
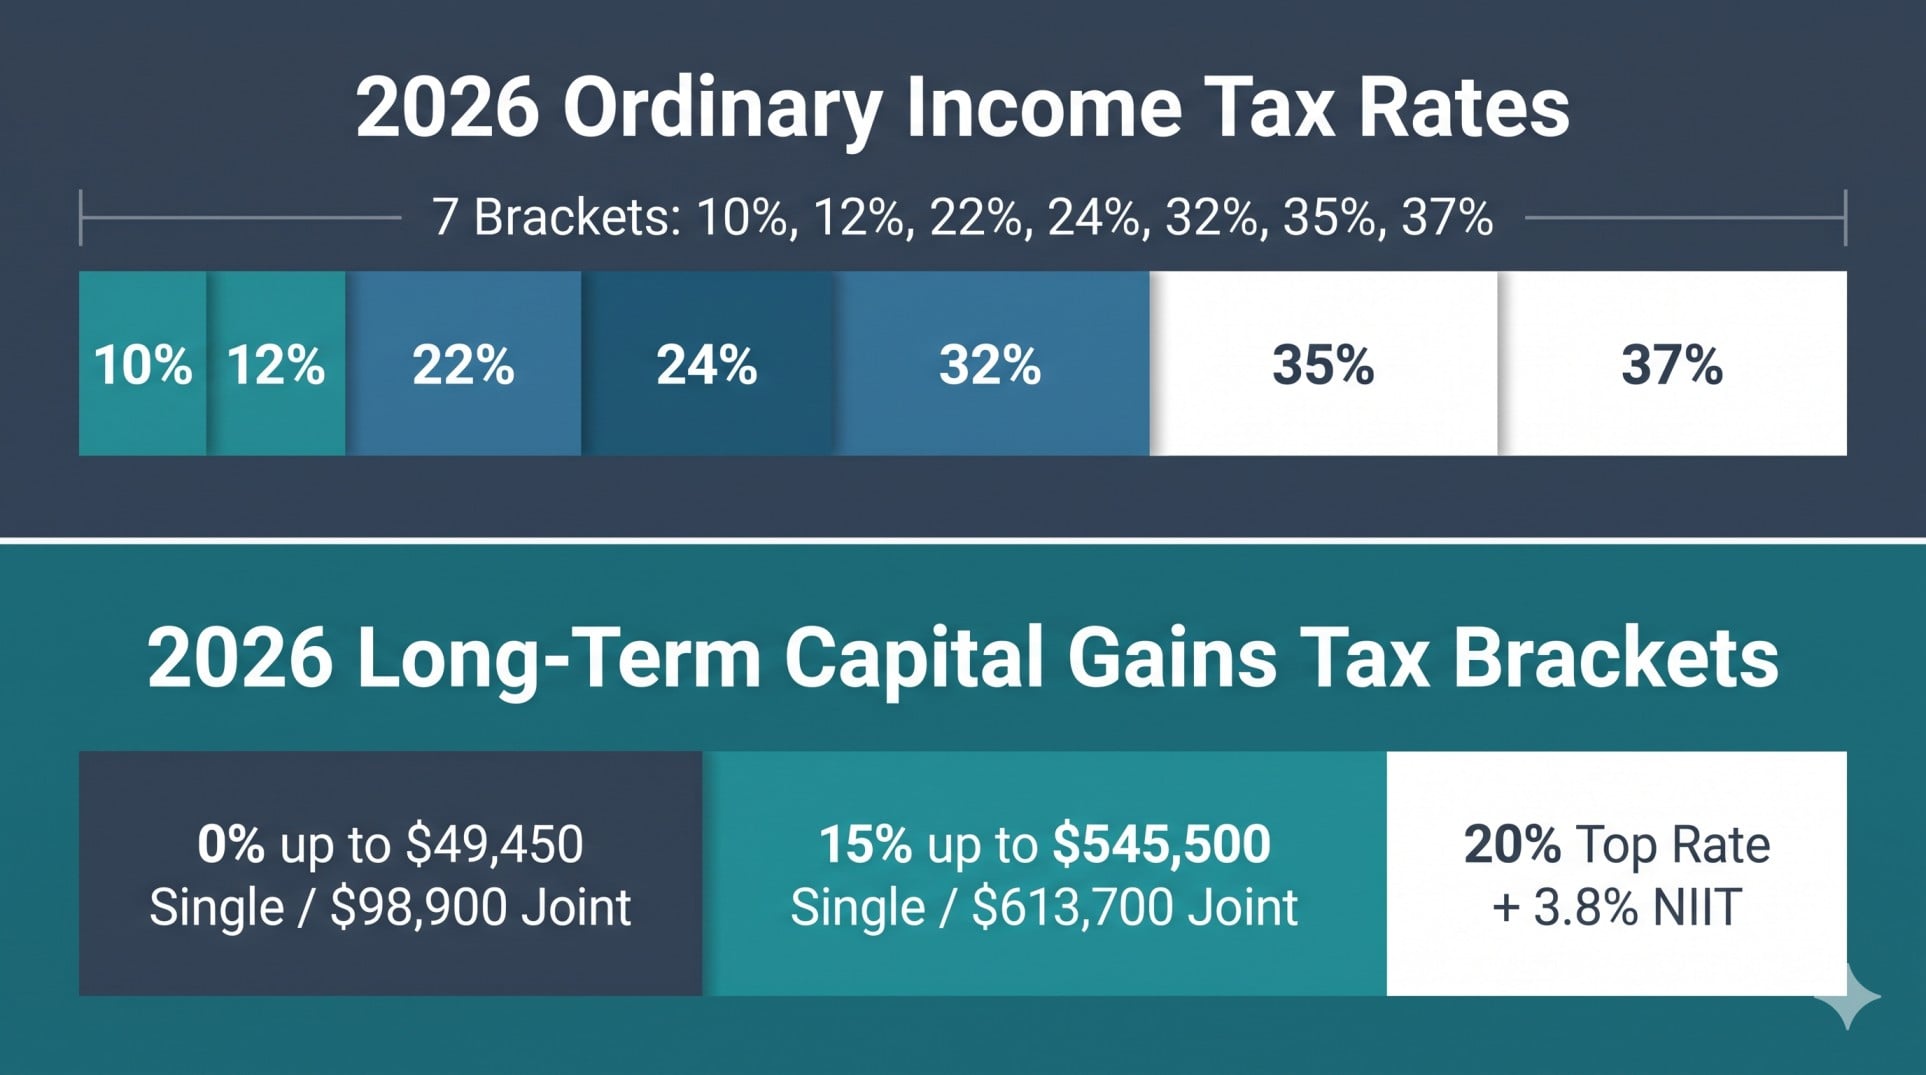
Checking the official 2026 tax brackets is the fastest way to project your federal tax bill, adjust your paycheck withholding, and time year-end investment moves. Under IRS Revenue Procedure 2025-32 and the permanent extensions in the One Big Beautiful Bill Act (OBBBA, P.L. 119-21), the seven federal marginal rates—10%, 12%, 22%, 24%, 32%, 35%, and 37%—remain locked in for Tax Year 2026 (for tax returns filed in 2027), while the income thresholds widened by roughly 2.2% to 4% to prevent inflation-driven “bracket creep.”
Knowing where your income lands across the 2026 federal income tax brackets is only the starting point. Because the IRS applies progressive rates solely to your Taxable Income on Form 1040, Line 15—after subtracting your $16,100 (Single) or $32,200 (Married Filing Jointly) standard deduction, retirement contributions, and Schedule 1-A bonus write-offs—your true tax burden is much lower than your top bracket percentage suggests.
⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- Seven Permanent Federal Tax Rates (Filed by April 15, 2027): Per Section 70101 of the One Big Beautiful Bill Act and IRS Revenue Procedure 2025-32, the 2026 rates are 10%, 12%, 22%, 24%, 32%, 35%, and 37%. The top 37% rate starts at $640,601 of taxable income for Single and Head of Household filers and $768,701 for Married Filing Jointly.
- Higher 2026 Standard Deduction & Senior Shield: Before entering the brackets, taxpayers subtract the 2026 standard deduction of $16,100 (Single/MFS), $24,150 (Head of Household), or $32,200 (Married Filing Jointly), plus $2,050 / $1,650 for age 65+ or blindness and up to $6,000 per senior on Schedule 1-A.
- 2026 Long-Term Capital Gains Thresholds: The 0% long-term capital gains rate applies up to $49,450 of taxable income for Single filers, $66,200 for Heads of Household, and $98,900 for Married Filing Jointly, while the 20% top rate begins above $545,500 (Single) and $613,700 (Joint).
- Major 2026 Credit, AMT & QBI Updates: For 2026, the Child Tax Credit holds at $2,200 per child ($1,700 refundable), the maximum Earned Income Tax Credit rises to $8,231, the Section 199A QBI phase-in starts at $201,775 Single & MFS ($201,750 HOH) / $403,500 Joint (with a new $400 minimum deduction), and AMT phaseouts reset to $500,000 Single / $1,000,000 Joint.
Table of Contents
- ⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- 2026 Tax Brackets and Federal Income Tax Rates by Filing Status
- 2025 Federal Income Tax Brackets by Filing Status (Year-Over-Year Comparison)
- How Do the 2026 Tax Brackets Work? Marginal vs. Effective Tax Rates
- 2026 Standard Deduction and Personal Exemption: What Changed for 2026?
- 2026 Capital Gains Tax Rates and Brackets (Long-Term Capital Gains)
- 2026 Alternative Minimum Tax (AMT) Exemptions and Phaseout Thresholds
- 2026 Earned Income Tax Credit (EITC) Parameters and Child Tax Credit
- 2026 Qualified Business Income Deduction (Sec. 199A) and Annual Gift Exclusion
- Potential Ways to Get Into a Lower Tax Bracket and Why Brackets Matter for Investors
- 4 Real-World Hypothetical Scenarios With Step-by-Step 2026 Tax Math
- Step-by-Step Guide: How to Figure Out Your Tax Bracket and File Your 2026 Return
- Federal vs. State Income Tax Brackets: Key Conformity Differences
- Frequently Asked Questions About 2026 Income Tax Brackets and Rates
- Final Year-End Tax Planning Checklist for 2026
2026 Tax Brackets and Federal Income Tax Rates by Filing Status
For Tax Year 2026 (returns filed in 2027), the IRS applies seven progressive federal income tax rates—10%, 12%, 22%, 24%, 32%, 35%, and 37%—across income ranges determined by your filing status: Single, Married Filing Jointly, Head of Household, or Married Filing Separately.
Every autumn, the IRS adjusts more than 60 tax provisions using the Chained Consumer Price Index (C-CPI-U) to stop inflation from pushing workers into higher tax tiers when their purchasing power hasn’t actually grown. Under Section 70101 of the One Big Beautiful Bill Act (P.L. 119-21), Congress made the seven TCJA rates permanent and gave the bottom 10% and 12% brackets an extra inflation adjustment starting in 2026 (~3.98% wider than 2025, while the 22% through 37% brackets expanded by ~2.27%).
2026 Federal Income Tax Brackets and Rates for Single Filers, Married Couples Filing Jointly, and Heads of Households
Use this master table from IRS Revenue Procedure 2025-32 (Section 4.01) to find your 2026 bracket based on your Taxable Income (Form 1040, Line 15)—not your gross salary:
| 2026 Tax Rate | Single Filers (Taxable Income) | Married Filing Jointly & Surviving Spouses | Head of Household (Taxable Income) | Married Filing Separately (Taxable Income) |
|---|---|---|---|---|
| 10% | $0 to $12,400 | $0 to $24,800 | $0 to $17,700 | $0 to $12,400 |
| 12% | $12,401 to $50,400 | $24,801 to $100,800 | $17,701 to $67,450 | $12,401 to $50,400 |
| 22% | $50,401 to $105,700 | $100,801 to $211,400 | $67,451 to $105,700 | $50,401 to $105,700 |
| 24% | $105,701 to $201,775 | $211,401 to $403,550 | $105,701 to $201,750 | $105,701 to $201,775 |
| 32% | $201,776 to $256,225 | $403,551 to $512,450 | $201,751 to $256,200 | $201,776 to $256,225 |
| 35% | $256,226 to $640,600 | $512,451 to $768,700 | $256,201 to $640,600 | $256,226 to $384,350 |
| 37% | Over $640,600 | Over $768,700 | Over $640,600 | Over $384,350 |
Exact 2026 IRS Tax Rate Schedules (Base Tax + Percentage Over Threshold)
When you or your tax software compute your exact 2026 federal tax liability on Form 1040, Line 16, the IRS uses a cumulative base-tax formula that sums the maximum tax from every lower bracket tier plus the marginal percentage on your dollars above the bracket floor:
| Filing Status | 10% Bracket | 12% Bracket Formula | 22% Bracket Formula | 24% Bracket Formula | 32% Bracket Formula | 35% Bracket Formula | 37% Top Bracket Formula |
|---|---|---|---|---|---|---|---|
| Single | 10% of taxable income (Max: $1,240) | $1,240 + 12% over $12,400 (Tier tax: $4,560) | $5,800 + 22% over $50,400 (Tier tax: $12,166) | $17,966 + 24% over $105,700 (Tier tax: $23,058) | $41,024 + 32% over $201,775 (Tier tax: $17,424) | $58,448 + 35% over $256,225 (Tier tax: $134,531.25) | $192,979.25 + 37% over $640,600 |
| Married Filing Jointly / QSS | 10% of taxable income (Max: $2,480) | $2,480 + 12% over $24,800 (Tier tax: $9,120) | $11,600 + 22% over $100,800 (Tier tax: $24,332) | $35,932 + 24% over $211,400 (Tier tax: $46,116) | $82,048 + 32% over $403,550 (Tier tax: $34,848) | $116,896 + 35% over $512,450 (Tier tax: $89,687.50) | $206,583.50 + 37% over $768,700 |
| Head of Household | 10% of taxable income (Max: $1,770) | $1,770 + 12% over $17,700 (Tier tax: $5,970) | $7,740 + 22% over $67,450 (Tier tax: $8,415) | $16,155 + 24% over $105,700 (Tier tax: $23,052) | $39,207 + 32% over $201,750 (Tier tax: $17,424) | $56,631 + 35% over $256,200 (Tier tax: $134,540) | $191,171.00 + 37% over $640,600 |
| Married Filing Separately | 10% of taxable income (Max: $1,240) | $1,240 + 12% over $12,400 (Tier tax: $4,560) | $5,800 + 22% over $50,400 (Tier tax: $12,166) | $17,966 + 24% over $105,700 (Tier tax: $23,058) | $41,024 + 32% over $201,775 (Tier tax: $17,424) | $58,448 + 35% over $256,225 (Tier tax: $44,843.75) | $103,291.75 + 37% over $384,350 |
2025 Federal Income Tax Brackets by Filing Status (Year-Over-Year Comparison)
Comparing the 2025 federal income tax brackets by filing status against the 2026 thresholds shows that every income tier expanded upward for 2026. If your taxable income stayed identical between 2025 and 2026, more of your money is taxed in the lower 10% and 12% tiers this year.
Whether you are finishing a prior-year return or comparing how much extra room you have inside the 2026 federal income tax brackets before crossing into the next rate tier, review the official 2025 table from IRS Revenue Procedure 2024-40 below:
| 2025 Tax Rate | 2025 Single Filers | 2025 Married Filing Jointly & QSS | 2025 Head of Household | 2025 Married Filing Separately | 2026 Single Threshold Increase |
|---|---|---|---|---|---|
| 10% | $0 to $11,925 | $0 to $23,850 | $0 to $17,000 | $0 to $11,925 | +$475 (+$950 Joint) |
| 12% | $11,926 to $48,475 | $23,851 to $96,950 | $17,001 to $64,850 | $11,926 to $48,475 | +$1,925 (+$3,850 Joint) |
| 22% | $48,476 to $103,350 | $96,951 to $206,700 | $64,851 to $103,350 | $48,476 to $103,350 | +$2,350 (+$4,700 Joint) |
| 24% | $103,351 to $197,300 | $206,701 to $394,600 | $103,351 to $197,300 | $103,351 to $197,300 | +$4,475 (+$8,950 Joint) |
| 32% | $197,301 to $250,525 | $394,601 to $501,050 | $197,301 to $250,500 | $197,301 to $250,525 | +$5,700 (+$11,400 Joint) |
| 35% | $250,526 to $626,350 | $501,051 to $751,600 | $250,501 to $626,350 | $250,526 to $375,800 | +$14,250 (+$17,100 Joint) |
| 37% | Over $626,350 | Over $751,600 | Over $626,350 | Over $375,800 | Starts $14,250 higher |
How Do the 2026 Tax Brackets Work? Marginal vs. Effective Tax Rates
The United States uses a progressive tax system where income is taxed in layered buckets rather than at a single flat rate. Moving into a higher tax bracket never causes all of your prior income to be taxed at that higher rate; only the dollars above the bracket cutoff face the higher percentage.
What Is a Tax Rate vs. What Is a Tax Bracket?
People frequently use the two terms interchangeably, but they serve distinct mechanical functions on your tax return. What is a tax rate? A tax rate is the specific percentage (such as 12% or 22%) at which a given slice of income is taxed. What is a tax bracket? A tax bracket is the statutory dollar range of taxable income (such as $12,401 to $50,400 for a single filer in 2026) to which that percentage applies.
What Is Your Federal Marginal Tax Rate?
Your federal marginal tax rate is the percentage of tax applied to the very next dollar of taxable income you earn—or the percentage you save on the very next dollar of tax-deductible expenses you claim. If you are a single filer with $100,000 of taxable income in 2026, your top dollar lands inside the $50,401 to $105,700 range, making your marginal tax rate 22%. Contributing an extra $1,000 to a pre-tax 401(k) trims $1,000 off that top layer, saving you exactly $220 in federal income tax ($1,000 × 22%).
What Is Your Federal Effective Tax Rate?
Your federal effective tax rate (also called your average tax rate) is the actual percentage of your total income that goes to the IRS after blending all of the lower progressive brackets together. You calculate your effective tax rate by dividing your total federal income tax (Form 1040, Line 24—or Line 16 before credits) by your total taxable income (or by your gross income for a holistic household view). Because your first dollars are always taxed at 10% and 12%, your effective rate is always noticeably lower than your marginal bracket.
Marginal vs. Effective Tax Rate: How $100,000 in Total Taxable Income for a Single Filer Is Taxed in 2026
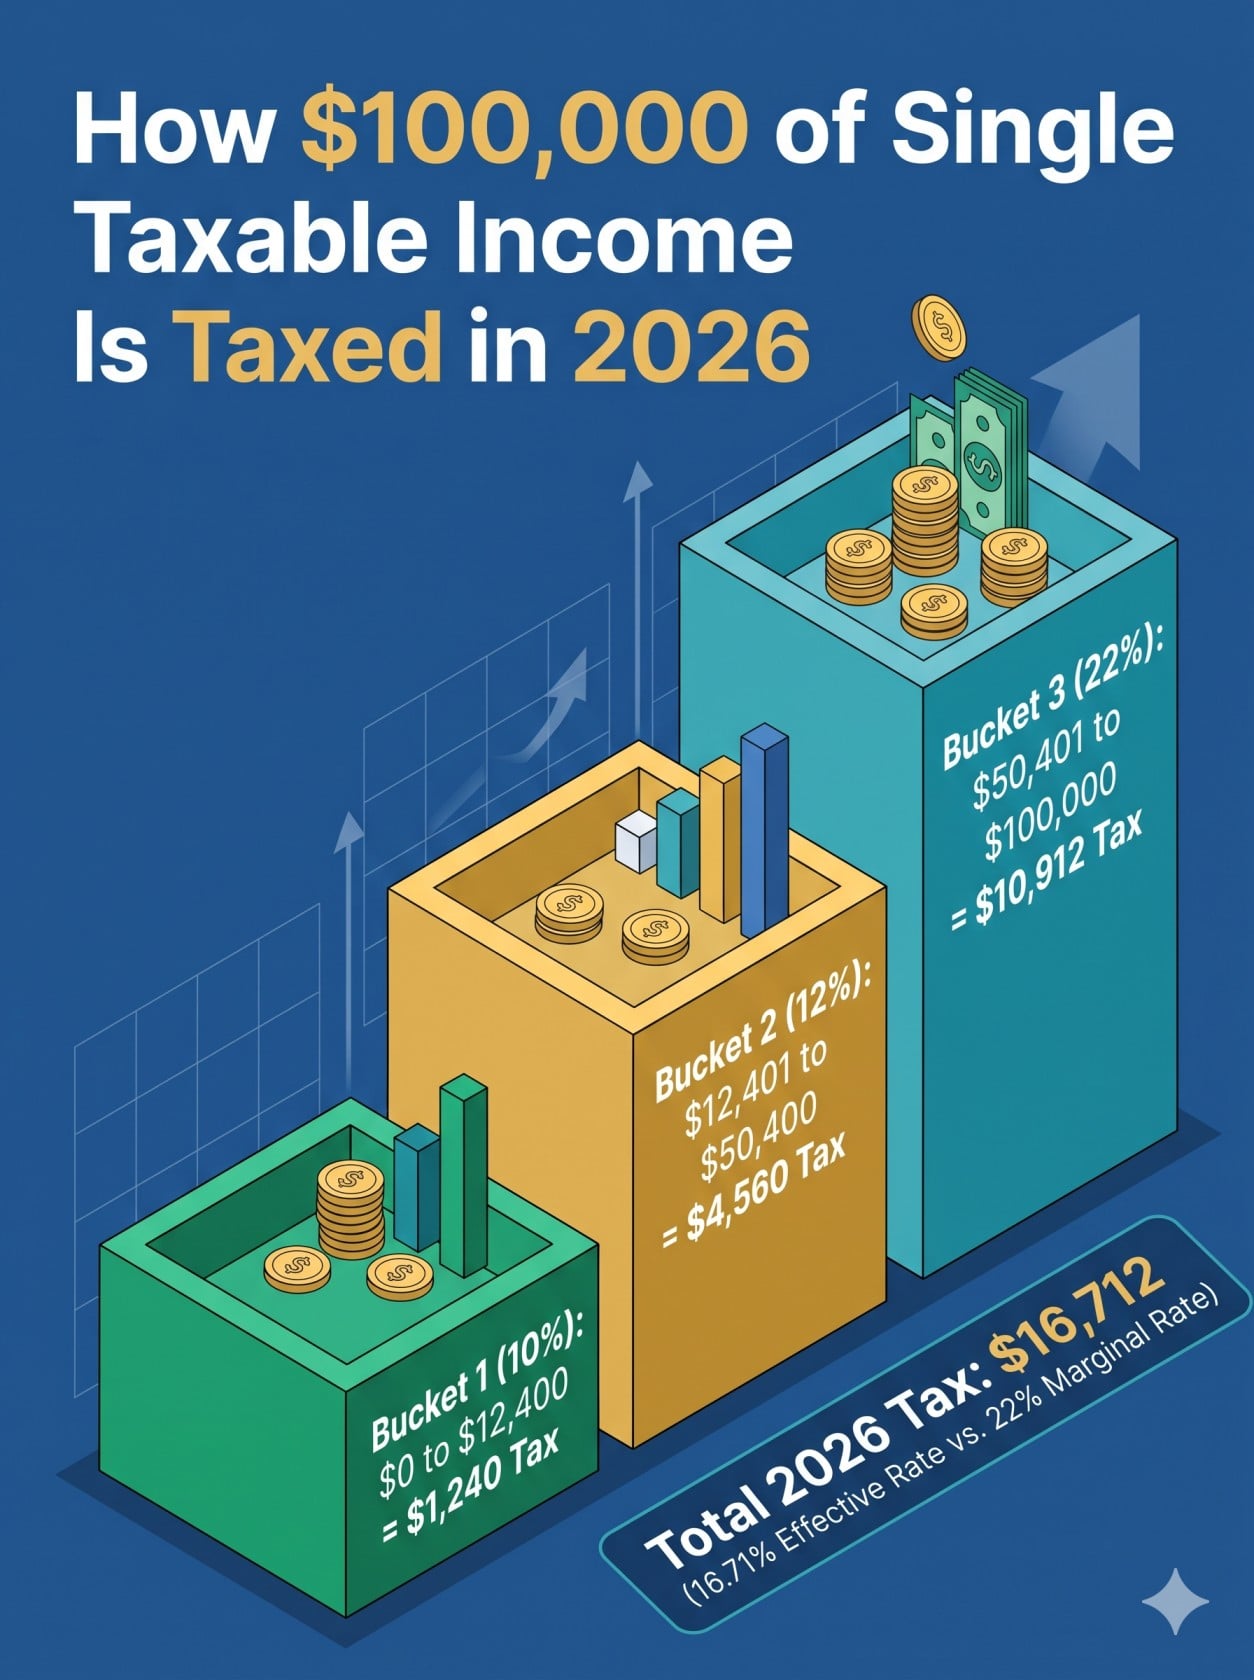
To see why a raise never results in lower take-home pay, look at the exact step-by-step math for how $100,000 in total taxable income for a single filer is taxed in 2026 (note that for a single worker taking the $16,100 standard deduction in 2026, having $100,000 of taxable income corresponds to $116,100 of gross salary):
- Bucket 1 (10% Bracket — $0 to $12,400): The first $12,400 of taxable income is taxed at 10% = $1,240.00.
- Bucket 2 (12% Bracket — $12,401 to $50,400): The next $38,000 of taxable income ($50,400 minus $12,400) is taxed at 12% = $4,560.00.
- Bucket 3 (22% Bracket — $50,401 to $100,000): The remaining $49,600 of taxable income ($100,000 minus $50,400) is taxed at 22% = $10,912.00.
- Total 2026 Federal Income Tax Owed: $1,240 + $4,560 + $10,912 = $16,712.00 (down $202 from the $16,914 tax on $100,000 in 2025!).
- Marginal vs. Effective Comparison: Even though this taxpayer is in the 22% marginal bracket, their effective tax rate on $100,000 of taxable income is only 16.71% ($16,712 ÷ $100,000)—and their effective rate on their $116,100 gross salary before the standard deduction is just 14.39%!
2026 Standard Deduction and Personal Exemption: What Changed for 2026?
For 2026, the basic standard deduction rises to $16,100 for Single and Married Filing Separately filers, $24,150 for Heads of Household, and $32,200 for Married Filing Jointly. The personal exemption remains permanently at $0, supplemented by a $6,000 bonus deduction for seniors age 65+.
When reviewing the 2026 standard deduction amounts by filing status: what changed for 2026?, two legislative updates from the One Big Beautiful Bill Act stand out. First, Congress permanently prevented the standard deduction from dropping back to pre-2018 levels and increased the 2026 amounts by $350 (Single/MFS), $525 (Head of Household), and $700 (Married Filing Jointly) over 2025. Second, while the 2026 Standard Deduction and Personal Exemption rules keep the general personal exemption at $0 under IRC Section 151(d)(5), taxpayers age 65 or older (born on or before January 1, 1962) can stack three layers of deductions in 2026. For complete rules on how these deductions work, read our complete guide to the 2026 standard deduction and our 2026 standard deduction for seniors over 65 guide.
| Filing Status | 2025 Base Standard Deduction | 2026 Base Standard Deduction (Line 12) | 2026 Extra Age 65+ or Blind Add-On (Line 12) | 2026 OBBBA Senior Bonus (Schedule 1-A / Line 13b)* | Max 2026 Total Shield for Seniors Age 65+* |
|---|---|---|---|---|---|
| Single | $15,750 | $16,100 | +$2,050 (+$4,100 if 65+ & blind) | +$6,000 | $24,150 ($26,200 if blind) |
| Married Filing Jointly | $31,500 | $32,200 | +$1,650 per spouse (+$3,300 both 65+) | +$6,000 per spouse (+$12,000 both 65+) | $47,500 (both 65+, not blind) |
| Head of Household | $23,625 | $24,150 | +$2,050 (+$4,100 if 65+ & blind) | +$6,000 | $32,200 ($34,250 if blind) |
| Qualifying Surviving Spouse | $31,500 | $32,200 | +$1,650 (+$3,300 if 65+ & blind) | +$6,000 | $39,850 ($41,500 if blind) |
| Married Filing Separately | $15,750 | $16,100 | +$1,650 per qualifying box | $0 (Ineligible) | $17,750 ($19,400 if blind) |
*The $6,000 per-person Schedule 1-A senior deduction applies for tax years 2025–2028 (available to both standard deduction filers and itemizers) and phases out at 6% of MAGI above $75,000 (Single/HOH/QSS) or $150,000 (Married Filing Jointly).
2026 Capital Gains Tax Rates and Brackets (Long-Term Capital Gains)
Profits from selling stocks, real estate, crypto, or business assets held for more than one year—along with qualified dividends—are taxed at preferential 2026 capital gains tax brackets of 0%, 15%, or 20% based on your total taxable income, while short-term gains held one year or less face ordinary tax rates.
When you calculate your tax using the Qualified Dividends and Capital Gain Tax Worksheet (or Schedule D Tax Worksheet), your ordinary taxable income sits at the bottom of the stack and your long-term capital gains sit on top. That means if a married couple filing jointly has $60,000 of ordinary taxable income after subtracting their $32,200 standard deduction, and realizes $50,000 of long-term capital gains in 2026, the first $38,900 of their capital gain fills up the 0% bracket (up to the $98,900 joint limit) completely tax-free, and only the remaining $11,100 is taxed at 15%!
| 2026 Long-Term Capital Gains & Qualified Dividends Rate | Single Filers (Taxable Income) | Married Filing Jointly & Surviving Spouses | Head of Household (Taxable Income) | Married Filing Separately (Taxable Income) |
|---|---|---|---|---|
| 0% Capital Gains Rate | $0 to $49,450 | $0 to $98,900 | $0 to $66,200 | $0 to $49,450 |
| 15% Capital Gains Rate | $49,451 to $545,500 | $98,901 to $613,700 | $66,201 to $579,600 | $49,451 to $306,850 |
| 20% Capital Gains Rate | Over $545,500 | Over $613,700 | Over $579,600 | Over $306,850 |
Don’t Forget the 3.8% Net Investment Income Tax (NIIT) & Special Capital Gains Rates
- The 3.8% NIIT Surtax (IRC Section 1411 / Form 8960): High earners whose Modified Adjusted Gross Income (MAGI) exceeds $200,000 (Single/HOH), $250,000 (Married Filing Jointly/QSS), or $125,000 (Married Filing Separately)—thresholds that are fixed by statute and not indexed for inflation—owe an extra 3.8% surtax on the lesser of their net investment income or their MAGI above the threshold. That brings the effective top federal capital gains rate to 18.8% (15% + 3.8%) or 23.8% (20% + 3.8%).
- 25% Unrecaptured Section 1250 Real Estate Depreciation Rate: When selling depreciated rental or commercial real estate held over one year, the portion of your gain attributable to prior straight-line depreciation is taxed at a maximum rate of 25%.
- 28% Collectibles & Section 1202 Rate: Long-term gains from selling physical gold, silver, coins, art, antiques, or stamps are taxed at up to 28%.
2026 Alternative Minimum Tax (AMT) Exemptions and Phaseout Thresholds
For 2026, the 2026 Alternative Minimum Tax (AMT) exemptions are $90,100 for Single and Head of Household filers, $140,200 for Married Filing Jointly, and $70,100 for Married Filing Separately. However, the One Big Beautiful Bill Act lowered the 2026 phaseout thresholds to $500,000 (Single) and $1,000,000 (Joint) and doubled the phaseout rate to 50%.
The 2026 Alternative Minimum Tax is a parallel federal tax system calculated on Form 6251 that adds back certain tax preferences—most notably the up-to-$40,400 State and Local Tax (SALT) deduction, incentive stock option (ISO) bargain elements upon exercise, and private activity bond interest—to arrive at Alternative Minimum Taxable Income (AMTI). After subtracting your AMT exemption, excess AMTI is taxed at 26% on the first $244,500 ($122,250 for Married Filing Separately) and 28% on any excess above $244,500.
Pay close attention to the 2026 Alternative Minimum Tax (AMT) exemption phaseout thresholds: in 2025, AMT exemptions didn’t begin phasing out until $626,350 (Single) and $1,252,700 (Joint) at a 25% rate. Under Section 70107 of the OBBBA, starting in 2026, the phaseout thresholds dropped back to $500,000 (Single/HOH/MFS) and $1,000,000 (Married Filing Jointly), and the exemption now shrinks by 50 cents for every dollar of AMTI above the threshold—meaning high-income executives exercising ISOs or claiming the $40,400 SALT deduction face higher AMT exposure in 2026 than in 2025!
| Filing Status | 2025 AMT Exemption | 2026 AMT Exemption (IRC §55(d)) | 2025 Phaseout Start (25% Rate) | 2026 Phaseout Start (50% Rate) | 2026 Complete AMT Exemption Phaseout |
|---|---|---|---|---|---|
| Single & Head of Household | $88,100 | $90,100 | $626,350 | $500,000 | $680,200 |
| Married Filing Jointly & Surviving Spouse | $137,000 | $140,200 | $1,252,700 | $1,000,000 | $1,280,400 |
| Married Filing Separately | $68,500 | $70,100 | $626,350 | $500,000 | $640,200 |
2026 Earned Income Tax Credit (EITC) Parameters and Child Tax Credit
For 2026, the maximum refundable 2026 Earned Income Tax Credit rises to $8,231 for families with three or more qualifying children, while the 2026 Child Tax Credit provides up to $2,200 per qualifying child under age 17 (with up to $1,700 refundable as the Additional Child Tax Credit).
2026 Earned Income Tax Credit (EITC) Parameters
Under IRS Revenue Procedure 2025-32 (Section 4.06), low- and moderate-income workers can claim the fully refundable EITC if their 2026 investment income (interest, dividends, capital gains, and passive rents) is $12,200 or less under IRC Section 32(i) and their earned income and AGI stay below these exact 2026 ceilings:
| Number of Qualifying Children | 2026 Maximum EITC Credit Amount | Single / HOH / QSS Phaseout Begins | Single / HOH / QSS Income Limit ($0 Credit) | Married Filing Jointly Phaseout Begins | Married Filing Jointly Income Limit ($0 Credit) |
|---|---|---|---|---|---|
| No Qualifying Children | $664 | $10,860 | $19,540 | $18,140 | $26,820 |
| 1 Qualifying Child | $4,427 | $23,890 | $51,593 | $31,160 | $58,863 |
| 2 Qualifying Children | $7,316 | $23,890 | $58,629 | $31,160 | $65,899 |
| 3 or More Qualifying Children | $8,231 | $23,890 | $62,974 | $31,160 | $70,244 |
2026 Child Tax Credit (CTC) Rules
Section 70104 of the One Big Beautiful Bill Act made the expanded Child Tax Credit permanent under IRC Section 24 and raised the maximum credit to $2,200 per qualifying child under age 17 (up from the old $2,000 TCJA amount). For 2026 (per Revenue Procedure 2025-32, Section 4.05), up to $1,700 per child is refundable via the Additional Child Tax Credit on Schedule 8812 (calculated as 15% of earned income exceeding $2,500). Older dependents (ages 17+, full-time college students ages 19–23, or qualifying elderly parents) qualify for the $500 nonrefundable Credit for Other Dependents (ODC). Both credits begin phasing out by $50 per $1,000 of MAGI above $200,000 (Single/HOH) or $400,000 (Married Filing Jointly).
2026 Qualified Business Income Deduction (Sec. 199A) and Annual Gift Exclusion
For 2026, the permanent 20% Qualified Business Income Deduction (Sec. 199A) begins phasing in W-2 wage and Specified Service Trade or Business (SSTB) limits at $201,775 of taxable income for Single and Married Filing Separately filers ($201,750 for Head of Household) and $403,500 for Married Filing Jointly, while the 2026 Annual Exclusion for Gifts holds at $19,000 per recipient.
2026 Qualified Business Income Deduction Thresholds & New $400 Minimum
Under Section 70105 of the One Big Beautiful Bill Act, Congress made the 20% Section 199A pass-through deduction permanent for sole proprietors (Schedule C), landlords with qualifying trade-or-business rentals (Schedule E), partners, and S-Corporation shareholders, and introduced two major taxpayer-friendly upgrades starting in 2026:
- Wider 2026 Phase-In Windows ($75,000 Single / $150,000 Joint): Previously, W-2 wage/property limits and Specified Service Trade or Business (SSTB—doctors, lawyers, consultants, accountants, financial advisors) disallowances phased in over a narrow $50,000 ($100,000 joint) range. Starting in 2026, the phase-in range expanded to $75,000 for non-joint filers and $150,000 for joint filers!
- New $400 Minimum QBI Deduction (IRC Section 199A(i)): Starting in tax year 2026, any taxpayer who has at least $1,000 of aggregate qualified business income from active trades or businesses in which they materially participate is guaranteed a minimum QBI deduction of $400 on Form 8995! Explore how business owners structure their entities in our S-Corporation vs. LLC tax comparison guide.
| Filing Status (2026 Section 199A QBI Thresholds) | Full 20% QBI Deduction Allowed (Taxable Income Before QBI) | 2026 Phase-In Window (W-2 / SSTB Limits Phase In) | SSTB Excluded & Full W-2 / UBIA Limits Apply Above: |
|---|---|---|---|
| Single & Married Filing Separately | $201,775 or less | $201,776 to $276,775 ($75,000 range) | $276,775 |
| Head of Household | $201,750 or less | $201,751 to $276,750 ($75,000 range) | $276,750 |
| Married Filing Jointly | $403,500 or less | $403,501 to $553,500 ($150,000 range) | $553,500 |
2026 Annual Exclusion for Gifts and $15 Million Estate Tax Exemption
Per Revenue Procedure 2025-32 (Section 4.41) and Section 70106 of the OBBBA, high-net-worth families have three major wealth-transfer thresholds for calendar year 2026:
- 2026 Annual Gift Tax Exclusion (IRC Section 2503(b)): $19,000 per recipient (or $38,000 per recipient for married couples who elect gift-splitting on Form 709). You can give $19,000 each to as many individuals as you wish in 2026 without filing a gift tax return or using a penny of your lifetime exemption.
- 2026 Annual Gift Exclusion to a Non-U.S.-Citizen Spouse (IRC Section 2523(i)): Increased to $194,000 for 2026 (up from $190,000 in 2025).
- 2026 Federal Estate, Gift & GST Lifetime Exemption (IRC Section 2010(c)(3)): Raised permanently by the OBBBA to $15,000,000 per individual ($30,000,000 for a married couple utilizing portability), up from $13,990,000 in 2025, with a top estate tax rate of 40% on taxable estates above that ceiling.
Potential Ways to Get Into a Lower Tax Bracket and Why Brackets Matter for Investors
Because tax brackets play a key role in tax planning decisions, reducing your Line 15 Taxable Income through pre-tax 401(k) and HSA contributions, Schedule 1-A deductions, and strategic capital gains harvesting can drop you out of the 22%, 24%, or 35% bracket into a lower marginal tier.
What Impacts Your Tax Rate? 6 Proven Ways to Drop Into a Lower 2026 Tax Bracket
Understanding what impacts your tax rate comes down to managing the levers between Gross Income and Line 15 Taxable Income before December 31, 2026:
- 1. Max Out Pre-Tax Workplace Retirement Accounts (2026 Limits): Every dollar contributed to a traditional 401(k), 403(b), 457(b), or federal Thrift Savings Plan is excluded from Box 1 of your W-2. For 2026 (per IRS Notice 2025-67), the base employee deferral limit is $24,500, plus an $8,000 catch-up contribution for workers age 50+ ($32,500 total)—or an enhanced $11,250 super catch-up for workers ages 60, 61, 62, or 63 ($35,750 total!). Note that starting in 2026 under SECURE 2.0, if your 2025 FICA wages from that employer exceeded $150,000, your catch-up contributions must go into a Roth 401(k) account rather than pre-tax. See our 2026 401(k) and IRA contribution limits guide for full details.
- 2. Fund a Triple-Tax-Advantaged Health Savings Account (HSA): If you are enrolled in an HSA-eligible high-deductible health plan in 2026 (per IRS Revenue Procedure 2025-19), you can deduct up to $4,400 for self-only coverage or $8,750 for family coverage (plus a $1,000 catch-up if age 55+).
- 3. Claim All 4 OBBBA Schedule 1-A Deductions on Line 13b: Even if you take the standard deduction in 2026, check whether you qualify for the $6,000 / $12,000 senior deduction (age 65+), up to $25,000 in qualified tips, up to $12,500 Single / $25,000 Married Filing Jointly in qualified FLSA overtime premium pay, or up to $10,000 in interest on a loan used to purchase a new U.S.-assembled passenger vehicle. Read our 2026 no tax on overtime and tips guide to verify your eligibility.
- 4. Deduct Up to $1,000 ($2,000 Joint) in Cash Charity Without Itemizing—or Bunch Into Schedule A: Starting in 2026, non-itemizers can deduct $1,000 (Single) or $2,000 (MFJ) in cash gifts to public charities, while itemizers with high state taxes can utilize the expanded $40,400 SALT cap.
- 5. Tax-Loss Harvesting in Brokerage Accounts (IRC Section 1211(b)): Selling losing stock or crypto positions before December 31 offsets 100% of your realized capital gains—and if your net capital losses exceed your gains, you can deduct up to $3,000 ($1,500 MFS) against your ordinary W-2 income every year and carry the rest forward indefinitely.
- 6. Qualified Charitable Distributions (QCDs) for Retirees Age 70½+: In 2026, individuals age 70½ or older can transfer up to $111,000 per person directly from a Traditional IRA to charity, satisfying Required Minimum Distributions (RMDs) without adding a dollar to AGI.
Why Tax Brackets Matter for Investors
Knowing why tax brackets matter for investors is critical when choosing between tax-free municipal bonds and taxable corporate bonds, or deciding whether to do a Roth conversion. To compare a tax-free municipal bond yield against a taxable bond yield, divide the municipal bond yield by (1 − your marginal tax rate). For example, if a married couple in the 35% federal bracket (plus the 3.8% NIIT = 38.8% combined federal rate) buys a tax-free municipal bond yielding 4.00%, its taxable equivalent yield is 4.00% ÷ (1 − 0.388) = 6.54%! Conversely, an investor in the 12% bracket only gets a 4.55% taxable equivalent yield from that same municipal bond.
4 Real-World Hypothetical Scenarios With Step-by-Step 2026 Tax Math
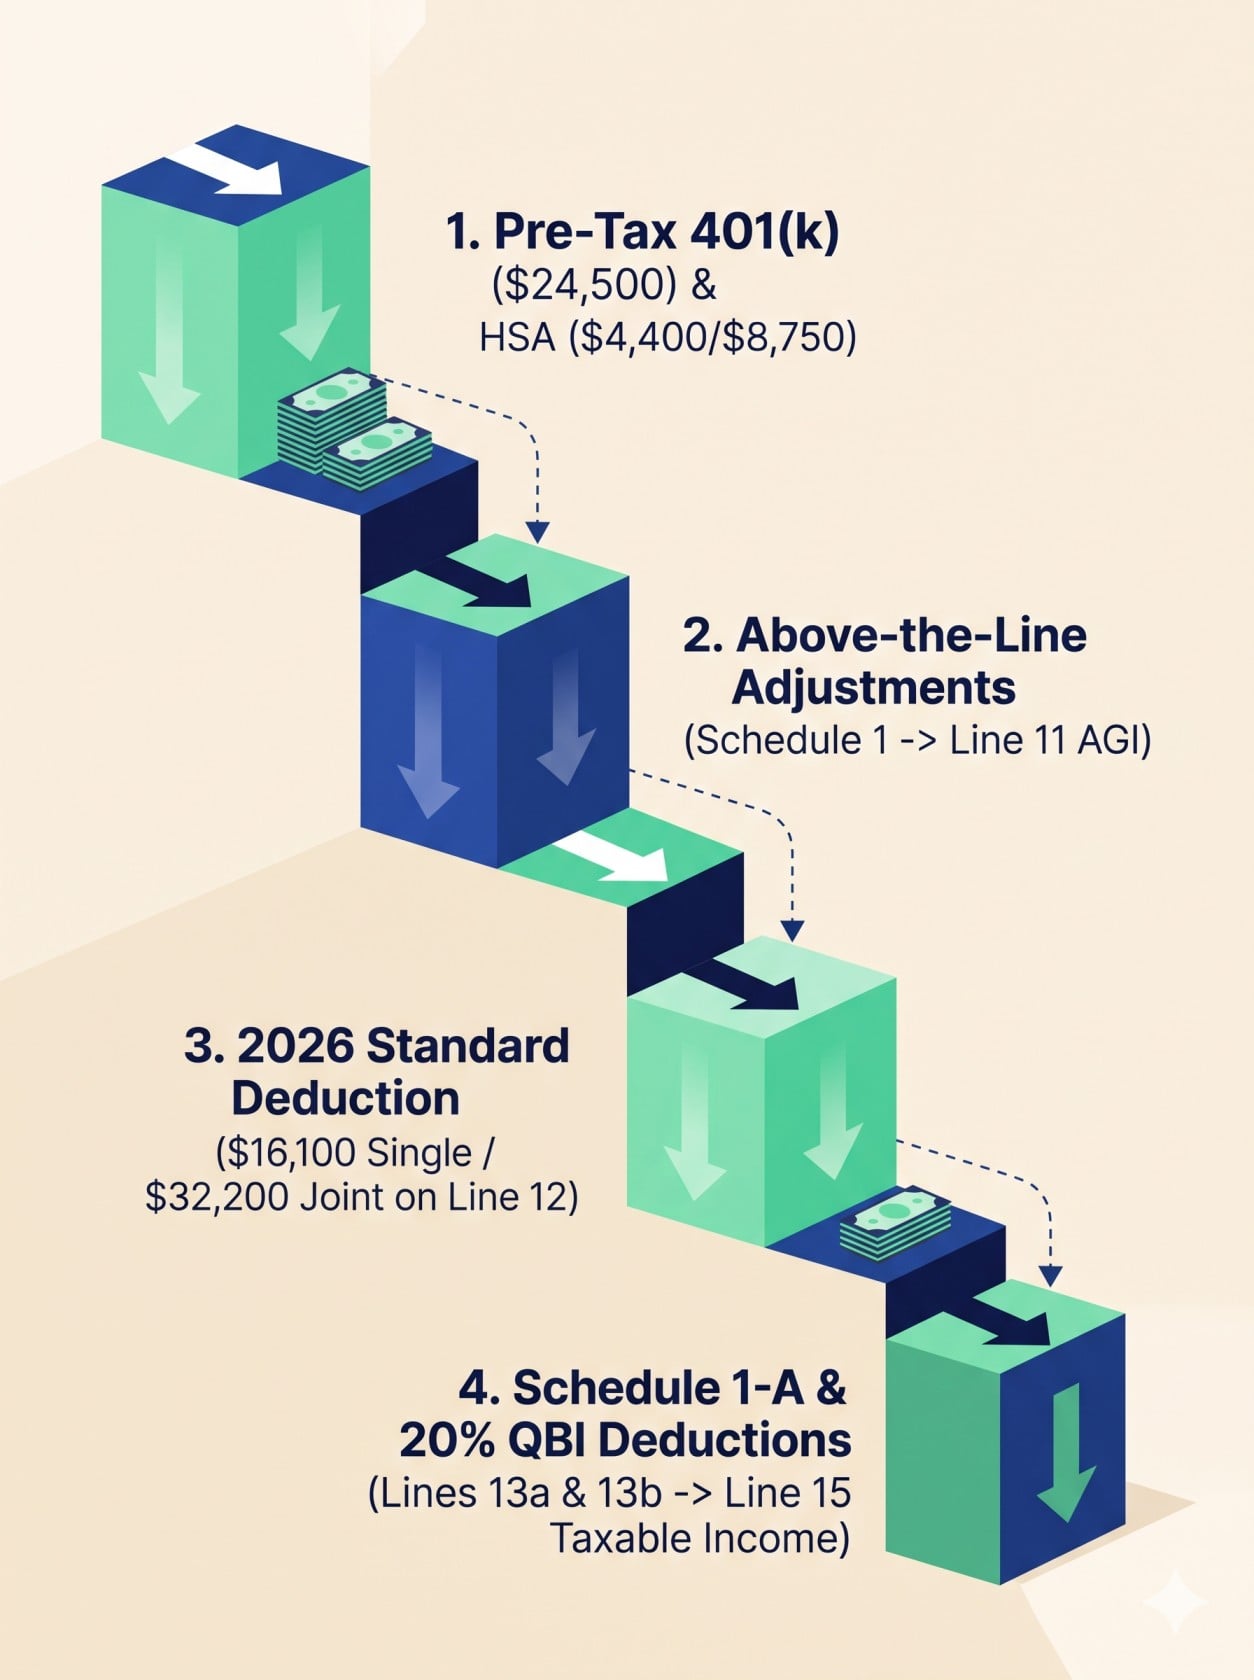
To see how household income flows through the 2026 tax brackets after subtracting pre-tax retirement contributions, the standard deduction, Schedule 1-A write-offs, and capital gains tiers, examine these four detailed scenarios with complete bracket-by-bracket calculations.
Scenario 1: The Single Software Engineer Knocking $145,000 Gross Salary Out of the 24% Bracket
Taxpayer Profile: Jordan, age 34, is a single software developer in Washington State. In 2026, Jordan earns a gross salary of $145,000. Without retirement planning, subtracting only the $16,100 single standard deduction would leave $128,900 of taxable income—pushing $23,200 into the 24% bracket (which starts at $105,701 in 2026).
- Strategic 2026 Moves: Jordan contributes the maximum $24,500 to a pre-tax 401(k), contributes the maximum $4,400 to an individual Health Savings Account (HSA), and donates $1,000 in cash to a qualified 501(c)(3) food bank.
- Calculating 2026 Line 15 Taxable Income:
- Gross Salary: $145,000 minus $24,500 (pre-tax 401(k)) minus $4,400 (HSA) = $116,100 Adjusted Gross Income (Line 11).
- Less 2026 Single Standard Deduction (Line 12): -$16,100.
- Less 2026 Non-Itemizer Cash Charitable Deduction: -$1,000.
- 2026 Taxable Income (Line 15): $99,000 (completely eliminating all income in the 24% bracket!).
- 2026 Progressive Bracket Math on $99,000 (Single):
- 10% Bracket ($0 to $12,400): $12,400 × 10% = $1,240.00.
- 12% Bracket ($12,401 to $50,400): ($50,400 − $12,400 = $38,000) × 12% = $4,560.00.
- 22% Bracket ($50,401 to $99,000): ($99,000 − $50,400 = $48,600) × 22% = $10,692.00.
- Total 2026 Federal Tax: $1,240 + $4,560 + $10,692 = $16,492.00 (saves $7,042 compared to the $23,534 tax on $128,900 without the 401(k), HSA, and charity moves!).
- Marginal Rate: 22% | Effective Rate on $99,000 Taxable Income: 16.66% | Effective Rate on $145,000 Gross Income: 11.37%.
Scenario 2: Married Couple With 2 Children, Overtime Pay, and the $2,200 Child Tax Credit
Taxpayer Profile: Carlos (age 38) and Hannah (age 36) file Married Filing Jointly in 2026 with two children, ages 6 and 9. Their combined gross W-2 income is $152,000, which includes $10,000 of qualified FLSA overtime premium pay earned by Carlos. They claim the standard deduction.
- Step 1 (2026 Deductions — Line 12 + Schedule 1-A Line 13b): Carlos and Hannah subtract the 2026 Married Filing Jointly standard deduction of $32,200 on Line 12. Because their $152,000 MAGI is below the $300,000 joint phase-out floor for the overtime deduction, they also deduct Carlos’s full $10,000 overtime premium on Schedule 1-A (Line 13b). Their total deductions are $42,200, leaving $109,800 of Taxable Income on Line 15.
- Step 2 (2026 Joint Progressive Bracket Math on $109,800):
- 10% Bracket ($0 to $24,800): $24,800 × 10% = $2,480.00.
- 12% Bracket ($24,801 to $100,800): ($100,800 − $24,800 = $76,000) × 12% = $9,120.00.
- 22% Bracket ($100,801 to $109,800): ($109,800 − $100,800 = $9,000) × 22% = $1,980.00.
- Line 16 Tax Before Credits: $2,480 + $9,120 + $1,980 = $13,580.00.
- Step 3 (Subtracting the 2026 Child Tax Credit): With two qualifying children under age 17, they subtract $4,400 ($2,200 × 2) on Form 1040, Line 19. Their final 2026 federal income tax bill drops to $9,180.00—an effective tax rate of just 6.04% on their $152,000 household salary!
Scenario 3: Self-Employed Consultant Utilizing the 2026 Section 199A QBI Deduction
Taxpayer Profile: Priya, age 44, is a single IT systems consultant operating as a sole proprietor (Schedule C). In 2026, after deducting business expenses, her net Schedule C profit is $190,000. She pays $16,000 in self-employed health insurance premiums and takes the 2026 single standard deduction.
- Step 1 (Self-Employment Tax & AGI): On Schedule SE, Priya’s net earnings from self-employment are $190,000 × 92.35% = $175,465 (below the $184,500 2026 Social Security wage cap). Her 15.3% SE tax is $26,846, giving her a $13,423 above-the-line deduction (50% of SE tax) on Schedule 1, plus her $16,000 self-employed health insurance deduction. Her 2026 AGI (Line 11) is $190,000 − $13,423 − $16,000 = $160,577.
- Step 2 (Standard Deduction & 20% Section 199A QBI Deduction):
- Subtracting the $16,100 single standard deduction leaves $144,477 of taxable income before the QBI deduction.
- Because $144,477 is well below the $201,775 single Section 199A threshold for 2026, Priya qualifies for the full 20% QBI deduction even though consulting is a Specified Service Trade or Business (SSTB)!
- Her net QBI is $160,577 × 20% = $32,115, capped at 20% of her taxable income before QBI ($144,477 × 20% = $28,895) on Line 13a.
- Step 3 (2026 Progressive Bracket Math on $115,582 Taxable Income): Subtracting the $28,895 QBI deduction from $144,477 leaves $115,582 of Taxable Income on Line 15:
- 10% Bracket ($0 to $12,400): $12,400 × 10% = $1,240.00.
- 12% Bracket ($12,401 to $50,400): ($50,400 − $12,400 = $38,000) × 12% = $4,560.00.
- 22% Bracket ($50,401 to $105,700): ($105,700 − $50,400 = $55,300) × 22% = $12,166.00 (Cumulative base tax through $105,700 = $17,966.00).
- 24% Bracket ($105,701 to $115,582): ($115,582 − $105,700 = $9,882) × 24% = $2,371.68.
- Total Regular 2026 Federal Income Tax: $17,966.00 + $2,371.68 = $20,337.68 (with the Section 199A QBI deduction alone saving her $6,934.80 in federal income tax!).
Scenario 4: Retired Couple Stacking Ordinary Income + 0% and 15% Long-Term Capital Gains
Taxpayer Profile: Richard (age 68) and Diane (age 66) file Married Filing Jointly in 2026. They have $95,000 in ordinary income (pension, IRA withdrawals, and taxable Social Security) plus $60,000 in long-term capital gains from selling stock held for five years (total 2026 AGI and MAGI on Line 11 of $155,000).
- Step 1 (2026 Senior Deductions With Partial MAGI Phase-Out):
- Line 12 Standard Deduction (Married, Both 65+): $32,200 base + $3,300 age add-on = $35,500.
- Line 13b Schedule 1-A Senior Bonus: Because their $155,000 MAGI exceeds the $150,000 joint floor by $5,000, each spouse’s $6,000 deduction is reduced by 6% of $5,000 ($300 each = $600 total reduction), leaving an allowed Schedule 1-A deduction of $11,400 ($12,000 − $600).
- Total 2026 Deductions (Line 14): $35,500 + $11,400 = $46,900.
- Step 2 (Splitting Ordinary Bracket Math vs. Stacked Capital Gains Brackets):
- Total Line 15 Taxable Income: $155,000 AGI minus $46,900 = $108,100.
- Ordinary Taxable Income at the Bottom of the Stack ($48,100): $95,000 ordinary income minus $46,900 deductions = $48,100:
- 10% Bracket ($0 to $24,800): $24,800 × 10% = $2,480.00.
- 12% Bracket ($24,801 to $48,100): ($48,100 − $24,800 = $23,300) × 12% = $2,796.00.
- Total Ordinary Income Tax: $2,480 + $2,796 = $5,276.00.
- Long-Term Capital Gains Stacked on Top ($48,101 to $108,100): The 0% joint capital gains bracket in 2026 extends up to $98,900 of total taxable income:
- 0% Capital Gains Bracket ($48,101 to $98,900): ($98,900 − $48,100 = $50,800 of capital gain) × 0% = $0.00.
- 15% Capital Gains Bracket ($98,901 to $108,100): ($108,100 − $98,900 = $9,200 of capital gain) × 15% = $1,380.00.
- Total 2026 Federal Tax on $155,000 of Income: $5,276.00 + $1,380.00 = $6,656.00—an effective tax rate of just 4.29%!
Step-by-Step Guide: How to Figure Out Your Tax Bracket and File Your 2026 Return
When asking how do you figure out what tax bracket you’re in for your 2026 return (filed by April 15, 2027), never look up your gross salary on the bracket chart. Follow this five-step Form 1040 sequence to find your exact Line 15 Taxable Income and Line 16 tax.
- Step 1: Total Your Gross Income and Subtract Schedule 1 Adjustments to Find Line 11 AGI. Combine your W-2 wages (Line 1a), taxable interest and ordinary dividends (Lines 2b and 3b), taxable IRA/pension distributions and Social Security (Lines 4b, 5b, and 6b), capital gains from Form 8949 and Schedule D (Line 7), and business/rental income from Schedule 1 (Line 8) to get Total Income on Line 9. Subtract your above-the-line adjustments from Schedule 1, Part II (HSA, IRA, 50% of SE tax, student loan interest) on Line 10 to arrive at your Adjusted Gross Income (AGI) on Form 1040, Line 11.
- Step 2: Subtract Your 2026 Standard Deduction (or Schedule A) on Line 12 and Bonus Deductions on Lines 13a & 13b. Enter your 2026 standard deduction ($16,100 Single/MFS, $24,150 HOH, or $32,200 MFJ, plus age-65/blind add-ons and up to $1,000/$2,000 in non-itemizer cash charity) or your Schedule A itemized total on Line 12. Enter any 20% Section 199A QBI deduction from Form 8995 on Line 13a and any OBBBA bonus deductions from Schedule 1-A ($6,000 senior, tips, overtime, auto loan interest) on Line 13b.
- Step 3: Compute Your 2026 Taxable Income on Form 1040, Line 15. Subtract Line 14 (the sum of Lines 12, 13a, and 13b) from your Line 11 AGI. This figure on Line 15 is your official 2026 Taxable Income. Look up this exact number (minus any net capital gains/qualified dividends) in the 2026 bracket chart for your filing status to identify your marginal tax bracket.
- Step 4: Calculate Your Line 16 Tax Using the Correct IRS Method.
- If your Line 15 Taxable Income is under $100,000 and you have no qualified dividends or net capital gains, the IRS requires you to look up your exact $50 income increment in the 2026 IRS Tax Table in the Form 1040 instructions.
- If your Line 15 Taxable Income is $100,000 or more (with no capital gains/qualified dividends), use the 2026 Tax Computation Worksheet (which matches our Base Tax + Percentage Over Threshold table in Section 1).
- If you have any qualified dividends (Line 3a) or net long-term capital gains (Line 7 / Schedule D), you must use the Qualified Dividends and Capital Gain Tax Worksheet so your gains receive the lower 0%, 15%, or 20% rates.
- Step 5: Add AMT (Form 6251) on Line 17 and Subtract Tax Credits on Lines 19–31. Add any Alternative Minimum Tax from Form 6251 on Line 17, then subtract nonrefundable credits (such as the $2,200 Child Tax Credit on Line 19) and refundable credits (such as the EITC on Line 27 and Additional Child Tax Credit on Line 28) to determine your final refund or balance due by April 15, 2027.
Federal vs. State Income Tax Brackets: Key Conformity Differences
Your federal tax bracket only governs your IRS tax bill; state income tax rates are set independently by state legislatures and range from 0% in nine states up to 13.3% in California (or over 14% when including New York City or local wage taxes).
When estimating your combined household marginal tax rate for 2026, factor in which of the three state tax structures applies where you live:
- 9 States With 0% State Wage Income Tax: Residents of Alaska, Florida, Nevada, New Hampshire (which repealed its interest and dividends tax starting in 2025), South Dakota, Tennessee, Texas, Washington (which levies a 7% to 9.9% excise tax only on high-tier long-term capital gains exceeding an inflation-adjusted threshold over $270,000), and Wyoming pay zero state income tax on salaries, pensions, or retirement withdrawals.
- 14 Flat-Rate Income Tax States: States including Arizona (2.5%), Colorado (4.4%), Georgia (5.19%), Idaho, Illinois (4.95%), Indiana (2.95%), Iowa (3.8%), Kentucky (3.5%), Massachusetts (5% + 4% millionaire surtax), Michigan (4.25%), Mississippi, North Carolina (3.99%), Pennsylvania (3.07%), and Utah (4.5%) apply a single flat tax rate rather than graduated brackets.
- Graduated Progressive Bracket States (e.g., California, New York, New Jersey, Oregon, Minnesota, Hawaii): High-bracket states stack their progressive rates on top of the federal tiers—and almost none of them give preferential rates to long-term capital gains! In California, a married couple selling appreciated stock is taxed at up to 13.3% at the state level on top of the 20% + 3.8% NIIT federal rate, creating a combined 37.1% capital gains rate.
Frequently Asked Questions About 2026 Income Tax Brackets and Rates
1. What are the 7 federal income tax brackets for 2026?
For Tax Year 2026 (returns filed in 2027), the seven federal marginal income tax rates are 10%, 12%, 22%, 24%, 32%, 35%, and 37%. Under the One Big Beautiful Bill Act (P.L. 119-21), Congress made these seven TCJA rates permanent and widened the income thresholds for inflation under IRS Revenue Procedure 2025-32, with the top 37% bracket starting at $640,601 for Single and Head of Household filers and $768,701 for Married Filing Jointly.
2. If I get a raise or bonus that pushes me into a higher 2026 tax bracket, will I take home less money?
No—it is mathematically impossible for a raise or bonus to reduce your take-home pay solely from moving into a higher federal tax bracket. Because the U.S. tax system is progressive, your existing income continues to be taxed at the lower 10%, 12%, and 22% rates, and only the exact dollars exceeding the new bracket threshold are taxed at the higher marginal tax rate.
3. Are the 2026 tax brackets based on my gross salary or my taxable income?
Federal tax brackets are always based on your Taxable Income (Form 1040, Line 15), never your gross salary or Adjusted Gross Income (Line 11). If you are a single filer earning $65,000 in gross W-2 salary in 2026 and take the $16,100 standard deduction, your taxable income is $48,900—which keeps you completely inside the 12% bracket (up to $50,400) rather than the 22% bracket!
4. How are bonuses, RSUs, and supplemental wages withheld in 2026 compared to my actual tax bracket?
Under federal payroll rules linked to the third-lowest tax rate, employers typically withhold federal income tax on bonuses, commissions, and Restricted Stock Unit (RSU) vesting at a flat 22% supplemental wage rate on amounts up to $1 million (and 37% on supplemental wages exceeding $1 million). However, when you file your 2026 Form 1040, that bonus is added to your regular taxable income and taxed at your actual marginal rate—meaning you will get a refund if you are in the 12% bracket or owe the difference if you are in the 32%, 35%, or 37% bracket.
5. What is the 0% capital gains tax bracket limit for 2026?
For 2026, you pay 0% federal capital gains tax on long-term capital gains and qualified dividends to the extent your total taxable income (including the gains) stays at or below $49,450 for Single and Married Filing Separately filers, $66,200 for Head of Household filers, and $98,900 for Married Filing Jointly and Qualifying Surviving Spouse filers.
6. Did the Child Tax Credit increase for the 2026 tax year?
Yes, compared to the old $2,000 TCJA limit, the One Big Beautiful Bill Act permanently increased the maximum Child Tax Credit to $2,200 per qualifying child under age 17 (indexed for inflation moving forward), with up to $1,700 per child refundable via the Additional Child Tax Credit on Schedule 8812 for 2026.
7. Why did my Alternative Minimum Tax (AMT) exposure go up in 2026?
While the 2026 AMT exemption amounts increased for inflation to $90,100 (Single/HOH) and $140,200 (Married Filing Jointly), Section 70107 of the One Big Beautiful Bill Act lowered the AMTI exemption phaseout thresholds from $626,350/$1,252,700 (in 2025) down to $500,000 (Single) and $1,000,000 (Joint) for 2026, and doubled the phaseout clawback rate from 25% to 50%—causing high-income earners with large SALT deductions or ISO exercises to lose their AMT exemption much faster.
8. What are the 2026 tax brackets for Estates and Trusts (Form 1041)?
Unlike individuals who enjoy wide progressive brackets, non-grantor estates and trusts reach the top 37% federal tax rate almost immediately in 2026. Under IRS Revenue Procedure 2025-32, estates and trusts have four condensed 2026 brackets: 10% on taxable income from $0 to $3,300; 24% from $3,301 to $11,700; 35% from $11,701 to $16,000; and 37% on any undistributed trust taxable income over $16,000.
9. When are 2026 estimated tax payments and the final 2026 tax return due?
For the 2026 tax year, quarterly estimated tax payments on Form 1040-ES are due on April 15, 2026 (Q1), June 15, 2026 (Q2), September 15, 2026 (Q3), and January 15, 2027 (Q4). Your annual 2026 Form 1040 or Form 1040-SR return and any remaining tax balance are due on April 15, 2027 (or October 15, 2027 with a timely Form 4868 extension).
Final Year-End Tax Planning Checklist for 2026
Mastering the 2026 tax brackets and federal income tax rates gives you complete control over how much of your hard-earned income stays in your account versus going to the U.S. Treasury. Because the wider inflation thresholds in IRS Revenue Procedure 2025-32 pair with the permanent $16,100 / $32,200 standard deduction, the $40,400 SALT cap, and the four temporary Schedule 1-A write-offs, proactive households have more room than ever to keep their taxable income out of the top tiers.
Before December 31, 2026, run your projected income through the 2026 federal income tax brackets above: check how close your Line 15 Taxable Income sits to the next bracket jump (especially the 12% to 22% jump at $50,400 Single / $100,800 Joint, and the 24% to 32% jump at $201,775 Single / $403,550 Joint), top off your $24,500 401(k) and $4,400 / $8,750 HSA limits, harvest any 0% long-term capital gains room, and adjust your Form W-4 or Q4 estimated tax payment before January 15, 2027.
Disclaimer: This content provides general information for educational purposes only and reflects federal tax laws applicable to Tax Year 2026 (returns filed in 2027). Tax laws are complex and subject to change. This article does not constitute professional tax, legal, or accounting advice. Always consult a certified public accountant (CPA), enrolled agent (EA), or qualified tax attorney regarding your specific financial situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.

Your method of explaining the whole thing in this piece of writing is genuinely fastidious, every one be capable of
without difficulty be aware of it, Thanks a lot.
Hmm it appears like your site ate my first comment (it was super
long) so I guess I’ll just sum it up what I wrote and say,
I’m thoroughly enjoying your blog. I as well
am an aspiring blog blogger but I’m still new to everything.
Do you have any tips for novice blog writers?
I’d genuinely appreciate it.
My brother recommended I may like this blog.
He used to be entirely right. This post actually made my day.
You cann’t consider simply how a lot time I had spent for this info!
Thank you!
It’s a shame you don’t have a donate button!
I’d certainly donate to this superb blog!
I suppose for now i’ll settle for book-marking and adding your RSS feed to my
Google account. I look forward to fresh updates and will talk about this site with my Facebook group.
Talk soon!
This is my first time visit at here and i am in fact happy
to read everthing at single place.
Hey there great blog! Does running a blog like this take a
great deal of work? I’ve no understanding of computer programming but I had
been hoping to start my own blog soon. Anyhow,
if you have any ideas or techniques for new blog owners please share.
I understand this is off subject nevertheless I just needed
to ask. Thank you!
Wow, marvelous weblog layout! How long have you ever been running a blog for?
you make blogging look easy. The total glance of your web site is fantastic,
let alone the content material!
Excellent blog you’ve got here.. It’s difficult to find high quality writing like yours nowadays.
I really appreciate people like you! Take care!!
Awesome site you have here but I was curious about if you knew of any community
forums that cover the same topics talked about in this article?
I’d really like to be a part of community where I can get suggestions from other knowledgeable people that
share the same interest. If you have any suggestions, please let me
know. Cheers!
Hi there, I think your website may be having browser compatibility
problems. Whenever I take a look at your website in Safari,
it looks fine however when opening in IE, it’s got some overlapping issues.
I merely wanted to give you a quick heads
up! Besides that, excellent blog!
Superb, what a webpage it is! This blog provides useful data to us, keep it up.