
⚡ Executive Summary: 2026 Senior Standard & Bonus Deduction Totals
- 2026 Base + Age 65 Standard Deduction (Line 12): Under IRS Revenue Procedure 2025-32, a single filer age 65 or older receives $18,150 ($16,100 base + $2,050 age add-on). A married couple filing jointly receives $33,850 if one spouse is 65+ ($32,200 base + $1,650) or $35,500 if both spouses are 65+ ($32,200 base + $3,300).
- The $6,000 Enhanced Senior Deduction (Schedule 1-A / Line 13b): Under Section 70103 of the One Big Beautiful Bill Act (IRC Section 151(d)(5)(C)), taxpayers age 65+ can claim a separate deduction of up to $6,000 per qualifying individual ($12,000 for married couples where both are 65+) for tax years 2025 through 2028.
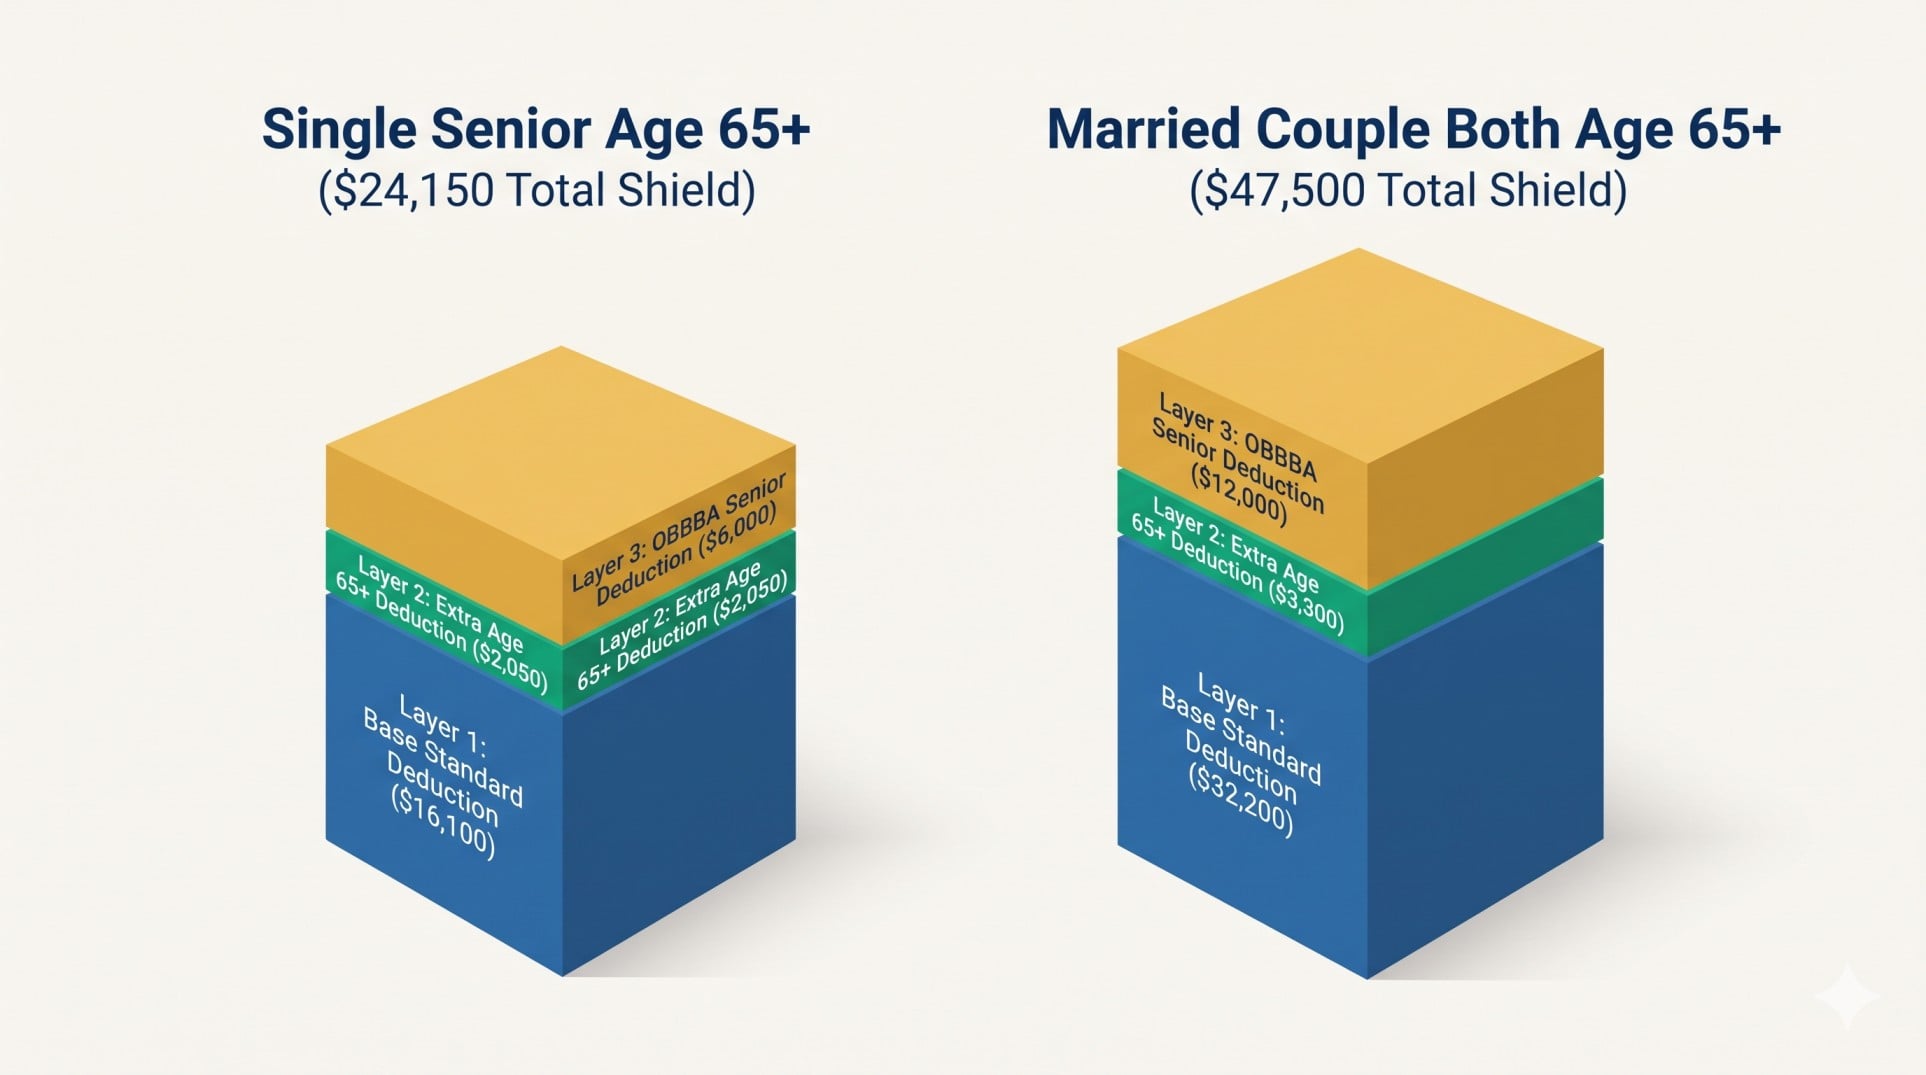
- Maximum 2026 “Triple-Stack” Shield: Combining the base standard deduction, the age-65 add-on, and the Schedule 1-A senior deduction shelters up to $24,150 for a single senior, $32,200 for a head-of-household senior, and $47,500 for a married couple where both spouses are 65+ (before adding blindness adjustments).
- 6% MAGI Phase-Out & January 1 Birthday Rule: You qualify as age 65 for 2026 if you were born on or before January 1, 1962. While the $2,050 / $1,650 extra standard deduction has no income limit, the $6,000 bonus deduction phases out at 6% of Modified Adjusted Gross Income (MAGI) above $75,000 (single) or $150,000 (joint).
Calculating the 2026 standard deduction for seniors over 65 requires combining three distinct statutory provisions on your federal return. Following IRS Revenue Procedure 2025-32 and the One Big Beautiful Bill Act (OBBBA, P.L. 119-21), older Americans no longer rely solely on the traditional age-based add-on under Internal Revenue Code (IRC) Section 63(f). Eligible retirees and working older adults can now stack their base standard deduction, their extra age-65 or blindness standard deduction, and the temporary $6,000 enhanced senior deduction on Schedule 1-A.
Missing one of these three layers—or entering the numbers on the wrong line of Form 1040 or Form 1040-SR—can cost a retired household thousands of dollars in avoidable federal tax. When evaluating the 2026 standard deduction over 65 alongside the senior deduction for 2026, every dollar figure below is verified directly against official IRS inflation adjustments and Treasury guidance for the 2026 tax year (returns filed in 2027).
Table of Contents
- What Is the 2026 Standard Deduction for Seniors Over 65? (Complete IRS Chart)
- How the 2026 Standard Deduction for Seniors Over 65 Stacks With the $6,000 Bonus
- Who Qualifies for the Extra Standard Deduction for People Age 65 and Older?
- The $6,000 Senior Tax Deduction for 2026: Schedule 1-A Rules & 6% MAGI Phase-Out
- 2025 vs. 2026 Senior Standard Deduction Comparison Table
- How 2026 Tax Deductions for Seniors Affect Social Security Taxes & Roth Conversions
- 4 Real-World Hypothetical Scenarios With Step-by-Step 2026 Tax Math
- Step-by-Step Guide: How to Claim All Senior Deductions on Form 1040-SR & Schedule 1-A
- Other 2026 Tax Breaks for Older Adults: $2,000 Charitable Rule, QCDs, Medical & SALT
- Federal vs. State Rules: Which States Conform to the 2026 Senior Deductions?
- Frequently Asked Questions About 2026 Senior Tax Deductions
What Is the 2026 Standard Deduction for Seniors Over 65? (Complete IRS Chart)
For tax year 2026, the base standard deduction plus the IRC Section 63(f) age-65 add-on equals $18,150 for single filers, $26,200 for heads of household, $33,850 for married couples filing jointly with one spouse age 65+, and $35,500 when both spouses are age 65+. Adding the $6,000 per-person Schedule 1-A deduction raises the total shield to $24,150 (single) and $47,500 (joint).
Pursuant to IRS Revenue Procedure 2025-32 (Section 4.14), the base standard deduction under IRC Section 63(c)(2) rose to $16,100 for Single and Married Filing Separately filers, $24,150 for Head of Household filers, and $32,200 for Married Filing Jointly and Qualifying Surviving Spouse filers. On top of those base figures, the 2026 standard deduction over 65 adds $2,050 for unmarried taxpayers (Single or Head of Household) and $1,650 per qualifying person for married taxpayers or surviving spouses.
Use this master standard deduction 2026 over 65 lookup table to see your exact Line 12 standard deduction alongside your combined total when including the Schedule 1-A bonus deduction:
| 2026 Filing Status & Age / Blindness Profile | 2026 Base Standard Deduction (IRC §63(c)(2)) | 2026 Extra Age 65+ / Blind Add-On (IRC §63(f)) | Total 2026 Standard Deduction (Line 12) | Max 2026 Schedule 1-A Senior Bonus (Line 13b)* | Combined 2026 Total Deduction Shield* |
|---|---|---|---|---|---|
| Single (Age 65+, Not Blind) | $16,100 | +$2,050 | $18,150 | +$6,000 | $24,150 |
| Single (Age 65+ AND Legally Blind) | $16,100 | +$4,100 ($2,050 × 2) | $20,200 | +$6,000 | $26,200 |
| Head of Household (Age 65+, Not Blind) | $24,150 | +$2,050 | $26,200 | +$6,000 | $32,200 |
| Head of Household (Age 65+ AND Legally Blind) | $24,150 | +$4,100 ($2,050 × 2) | $28,250 | +$6,000 | $34,250 |
| Married Filing Jointly (One Spouse 65+, Neither Blind) | $32,200 | +$1,650 | $33,850 | +$6,000 | $39,850 |
| Married Filing Jointly (Both Spouses 65+, Neither Blind) | $32,200 | +$3,300 ($1,650 × 2) | $35,500 | +$12,000 ($6,000 × 2) | $47,500 |
| Married Filing Jointly (Both 65+ AND One Spouse Blind) | $32,200 | +$4,950 ($1,650 × 3) | $37,150 | +$12,000 ($6,000 × 2) | $49,150 |
| Married Filing Jointly (Both 65+ AND Both Spouses Blind) | $32,200 | +$6,600 ($1,650 × 4) | $38,800 | +$12,000 ($6,000 × 2) | $50,800 |
| Qualifying Surviving Spouse (Age 65+, Not Blind) | $32,200 | +$1,650 | $33,850 | +$6,000 | $39,850 |
| Qualifying Surviving Spouse (Age 65+ AND Blind) | $32,200 | +$3,300 ($1,650 × 2) | $35,500 | +$6,000 | $41,500 |
| Married Filing Separately (Age 65+, Not Blind)** | $16,100 | +$1,650 | $17,750 | $0 (Ineligible) | $17,750 |
| Married Filing Separately (Age 65+ AND Blind)** | $16,100 | +$3,300 ($1,650 × 2) | $19,400 | $0 (Ineligible) | $19,400 |
*Note: The $6,000 per-person Schedule 1-A senior deduction reflects the maximum amount for filers with MAGI at or below $75,000 (Single/HOH/QSS) or $150,000 (Married Filing Jointly). **If your spouse itemizes deductions on a separate return, your standard deduction on a Married Filing Separately return is $0 under IRC Section 63(c)(6)(A).
How the 2026 Standard Deduction for Seniors Over 65 Stacks With the $6,000 Bonus
The 2026 standard deduction for seniors over 65 works as a three-layer stack because the One Big Beautiful Bill Act (P.L. 119-21) did not repeal or replace the historical age-65 standard deduction add-on. Instead, Congress layered the new $6,000 personal exemption-style deduction directly on top of both the base and age-adjusted standard deductions.
Many retirees get tripped up when comparing the traditional standard deduction for seniors 2026 rules against the new OBBBA rules because both require turning 65 by the end of the year, yet they live in completely different sections of the Internal Revenue Code and follow different qualification rules:
- Layer 1: The Permanently Boosted Base Standard Deduction (IRC Section 63(c)(2)). Section 70102 of the OBBBA permanently extended the higher Tax Cuts and Jobs Act (TCJA) standard deduction structure and added an extra inflation-indexed boost starting in 2025. For 2026, IRS Revenue Procedure 2025-32 sets this baseline at $16,100 (Single/MFS), $24,150 (Head of Household), and $32,200 (Married Filing Jointly / Qualifying Surviving Spouse).
- Layer 2: The Traditional Additional Standard Deduction for Age 65+ or Blindness (IRC Section 63(f)). Enacted in the Tax Reform Act of 1986, this provision adds $2,050 (unmarried) or $1,650 (married/surviving spouse) per box checked for age 65+ or legal blindness in 2026. It has zero income cap or phase-out, does not require a work-eligible Social Security number (ITIN holders qualify), and is available only if you take the standard deduction rather than itemizing on Schedule A.
- Layer 3: The $6,000 OBBBA Enhanced Senior Deduction (IRC Section 151(d)(5)(C)). Created by Section 70103 of the OBBBA for tax years 2025 through 2028, this senior tax deduction for 2026 provides up to $6,000 per qualifying individual age 65+ ($12,000 if both spouses on a joint return are 65+). Unlike Layer 2, you can claim Layer 3 even if you itemize deductions on Schedule A, but it phases out above $75,000 MAGI (single) or $150,000 MAGI (joint), requires a valid Social Security number, and is completely barred for Married Filing Separately returns.
| Rule / Feature | Layer 2: Extra Age 65+ Standard Deduction (IRC §63(f)) | Layer 3: $6,000 OBBBA Senior Deduction (IRC §151(d)(5)(C)) |
|---|---|---|
| 2026 Dollar Amount | $2,050 (Single/HOH) or $1,650 per spouse (MFJ/MFS/QSS) | Up to $6,000 per person age 65+ (up to $12,000 MFJ if both 65+) |
| Where It Is Claimed on 2026 Return | Folded directly into Form 1040 / 1040-SR, Line 12 | Calculated on Schedule 1-A; flows to Form 1040 / 1040-SR, Line 13b |
| Available If You Itemize on Schedule A? | No (only for standard deduction filers) | Yes (available to both standard deduction filers and itemizers) |
| Income Limits / MAGI Phase-Out? | None (available at any income level) | Phases out at 6% of MAGI over $75,000 (Single/HOH/QSS) or $150,000 (MFJ) |
| Extra Amount for Legal Blindness? | Yes (doubles the add-on to $4,100 Single or $3,300 per married spouse) | No (strictly tied to attaining age 65; no blindness multiplier) |
| Married Filing Separately (MFS) Allowed? | Yes (if your spouse does not itemize) | No (joint return mandatory for married couples) |
| Expiration Date Under Current Law | Permanent (indexed annually for inflation) | Temporary (applies to tax years 2025 through 2028; expires Dec. 31, 2028) |
To see how these rules fit into the broader tax code updates for all age groups, check out our 2026 federal tax brackets and standard deduction guide.
Who Qualifies for the Extra Standard Deduction for People Age 65 and Older?
Under IRS Publication 501 and IRC Section 63(f), you qualify for the extra standard deduction for people age 65 and older on your 2026 tax return if you were born on or before January 1, 1962, and you do not itemize deductions on Schedule A.
When reviewing the 2026 IRS standard deduction over 65 age threshold, pay close attention to four special statutory edge cases that frequently confuse taxpayers and preparers:
1. The January 1, 1962 Birthday Rule
Under long-standing federal tax law (following the common-law principle referenced in IRS Publication 501), the IRS considers you to attain age 65 on the day before your 65th birthday. Consequently, if your 65th birthday falls on January 1, 2027 (meaning you were born on January 1, 1962), the IRS treats you as having turned 65 on December 31, 2026! That entitles you to claim both the $2,050 / $1,650 additional standard deduction and the $6,000 Schedule 1-A senior deduction for the entire 2026 tax year.
2. Rules for a Spouse Who Passed Away in 2026
If your spouse was age 65 or older (born on or before January 1, 1962) and passed away during 2026, you can still check the age-65 box for your deceased spouse on your 2026 Married Filing Jointly return (provided you did not remarry before December 31, 2026). However, if a taxpayer or spouse passed away in 2026 before reaching their 65th birthday—even if they would have turned 65 later in 2026—the IRS does not allow the age-65 additional deduction for that deceased individual.
3. Legal Blindness Qualification Rules (IRC Section 63(f)(4))
You can stack the blindness add-on (an extra $2,050 for Single/HOH or $1,650 for Married/QSS) on top of the age-65 add-on if you are legally blind on the last day of 2026. Under IRC Section 63(f)(4), partial blindness qualifies only if you obtain a certified statement from an eye physician or registered optometrist confirming that as of December 31, 2026:
- You cannot see better than 20/200 in your better eye even with glasses or contact lenses, OR
- Your field of vision is 20 degrees or less (tunnel vision).
Keep this physician certification in your permanent tax records; you do not need to mail it with your return, but the IRS can request it during an examination.
4. Elderly Parents Claimed as Dependents on an Adult Child’s Return
What if an adult child claims a 72-year-old parent as a “Qualifying Relative” dependent in 2026, and the parent still has to file their own tax return due to pension, interest, or part-time income? Under IRC Section 63(c)(5) and Revenue Procedure 2025-32, a dependent’s base standard deduction in 2026 cannot exceed the greater of (a) $1,350, or (b) the dependent’s earned income plus $450 (up to the regular $16,100 single base standard deduction). However, the dependent parent still gets to add the full $2,050 age-65 additional standard deduction (and another $2,050 if blind) on top of that limited base! By contrast, under IRC Section 151(d)(5)(C), an individual claimed as a dependent on another taxpayer’s return is generally ineligible to claim the separate $6,000 Schedule 1-A personal exemption deduction on their own return.
The $6,000 Senior Tax Deduction for 2026: Schedule 1-A Rules & 6% MAGI Phase-Out
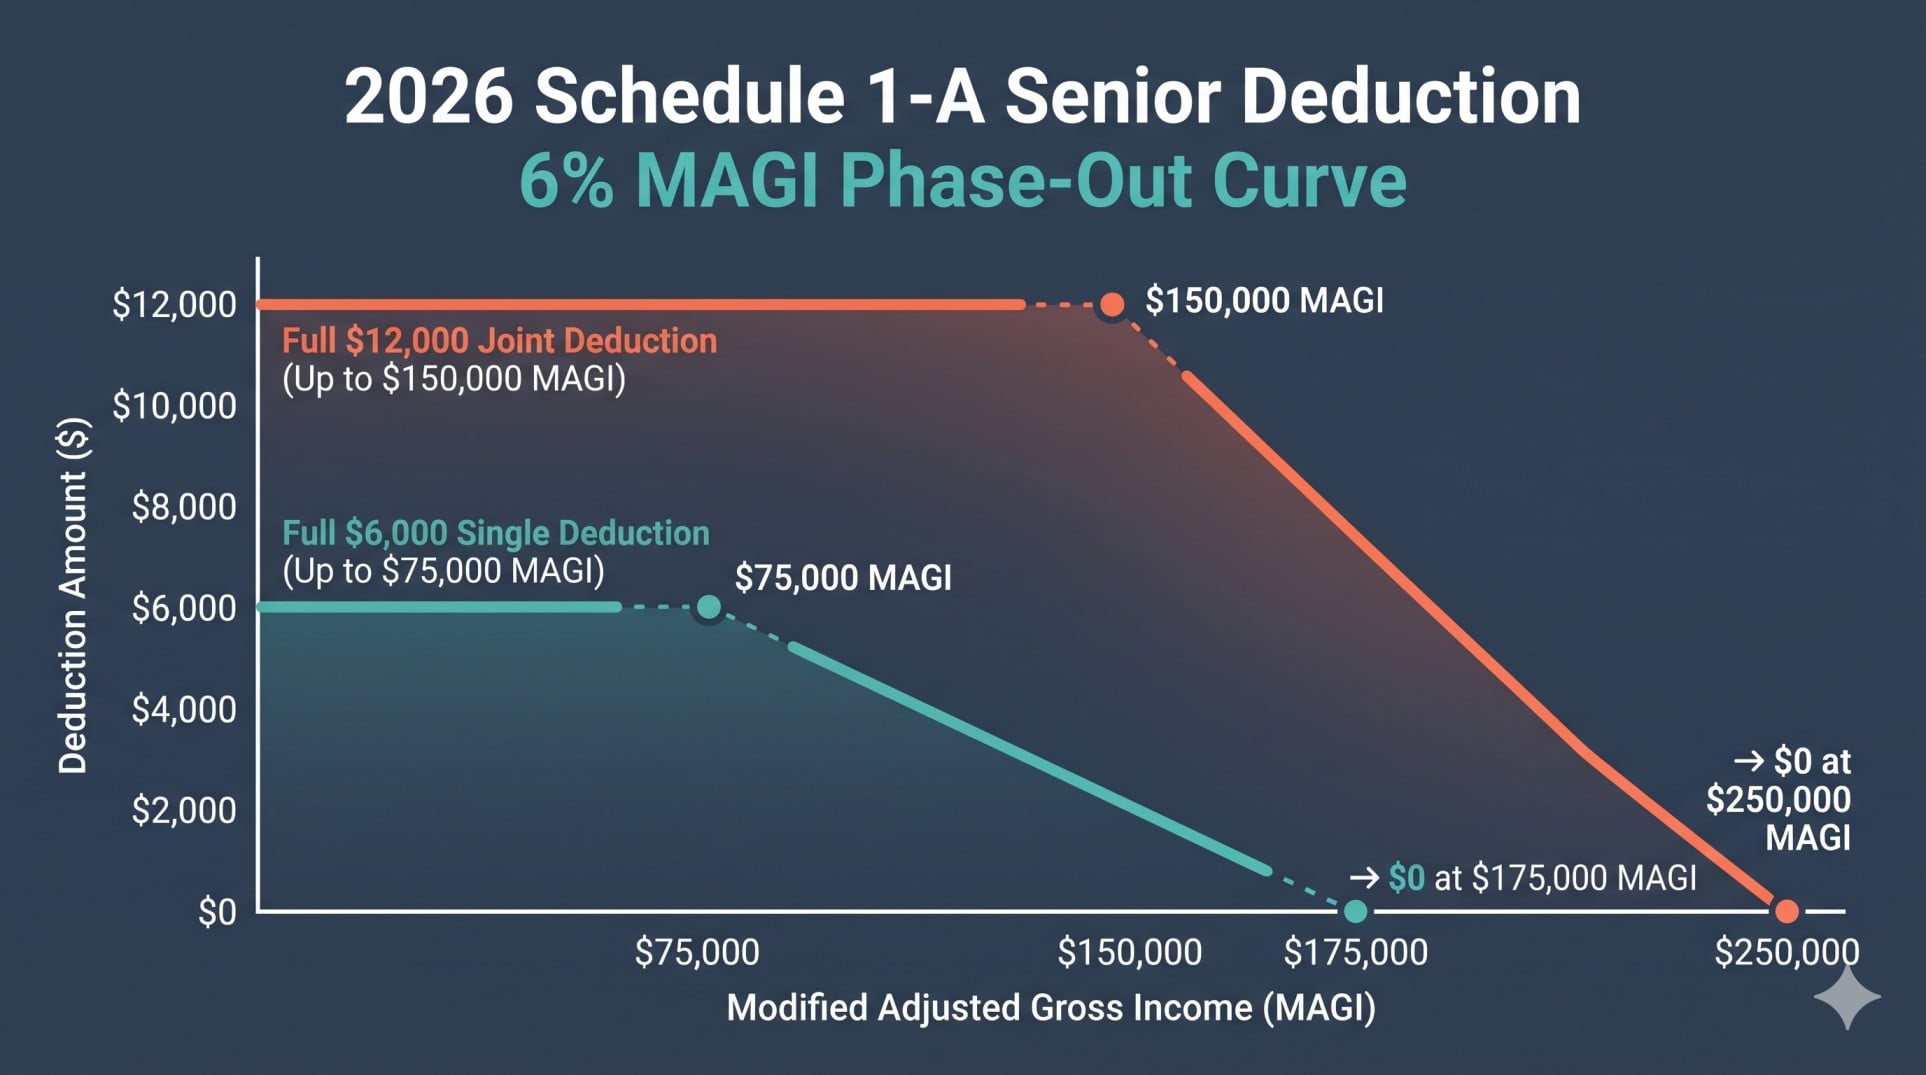
Under Section 70103 of the One Big Beautiful Bill Act (codified at IRC Section 151(d)(5)(C)), qualifying taxpayers age 65 or older can deduct up to $6,000 per person ($12,000 if both spouses on a joint return are 65+) on Schedule 1-A for 2026. The deduction phases out by 6% of Modified Adjusted Gross Income (MAGI) exceeding $75,000 (single) or $150,000 (joint).
Understanding how the 2026 senior tax deduction works requires mastering its phase-out formula and filing mechanics. Unlike the tips, overtime, and auto-loan interest deductions on Schedule 1-A—which phase out in $1,000 stepped increments—the senior deduction for 2026 phases out continuously at a flat rate of **6 cents for every $1 of MAGI** over the threshold ($60 per $1,000 of excess MAGI).
How to Calculate Your Exact 2026 Schedule 1-A Senior Deduction
- Step 1: Determine Your 2026 MAGI for Schedule 1-A. Under IRC Section 151(d)(5)(C), your MAGI is your Adjusted Gross Income from Form 1040, Line 11, increased by any foreign earned income or territory income excluded under IRC Sections 911, 931, or 933. (For 99% of domestic retirees with no foreign exclusions, your Schedule 1-A MAGI is identical to your regular AGI on Line 11!).
- Step 2: Compare Your MAGI to Your Filing Status Threshold.
- Single, Head of Household, or Qualifying Surviving Spouse: Phase-out begins at $75,000 MAGI and completes at $175,000 MAGI.
- Married Filing Jointly (One or Both Spouses 65+): Phase-out begins at $150,000 joint MAGI and completes at $250,000 joint MAGI.
- Married Filing Separately: Strictly ineligible ($0 deduction at any income level).
- Step 3: Apply the 6% Reduction Formula Per Qualifying Person.
- Single / HOH / QSS Formula: $6,000 − [0.06 × (MAGI − $75,000)].
- Married Filing Jointly (One Spouse Age 65+) Formula: $6,000 − [0.06 × (Joint MAGI − $150,000)].
- Married Filing Jointly (Both Spouses Age 65+) Formula: Each spouse’s $6,000 deduction is reduced by 6% of the excess joint MAGI over $150,000, which equals $12,000 − [0.12 × (Joint MAGI − $150,000)].
| 2026 MAGI Level (Single / HOH / QSS) | Single Senior ($6,000 Max) Allowed Deduction | 2026 Joint MAGI Level (Married Filing Jointly) | MFJ One Spouse 65+ ($6,000 Max) Allowed | MFJ Both Spouses 65+ ($12,000 Max) Allowed |
|---|---|---|---|---|
| $75,000 or less | $6,000 (100%) | $150,000 or less | $6,000 (100%) | $12,000 (100%) |
| $85,000 ($10k over) | $5,400 (-$600) | $160,000 ($10k over) | $5,400 (-$600) | $10,800 (-$1,200) |
| $100,000 ($25k over) | $4,500 (-$1,500) | $175,000 ($25k over) | $4,500 (-$1,500) | $9,000 (-$3,000) |
| $125,000 ($50k over) | $3,000 (-$3,000) | $200,000 ($50k over) | $3,000 (-$3,000) | $6,000 (-$6,000) |
| $150,000 ($75k over) | $1,500 (-$4,500) | $225,000 ($75k over) | $1,500 (-$4,500) | $3,000 (-$9,000) |
| $175,000 or more | $0 (Phased out) | $250,000 or more | $0 (Phased out) | $0 (Phased out) |
2025 vs. 2026 Senior Standard Deduction Comparison Table
Between 2025 and 2026, inflation adjustments in IRS Revenue Procedure 2025-32 increased the base standard deduction by $350 for single filers, $525 for heads of household, and $700 for married joint filers, while raising the age-65 additional standard deduction by $50 per qualifying person across all filing statuses.
While the base and age-adjusted standard deductions increased for inflation, the $6,000 Schedule 1-A senior deduction and its $75,000 / $150,000 MAGI phase-out thresholds are fixed by statute from 2025 through 2028 without inflation indexing. Compare the 2025 figures against the standard deduction 2026 for seniors over 65 below:
| Senior Taxpayer Category | 2025 Total Standard Deduction (Line 12) | 2026 Total Standard Deduction (Line 12) | 2025 Max Combined Shield (With $6k/$12k Bonus) | 2026 Max Combined Shield (With $6k/$12k Bonus) | Year-Over-Year Increase (2025 to 2026) |
|---|---|---|---|---|---|
| Single (Age 65+, Not Blind) | $17,750 ($15,750 + $2,000) | $18,150 ($16,100 + $2,050) | $23,750 | $24,150 | +$400 |
| Single (Age 65+ AND Blind) | $19,750 ($15,750 + $4,000) | $20,200 ($16,100 + $4,100) | $25,750 | $26,200 | +$450 |
| Head of Household (Age 65+, Not Blind) | $25,625 ($23,625 + $2,000) | $26,200 ($24,150 + $2,050) | $31,625 | $32,200 | +$575 |
| Married Filing Jointly (One Spouse 65+) | $33,100 ($31,500 + $1,600) | $33,850 ($32,200 + $1,650) | $39,100 | $39,850 | +$750 |
| Married Filing Jointly (Both Spouses 65+) | $34,700 ($31,500 + $3,200) | $35,500 ($32,200 + $3,300) | $46,700 | $47,500 | +$800 |
| Married Filing Jointly (Both 65+ & Both Blind) | $37,900 ($31,500 + $6,400) | $38,800 ($32,200 + $6,600) | $49,900 | $50,800 | +$900 |
How 2026 Tax Deductions for Seniors Affect Social Security Taxes & Roth Conversions
Neither the standard deduction nor the $6,000 Schedule 1-A senior deduction alters the IRC Section 86 formula that determines how much of your Social Security benefit enters Adjusted Gross Income on Line 6b. Instead, both deductions subtract from your AGI after Line 11, wiping out or reducing the final federal tax owed on Line 15.
During the legislative debate over the One Big Beautiful Bill Act, headlines frequently claimed the bill “repealed taxes on Social Security.” In reality, because the reconciliation bill was passed under Senate Byrd Rule constraints, Congress could not directly amend the Social Security Act or IRC Section 86. Thus, the three statutory **Provisional Income (Combined Income)** tiers under IRC Section 86—which equals your non-Social Security AGI + tax-exempt municipal bond interest + **50% of your gross Social Security benefits**—remain unchanged for 2026:
- Single, Head of Household, or Qualifying Surviving Spouse: Up to 50% of Social Security benefits are taxable if Provisional Income is between $25,000 and $34,000, and up to 85% of benefits are taxable once Provisional Income exceeds $34,000.
- Married Filing Jointly: Up to 50% of Social Security benefits are taxable if Provisional Income is between $32,000 and $44,000, and up to 85% of benefits are taxable once Provisional Income exceeds $44,000.
Because both the 2026 standard deduction for seniors (Line 12) and the senior deduction for 2026 on Schedule 1-A (Line 13b) are subtracted *after* AGI is calculated on Line 11, they do **not** lower your Line 11 AGI or your Provisional Income. Yet they accomplish the same bottom-line goal for middle-income retirees: if a married couple (both age 65+) has **$36,000** in pension/IRA withdrawals and **$40,000** in Social Security benefits, their Provisional Income of $56,000 makes **$16,200** of their Social Security taxable on Line 6b, producing an AGI of **$52,200** on Line 11. Then their **$35,500** Line 12 standard deduction and **$12,000** Line 13b senior deduction (**$47,500** combined) slash their taxable income down to just **$4,700**—taxed at 10% for a total tax bill of **$470** instead of thousands!
The 2026 Roth Conversion “Phase-Out Spike” Warning: If you are planning Roth conversions or extra IRA withdrawals in 2026, watch the $75,000 to $175,000 (Single) and $150,000 to $250,000 (Married Filing Jointly) MAGI phase-out zone carefully.
Inside that window, every extra $1,000 of IRA withdrawal or Roth conversion increases your AGI by $1,000 AND destroys $60 of your Schedule 1-A deduction (or $120 on a joint return where both spouses are 65+!). For a married couple in the 22% federal bracket (which spans $100,801 to $211,400 of taxable income in 2026), losing $120 of deduction per $1,000 converted raises their effective marginal tax rate from 22.0% to 24.64% ($1,120 × 22% = $246.40 tax per $1,000 converted).
To plan your retirement withdrawals around these brackets and Medicare surcharges, review our guide to minimizing taxes on Social Security benefits and RMDs.
4 Real-World Hypothetical Scenarios With Step-by-Step 2026 Tax Math
To illustrate how the standard deduction 2026 seniors over 65 chart, the Schedule 1-A phase-out, and the 2026 tax brackets interact, walk through these four real-world scenarios.
Scenario 1: The Single Retiree Who Pays $0 Federal Tax on $46,000 of Total Income
Taxpayer Profile: Evelyn, age 68 (born in 1958, not blind), is a single retiree in Florida. In 2026, she receives $28,000 in gross Social Security benefits (Form SSA-1099) and withdraws $18,000 from her Traditional IRA, giving her $46,000 in total cash flow.
- Step 1 (Social Security Provisional Income Test — IRC Section 86): Evelyn’s Provisional Income is $18,000 (IRA withdrawal) + $14,000 (50% of her $28,000 Social Security) = $32,000. Because $32,000 is between the $25,000 and $34,000 single thresholds, 50% of the excess over $25,000 ($7,000 × 50% = $3,500) of her Social Security is taxable on Form 1040-SR, Line 6b.
- Step 2 (2026 Adjusted Gross Income on Line 11): $18,000 IRA distribution + $3,500 taxable Social Security = $21,500 AGI (and MAGI).
- Step 3 (Applying the 2026 Triple-Stack Deductions):
- Base Single Standard Deduction (Line 12): $16,100.
- Extra Age-65 Standard Deduction (Line 12): +$2,050 (Total Line 12 = $18,150).
- Schedule 1-A Enhanced Senior Deduction (Line 13b): Because Evelyn’s $21,500 MAGI is well below the $75,000 threshold, she gets the full +$6,000.
- Combined 2026 Deductions (Line 14): $24,150.
- Step 4 (2026 Taxable Income & Tax Owed): $21,500 AGI minus $24,150 total deductions = $0 Taxable Income on Line 15 (and $0 federal income tax!). In fact, Evelyn still has $2,650 of unused deduction room—meaning she could convert roughly $1,766 of her Traditional IRA to a Roth IRA in 2026 (which pulls an extra $883 of Social Security into AGI) and pay $0 tax on the Roth conversion!
Scenario 2: The Married Couple (Both Age 65+) With a Partial MAGI Phase-Out
Taxpayer Profile: Robert (age 70) and Linda (age 67) file Married Filing Jointly in 2026. Neither is blind. Between Robert’s corporate pension, Linda’s part-time consulting, and their 85% taxable Social Security benefits, their 2026 Adjusted Gross Income (and MAGI) on Line 11 is $185,000.
- Step 1 (Line 12 Standard Deduction): Because the IRC Section 63(f) age add-on never phases out with income, Robert and Linda receive the full $32,200 joint base standard deduction plus $3,300 ($1,650 × 2 for both spouses being 65+) = $35,500 on Form 1040-SR, Line 12.
- Step 2 (Line 13b Schedule 1-A Senior Deduction Phase-Out Math): Their joint MAGI of $185,000 exceeds the $150,000 joint threshold by $35,000.
- Robert’s $6,000 deduction is reduced by 6% of $35,000 ($35,000 × 0.06 = $2,100), leaving $3,900.
- Linda’s $6,000 deduction is also reduced by 6% of $35,000 ($2,100), leaving $3,900.
- Combined Schedule 1-A / Line 13b Senior Deduction = $7,800 (out of the $12,000 maximum).
- Step 3 (2026 Taxable Income & Tax Savings):
- Total 2026 Deductions (Line 14): $35,500 + $7,800 = $43,300.
- 2026 Taxable Income (Line 15): $185,000 AGI minus $43,300 = $141,700 (falling squarely inside the 22% joint bracket, which starts at $100,801 in 2026).
- 2026 Tax Saved by the Senior Add-Ons Alone: Compared to a younger couple under age 65 who only receives the $32,200 base standard deduction, Robert and Linda’s extra $11,100 in senior deductions ($3,300 age add-on + $7,800 Schedule 1-A deduction) saves them $2,442 in 2026 federal income tax ($11,100 × 22%).
Scenario 3: The Mixed-Age Married Couple With a January 1, 1962 Birthday
Taxpayer Profile: David and Maria file Married Filing Jointly in 2026 with a combined MAGI of $135,000. David was born on January 1, 1962 (turning 65 on New Year’s Day 2027), while Maria is age 61 (born in June 1965) and is legally blind due to retinitis pigmentosa (with a physician certificate confirming a visual field under 20 degrees).
- Applying the January 1 Birthday Rule to David: Because David was born on January 1, 1962, the IRS deems him to have reached age 65 on December 31, 2026. He qualifies for both the $1,650 age-65 standard deduction add-on and the $6,000 Schedule 1-A senior deduction for 2026!
- Applying the Blindness Rule to Maria (Age 61): Even though Maria is under age 65, her legal blindness entitles the couple to check the blindness box for her on Form 1040-SR, adding another $1,650 to their Line 12 standard deduction. However, because Maria is not yet 65, she does not qualify for a second $6,000 Schedule 1-A senior deduction.
- Total 2026 Deduction Stack:
- Base Joint Standard Deduction: $32,200.
- David’s Age-65 Add-On (Line 12): +$1,650.
- Maria’s Blindness Add-On (Line 12): +$1,650 (Total Line 12 Standard Deduction = $35,500).
- David’s Schedule 1-A Senior Deduction (Line 13b, since $135,000 MAGI is under $150,000): +$6,000.
- Combined 2026 Deduction Total: $41,500, reducing their taxable income from $135,000 down to $93,500 (dropping them completely out of the 22% bracket into the 12% joint bracket, which ends at $100,800 in 2026!).
Scenario 4: The High-Property-Tax Senior Who Itemizes on Schedule A AND Claims the $6,000 Bonus
Taxpayer Profile: Arthur, age 71, is a single homeowner in New Jersey with a 2026 MAGI of $115,000. In 2026, he pays $16,500 in local property taxes and state income taxes (fully deductible under the expanded OBBBA SALT cap), $6,500 in mortgage interest, and $4,000 in charitable contributions, totaling $27,000 in Schedule A itemized deductions.
- Standard vs. Itemized Comparison (Line 12): If Arthur took the standard deduction, his Line 12 amount would be $18,150 ($16,100 base + $2,050 age-65 add-on). Because his $27,000 of itemized deductions on Schedule A beats $18,150 by $8,850, Arthur chooses to itemize on Line 12 (forfeiting the $18,150 standard deduction).
- Stacking the Schedule 1-A Senior Tax Deduction for 2026 on Top of Schedule A: Because IRC Section 151(d)(5)(C) allows itemizers to claim the $6,000 senior deduction on Line 13b, Arthur still calculates his Schedule 1-A benefit! At $115,000 MAGI ($40,000 above the $75,000 single phase-out floor), his $6,000 deduction is reduced by $40,000 × 6% = $2,400, giving him a $3,600 Schedule 1-A senior deduction on Line 13b.
- Total 2026 Write-Off (Line 14): $27,000 (Schedule A itemized deductions on Line 12) + $3,600 (Schedule 1-A senior deduction on Line 13b) = $30,600 total deductions!
Step-by-Step Guide: How to Claim All Senior Deductions on Form 1040-SR & Schedule 1-A
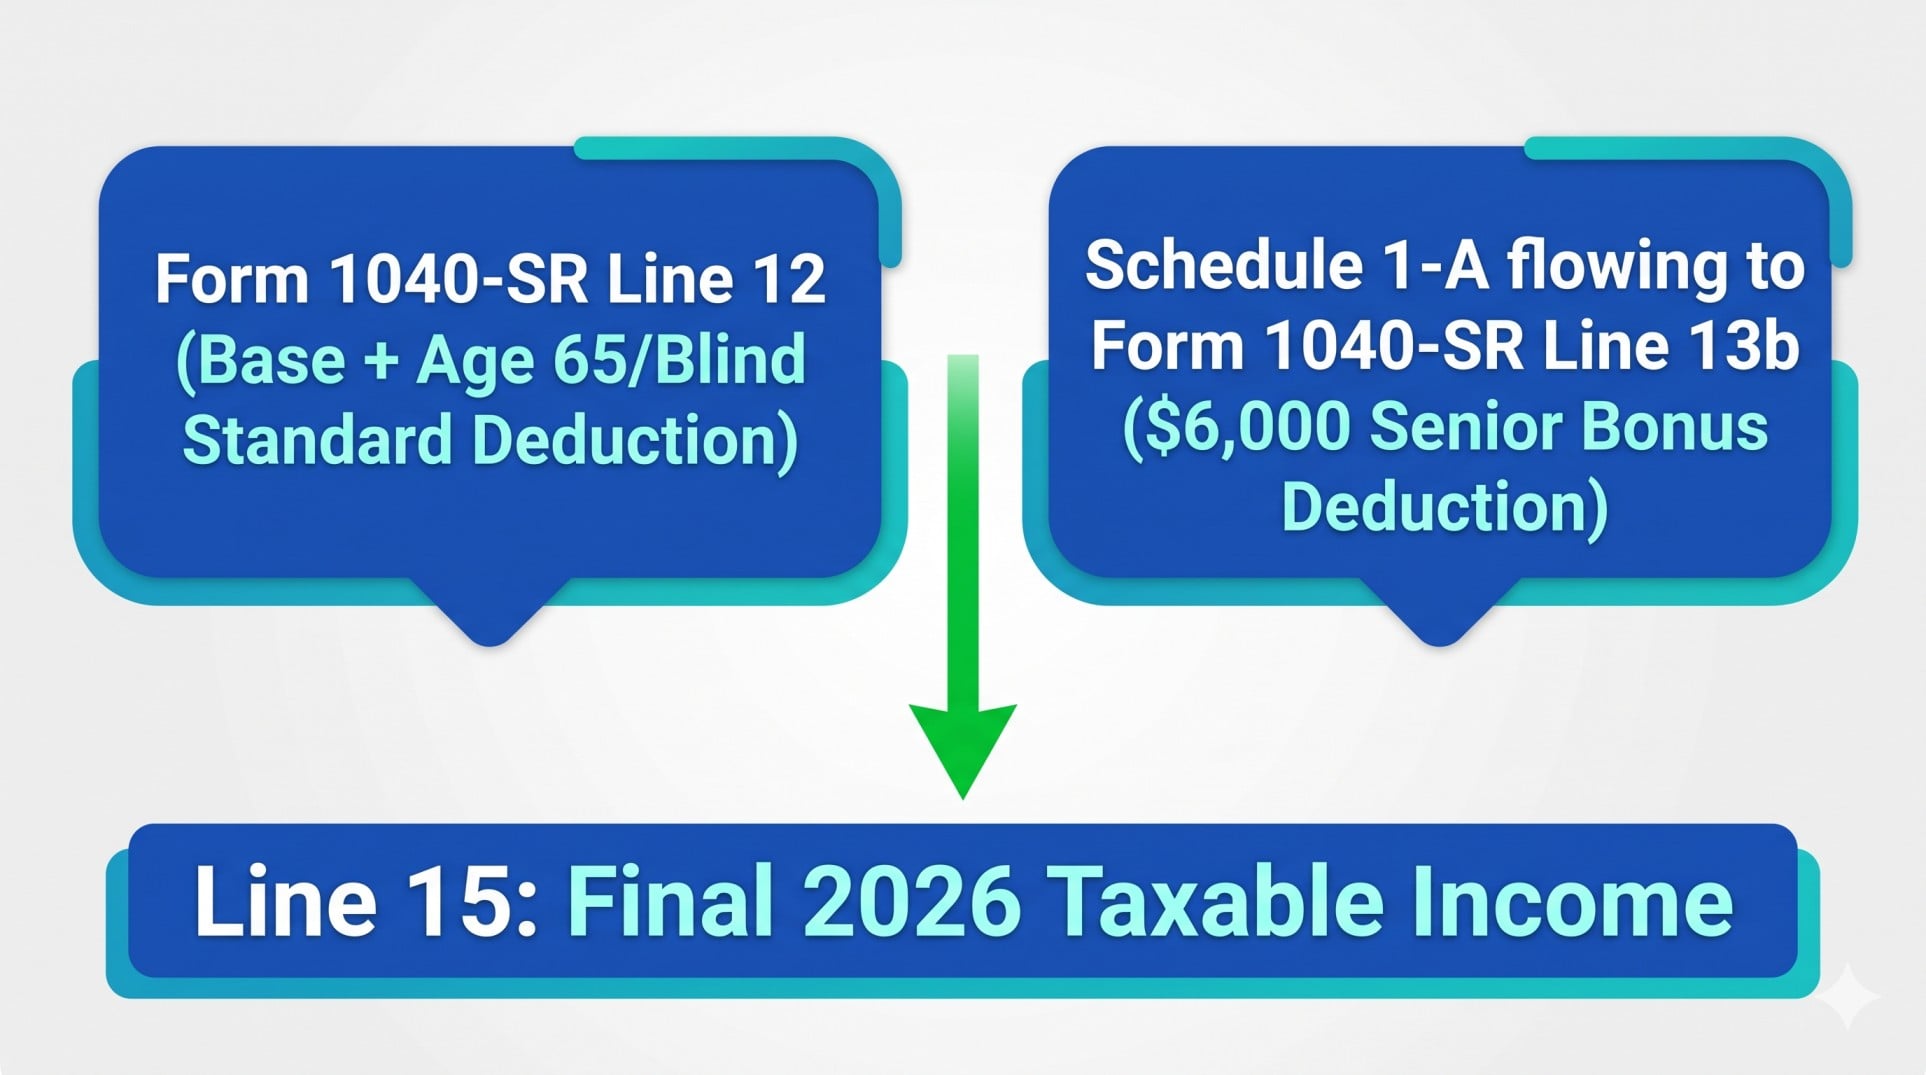
To capture the full 2026 standard deduction for seniors over 65 and the $6,000 bonus deduction, you must check the age/blindness boxes on page 1 of Form 1040 or Form 1040-SR, enter your enhanced standard deduction on Line 12, and attach Schedule 1-A so your bonus deduction flows to Line 13b.
Follow this exact 6-step checklist so you don’t fall into the “Schedule 1-A Snare” where software or paper filers accidentally omit the $6,000 deduction:
- Step 1: Choose Between Form 1040 and Form 1040-SR. Any taxpayer born on or before January 1, 1962, can use Form 1040-SR (U.S. Income Tax Return for Seniors). Form 1040-SR uses identical line numbers, schedules, and tax tables as the standard Form 1040, but provides larger font, higher contrast (no shaded boxes), and a built-in 2026-65 Standard Deduction Chart printed directly on page 4.
- Step 2: Check the Age and Blindness Boxes Under the “Standard Deduction” Section on Page 1. Locate the checkboxes directly above Line 1 showing: “You: Were born before January 2, 1962 / Are blind” and “Spouse: Was born before January 2, 1962 / Is blind.” Count the total number of boxes checked (from 1 to 4). If you leave these boxes blank, IRS processing computers will default your Line 12 standard deduction to the lower under-65 base amount!
- Step 3: Enter Your Enhanced Standard Deduction on Line 12 (or Schedule A Total if Itemizing). Using the page 4 Standard Deduction Chart on Form 1040-SR (our standard deduction for 2026 seniors over 65 table above), enter your combined base + age/blindness standard deduction on Line 12 (for example, $18,150 for a single senior or $35,500 for a married couple where both are 65+).
- Step 4: Complete Schedule 1-A (Additional Deductions) for the $6,000 / $12,000 Senior Bonus. Do not add the $6,000 senior deduction into Line 12! Instead, open Schedule 1-A (Form 1040):
- Verify that each qualifying senior has a valid Social Security Number entered on page 1 of Form 1040/1040-SR and that your filing status is not Married Filing Separately.
- In Part I of Schedule 1-A, compute your Modified Adjusted Gross Income (Line 11 AGI plus any IRC Section 911/931/933 foreign or territory exclusions).
- In the Senior Deduction section of Schedule 1-A, enter $6,000 (one qualifying senior) or $12,000 (two qualifying seniors on a joint return) and subtract the 6% phase-out reduction if your MAGI exceeds $75,000 (Single/HOH/QSS) or $150,000 (Married Filing Jointly).
- Step 5: Carry Your Schedule 1-A Total to Form 1040 / 1040-SR, Line 13b. Add your allowed senior deduction to any qualifying tip, overtime, or auto-loan interest deductions on Schedule 1-A and transfer the total to Line 13b of Form 1040 or Form 1040-SR (right beside Line 13a, which holds the 20% Qualified Business Income deduction).
- Step 6: Sum Lines 12, 13a, and 13b on Line 14 and Subtract From Line 11 AGI. Combine your Line 12 standard (or itemized) deduction and your Line 13b Schedule 1-A deduction on Line 14, then subtract Line 14 from Line 11 to arrive at your final 2026 Taxable Income on Line 15.
Other 2026 Tax Breaks for Older Adults: $2,000 Charitable Rule, QCDs, Medical & SALT
Beyond the 2026 federal standard deduction over 65 and Schedule 1-A, older taxpayers in 2026 can take advantage of the newly restored $1,000 / $2,000 non-itemizer charitable deduction, tax-free Qualified Charitable Distributions (QCDs) from IRAs starting at age 70½, and the 7.5% AGI medical expense floor.
When reviewing all available 2026 tax deductions for seniors, coordinate these five high-value provisions with your CPA:
- 1. The New 2026 Non-Itemizer Charitable Deduction ($1,000 Single / $2,000 Married Filing Jointly): Starting in tax year 2026 under the OBBBA amendments to IRC Section 170, taxpayers who take the standard deduction (and do not itemize on Schedule A) can deduct up to $1,000 (Single) or $2,000 (Married Filing Jointly) of cash contributions made directly to qualified 501(c)(3) public charities (excluding donor-advised funds and supporting organizations). That means a married couple (both 65+) taking the standard deduction in 2026 who donates $2,000 to their church or local food bank can shield up to $49,500 ($35,500 standard deduction + $12,000 Schedule 1-A senior deduction + $2,000 charitable deduction)!
- 2. Qualified Charitable Distributions (QCDs) for Seniors Age 70½+ (IRC Section 408(d)(8)): Once you reach actual age 70½, you can transfer up to the inflation-adjusted annual QCD limit (over $111,000 per person) directly from your Traditional IRA custodian to a qualified charity. A QCD counts toward your annual Required Minimum Distribution (RMD, which begins at age 73 under SECURE 2.0) and is **excluded from gross income and AGI completely**. For seniors with MAGI between $75,000 and $175,000 (single) or $150,000 and $250,000 (joint), using a QCD instead of taking an RMD and donating cash prevents the 6% MAGI phase-out of your $6,000 Schedule 1-A senior deduction and helps avoid Medicare Part B and Part D IRMAA surcharges!
- 3. Deducting Medical, Dental, and Long-Term Care Expenses Above 7.5% of AGI (IRC Section 213): If you face major out-of-pocket medical bills, assisted-living costs, Medicare Part B/D and Medigap premiums, or age-based qualified long-term care insurance premiums in 2026, you can deduct the portion exceeding 7.5% of your AGI on Schedule A—and still claim the **$6,000 / $12,000** Schedule 1-A senior deduction on Line 13b!
- 4. Credit for the Elderly or the Disabled (Schedule R / IRC Section 22): Low-income seniors age 65+ (or retired under age 65 on permanent and total disability) with very low AGI (under $17,500 single or $25,000 joint where both qualify) and nontaxable Social Security/pension income under $5,000 ($7,500 joint) can claim a nonrefundable tax credit between **$3,750 and $7,500** on **Schedule R**.
- 5. Higher Catch-Up Contributions for Working Seniors Ages 60–63 and 65+: If you or your spouse still earn W-2 wages or self-employment income in 2026, you can lower your MAGI (preserving more of your $6,000 Schedule 1-A senior deduction!) by making pre-tax contributions to a 401(k), 403(b), or 457(b) plan (base limit of $24,500 in 2026 plus the standard age 50+ catch-up, or the enhanced $11,250 catch-up for workers ages 60 to 63). Note that beginning in 2026 under SECURE 2.0 (IRC Section 414(v)(7)), if your prior-year FICA wages from that employer exceeded the inflation-adjusted threshold ($150,000), your 401(k) catch-up contributions must go into a designated Roth account rather than pre-tax. For a full breakdown of retirement savings caps, see our 2026 401(k) and IRA contribution limits guide.
Federal vs. State Rules: Which States Conform to the 2026 Senior Deductions?
Claiming the IRS standard deduction 2026 over 65 and the $6,000 Schedule 1-A bonus on your federal Form 1040-SR does not guarantee the same deduction on your state income tax return. Because the $6,000 OBBBA senior deduction sits below Line 11 AGI on Line 13b, states that start their tax calculation with federal AGI do not automatically include it unless state law specifically conforms to IRC Section 151(d)(5)(C) or starts with federal Taxable Income (Line 15).
Always separate your federal deduction from your state return rules:
- 9 States With Zero Personal Wage/Retirement Income Tax: Residents of **Alaska, Florida, Nevada, New Hampshire** (interest and dividends tax repealed effective 2025 onward), **South Dakota, Tennessee, Texas, Washington** (capital gains excise tax only on high-tier sales), and **Wyoming** pay no state income tax on pensions, IRA withdrawals, or Social Security.
- States That Exempt Retirement Income (Pennsylvania, Illinois, Mississippi, Iowa): States like Pennsylvania, Illinois, Mississippi, and Iowa (for residents 55+) generally exempt Social Security, 401(k)/IRA distributions, and pensions from state income tax regardless of your federal standard deduction.
- Federal Taxable Income Starting-Point States (Automatic Conformity Unless Decoupled): A small group of states—such as **Colorado, Idaho, North Dakota, and South Carolina**—begin their state income tax computation with **Federal Taxable Income (Form 1040, Line 15)** rather than Federal AGI (Line 11). Unless a state legislature enacts a specific statutory add-back, deductions taken on Line 12 and Line 13b automatically flow into the state starting figure.
- Federal AGI Starting-Point & Fixed-Conformity States (California, New York, New Jersey, Massachusetts): Most income-tax states start with **Federal AGI (Form 1040, Line 11)** and apply their own state-specific standard deductions and senior exemptions. For example, California (FTB Form 540) uses its own state standard deduction and provides a state Senior Exemption Credit rather than conforming to the federal Line 12 standard deduction or the federal Line 13b $6,000 Schedule 1-A senior deduction.
Frequently Asked Questions About 2026 Senior Tax Deductions
How much is the standard deduction 2026 for seniors over 65?
For the 2026 tax year, the base plus age-65 standard deduction on Line 12 is $18,150 for single filers ($16,100 + $2,050), $26,200 for heads of household ($24,150 + $2,050), $33,850 for married couples filing jointly where one spouse is 65+ ($32,200 + $1,650), and $35,500 where both spouses are 65+ ($32,200 + $3,300). Qualifying seniors can also add up to $6,000 per person on Schedule 1-A (Line 13b), bringing the maximum combined shield to $24,150 (single) or $47,500 (married both 65+).
Did the $6,000 senior deduction replace the extra standard deduction for age 65 in 2026?
No, the $6,000 senior deduction enacted under the One Big Beautiful Bill Act (IRC Section 151(d)(5)(C)) did not replace the traditional extra standard deduction under IRC Section 63(f). Both deductions are in full force for 2026 and stack directly on top of each other: a single senior with MAGI under $75,000 gets both the $2,050 age-65 standard deduction add-on (Line 12) and the $6,000 bonus deduction (Schedule 1-A / Line 13b) for $8,050 in extra age-based write-offs.
Can I claim the $6,000 senior deduction for 2026 if I itemize my deductions on Schedule A?
Yes! Unlike the $2,050 / $1,650 extra standard deduction—which is only available to taxpayers who take the standard deduction—the $6,000 OBBBA senior deduction is claimed on Schedule 1-A and entered on Form 1040, Line 13b, regardless of whether you take the standard deduction or itemize deductions on Schedule A.
What is the exact birthday cutoff to qualify as age 65 for the 2026 tax year?
You must be born on or before January 1, 1962, to qualify as age 65 or older for the 2026 tax year. Because IRS rules state that you attain age 65 on the day before your 65th birthday, someone born on January 1, 1962, is legally treated as turning 65 on December 31, 2026, qualifying for the full 2026 senior deductions.
Do I have to be retired or collecting Social Security to claim the 2026 senior deductions?
No, neither the $2,050 / $1,650 extra standard deduction nor the $6,000 Schedule 1-A senior deduction requires you to be retired or receiving Social Security benefits. A 66-year-old who works full-time earning W-2 wages and delays Social Security until age 70 still qualifies for both deductions (subject to the $75,000 single / $150,000 joint MAGI phase-out on the $6,000 bonus deduction).
What happens if my spouse and I are both over 65 but file Married Filing Separately in 2026?
Filing as Married Filing Separately (MFS) carries a severe penalty in 2026: under IRC Section 151(d)(5)(C), MFS filers are 100% disqualified from claiming the $6,000 per-person ($12,000 combined) Schedule 1-A senior deduction, regardless of how low their income is. You can still claim the $16,100 base plus $1,650 age-65 standard deduction ($17,750) on an MFS return, provided your spouse does not itemize deductions.
How does the standard deduction 2026 for seniors work if I am both over 65 and legally blind?
Under IRC Section 63(f), the additional standard deduction applies separately to age 65+ and legal blindness, allowing you to double the Line 12 add-on. In 2026, a single filer who is both 65+ and legally blind adds $4,100 ($2,050 × 2) to the $16,100 base for a $20,200 Line 12 standard deduction (plus up to $6,000 on Schedule 1-A for $26,200 total). Note that the $6,000 Schedule 1-A deduction does not double for blindness.
Does the $6,000 senior deduction lower my Medicare IRMAA brackets for 2028?
No, the $6,000 Schedule 1-A senior deduction does not reduce your Medicare Income-Related Monthly Adjustment Amount (IRMAA). Medicare Part B and Part D IRMAA surcharges (which use a 2-year lookback, meaning your 2026 return determines your 2028 Medicare premiums) are based on your Form 1040, Line 11 AGI plus tax-exempt interest. Because Line 13b is subtracted after Line 11 AGI, it does not lower your IRMAA MAGI—whereas a Qualified Charitable Distribution (QCD) from an IRA does lower Line 11 AGI.
When does the $6,000 Schedule 1-A senior deduction expire?
Under Section 70103 of the One Big Beautiful Bill Act (P.L. 119-21), the $6,000 per-person enhanced senior deduction is temporary and applies to four tax years: 2025, 2026, 2027, and 2028. Unless Congress passes new legislation extending it, the $6,000 bonus deduction will sunset after December 31, 2028, while the base standard deduction and the IRC Section 63(f) extra standard deduction ($2,050 / $1,650, indexed for inflation) remain permanent.
Maximizing Your 2026 Retirement Tax Shield
Taking full advantage of the 2026 standard deduction for seniors over 65 alongside the senior tax deduction for 2026 gives older Americans a four-year window (through 2028) to shelter up to $24,150 (Single) or $47,500 (Married Filing Jointly) of retirement income before paying a single dollar of federal income tax. When combined with the newly restored $1,000 / $2,000 non-itemizer charitable deduction and tax-free Qualified Charitable Distributions from IRAs, retirees have unprecedented flexibility to manage their tax brackets in 2026.
Make sure you capture both halves of the benefit when preparing your return: check the age-65 and blindness boxes on page 1 of Form 1040-SR so you receive the full 2026 standard deduction over 65 on Line 12, and complete Schedule 1-A so your $6,000 or $12,000 bonus deduction flows onto Line 13b. If your household income approaches the $75,000 (single) or $150,000 (joint) MAGI phase-out threshold, review your year-end IRA distributions and capital gains before December 31 to keep every dollar of your 2026 deduction intact.
Disclaimer: This content provides general information for educational purposes only. Tax laws are complex and change often. It is not professional tax, legal, or financial advice. Always consult a qualified tax professional for personalized guidance regarding your specific situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.
