
Homeowners spending thousands on a new roof, kitchen remodel, or HVAC replacement naturally want to know if they can write off home improvements on their federal return. Under Internal Revenue Code (IRC) Section 262(a), personal living expenses are nondeductible—meaning you generally cannot deduct routine repairs or renovations to a strictly personal residence in the year you swipe your card. However, five major exceptions in the tax code allow individual homeowners, remote business owners, and landlords to turn renovation invoices into thousands of dollars in tax savings for Tax Year 2026 (returns filed in 2027).
Everything hinges on how the property is used, how the project is financed, and whether the work counts as a repair or a capital improvement. Following the passage of the One Big Beautiful Bill Act (OBBBA, P.L. 119-21) and IRS Revenue Procedure 2025-32, the 2026 rules look markedly different from prior years: federal residential energy credits under IRC Sections 25C and 25D expired after December 31, 2025, while the expanded $40,400 SALT cap, permanent $750,000 home equity loan interest rules, and permanent 100% bonus depreciation for rental upgrades created powerful new planning opportunities.
⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- Capital Improvements Boost Cost Basis (IRC §1016): Personal home improvements aren’t deducted on your 2026 return (filed by April 15, 2027), but they add dollar-for-dollar to your home’s adjusted cost basis—reducing taxable capital gains above the $250,000 (Single) or $500,000 (Married Filing Jointly) IRC Section 121 exclusion when you sell.
- 2026 OBBBA Energy Credit Sunset & HELOC Permanence: Under P.L. 119-21, the Section 25C ($3,200 efficiency) and Section 25D (30% solar) credits expired after December 31, 2025 (only prior-year Section 25D carryforwards apply on 2026 Form 5695). Meanwhile, deducting HELOC interest on up to $750,000 of combined debt used to substantially improve your home is now permanent on Schedule A.
- Home Office, Rental & Medical Write-Offs: Self-employed owners can deduct pro-rata repairs and depreciate improvements on Form 8829; landlords can immediately expense items up to $2,500 under the De Minimis Safe Harbor or claim 100% bonus depreciation on 5- and 15-year assets on Schedule E / Form 4562; and medically necessary modifications are deductible above 7.5% of AGI on Schedule A, Line 1.
- 2026 Standard Deduction Hurdle: Per IRS Revenue Procedure 2025-32, itemized deductions on Schedule A (such as medical upgrades and HELOC interest) only save you money if your total itemized expenses exceed the 2026 standard deduction of $16,100 (Single), $24,150 (Head of Household), or $32,200 (Married Filing Jointly).
Table of Contents
- ⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- What Are Home Improvement Tax Deductions in 2026?
- Home Repairs vs. Capital Improvements: The IRS BAR Classification Test
- 5 Scenarios Where You Can Write Off Home Improvements or Repairs in 2026
- What Recently Changed: The Energy Credit Sunset & 2025 vs. 2026 Comparison
- 4 Real-World Hypothetical Scenarios With Step-by-Step 2026 Tax Math
- Step-by-Step Guide: How to Claim and Report Home Improvements on Your 2026 Return
- Documenting Now So You’re Not Guessing Later: IRS Audit-Proof Recordkeeping
- Federal vs. State Rules: State Energy Credits, Rebates & Depreciation Conformity
- Frequently Asked Questions About Writing Off Home Improvements & Repairs
- Final 2026 Tax Planning Checklist for Homeowners and Investors
What Are Home Improvement Tax Deductions in 2026?
Home improvement tax deductions are specific federal tax provisions that let property owners recover the cost of renovations, accessibility modifications, or financing interest—either immediately on Schedule A, Schedule C, or Schedule E, or over time through depreciation and a higher adjusted cost basis when selling.
Understanding why the IRS treats two identical contractor invoices differently starts with separating personal living space from income-producing or medically required space. Under IRC Section 262(a), the cost of maintaining or upgrading your personal home is treated as a nondeductible personal expense in the year paid. You cannot subtract a $35,000 primary bathroom remodel from your W-2 salary on Form 1040 simply because you own the house.
Instead, the tax code channels residential property work into five distinct legal buckets:
- 1. Capital Gains Cost Basis Increases (IRC Section 1016 & Section 121): Permanent upgrades to your primary or secondary residence increase your property’s cost basis, shrinking your taxable profit when you sell the house years later.
- 2. Home Equity & Mortgage Renovation Interest (IRC Section 163(h)): If you borrow via a mortgage, Home Equity Line of Credit (HELOC), or home equity loan to “buy, build, or substantially improve” the home securing the loan, the interest on up to $750,000 of combined acquisition debt is deductible on Schedule A if you itemize.
- 3. Self-Employed Home Office Write-Offs (IRC Section 280A): Business owners who use part of their home exclusively and regularly as their principal place of business can deduct repairs and depreciate improvements allocable to that workspace on Form 8829 and Schedule C.
- 4. Rental Property & “House Hacking” Deductions (IRC Section 162, Section 168(k), & Section 263(a)): Landlords renting out a whole house, a duplex unit, or a spare bedroom can deduct 100% of ordinary repairs immediately on Schedule E, expense small items up to $2,500 via the De Minimis Safe Harbor, and claim permanent 100% bonus depreciation on qualifying 5- and 15-year property in 2026.
- 5. Medically Necessary Home Modifications (IRC Section 213): Upgrades prescribed to accommodate a disability or medical condition for you, your spouse, or a dependent are deductible as itemized medical expenses on Schedule A to the extent total medical costs exceed 7.5% of your Adjusted Gross Income (AGI).
Before deciding whether to itemize personal medical or mortgage interest expenses on Schedule A, compare your total against the higher 2026 standard deduction amounts of $16,100 (Single), $24,150 (Head of Household), and $32,200 (Married Filing Jointly).
Home Repairs vs. Capital Improvements: The IRS BAR Classification Test
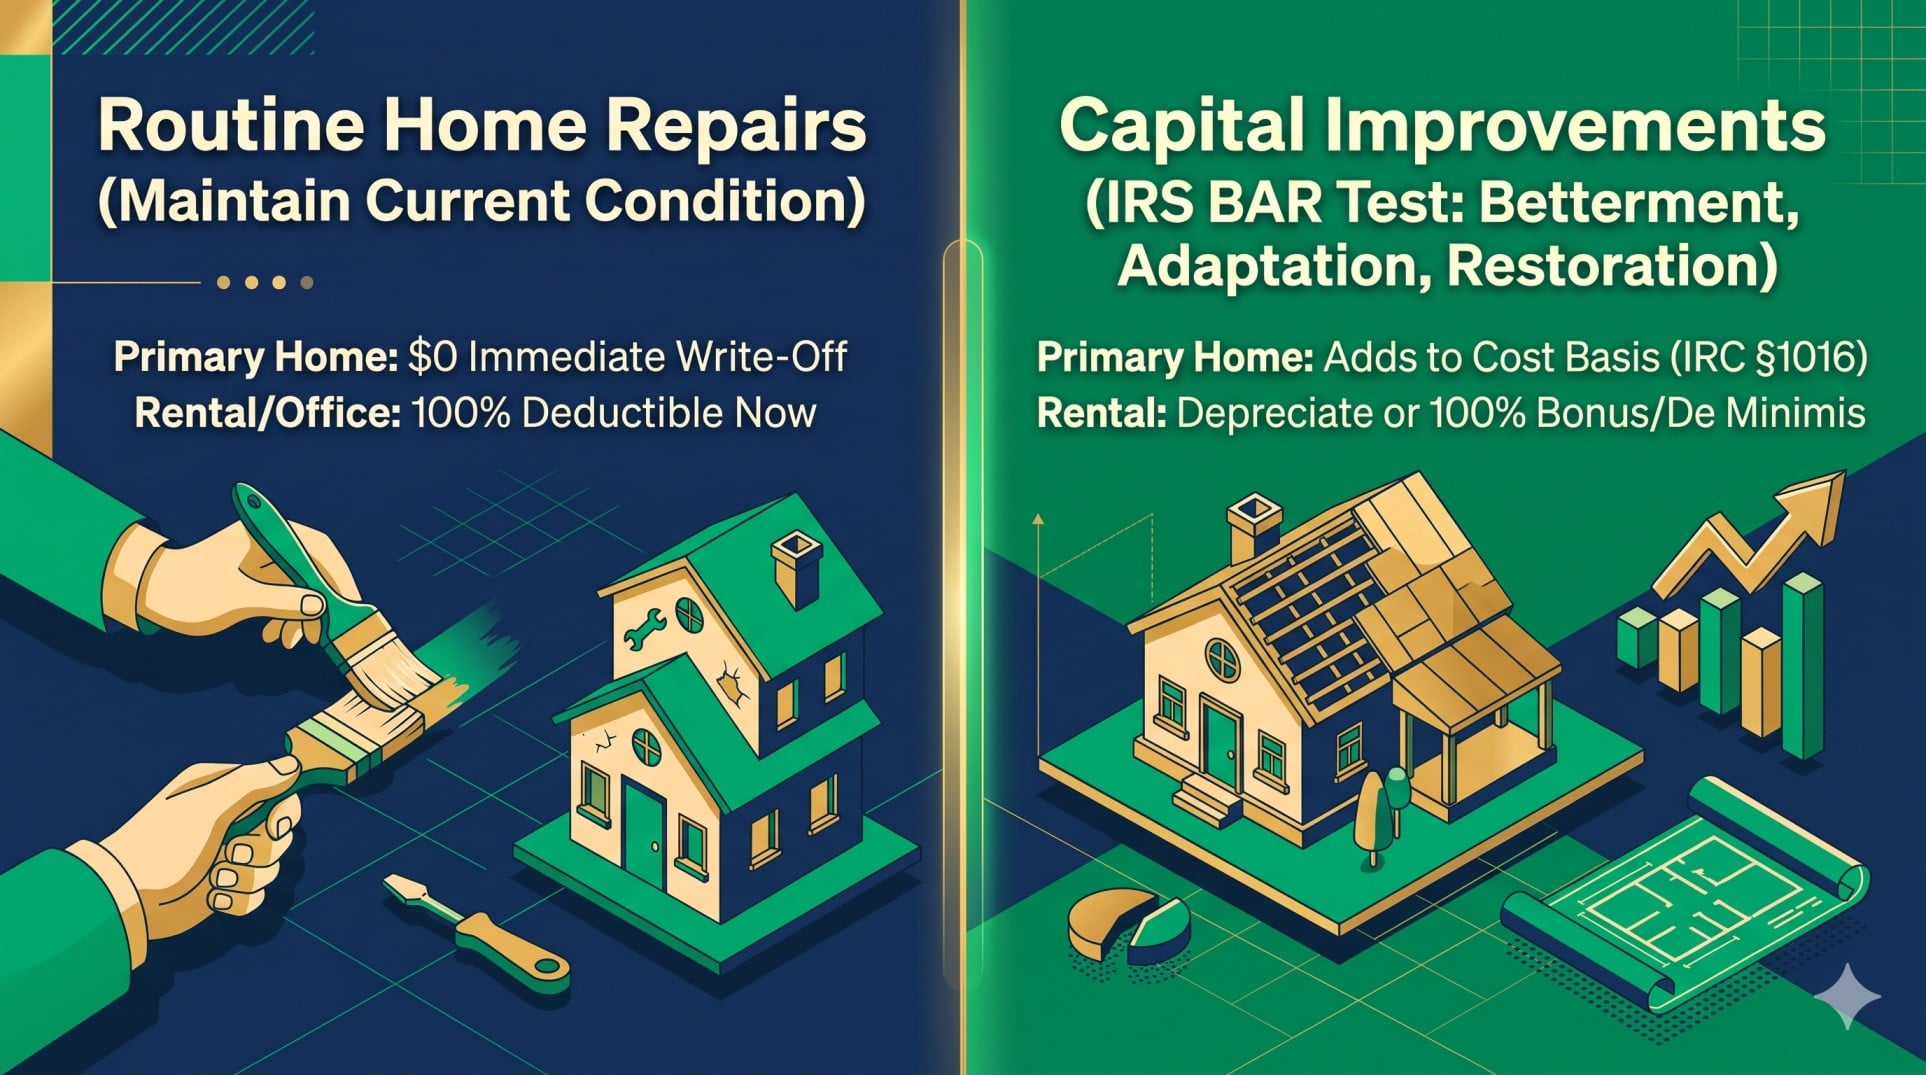
In every real estate tax scenario, repair or improvement is the question that matters. Under IRC Section 263(a) and IRS Publication 523, a capital improvement must add material value, prolong the home’s useful life, or adapt it to a new use, whereas a repair merely maintains ordinary operating condition.
Why do CPAs obsess over home repairs vs. capital improvements? Because the two categories have opposite tax consequences depending on whether you live in the property or rent it out:
- For Your Personal Residence: A capital improvement is good news—it increases your home’s adjusted cost basis (saving you capital gains tax when you sell) and allows you to deduct HELOC interest if financed. A routine repair on a personal residence gives you $0 tax benefit both now and when you sell!
- For a Rental Property or Home Office: A routine repair is the gold standard—it is 100% deductible immediately in the year paid against your rental or business income! A structural capital improvement generally cannot be deducted all at once unless it qualifies for a tangible property safe harbor, Section 179, or 100% bonus depreciation; otherwise, it must be capitalized and depreciated over 27.5 years (residential rental) or 39 years (home office / commercial).
Repairs vs. Improvements: The Classification Test (The IRS “BAR” Rule)
Under Treasury Regulation Section 1.263(a)-3, the IRS uses a three-part mechanical test—universally known by tax practitioners as the BAR Test—to determine when an expenditure crosses the line from a repair into a capital improvement. If a project triggers any one of the three letters, it must be treated as a capital improvement:
- B — Betterment (Treas. Reg. §1.263(a)-3(j)): Does the work fix a pre-existing material defect that existed when you bought the property, materially enlarge or expand the building’s square footage, or materially increase its capacity, productivity, strength, or quality? (Example: Finishing an unfinished basement, adding a deck, or upgrading standard laminate countertops to custom quartz with new cabinetry).
- A — Adaptation (Treas. Reg. §1.263(a)-3(l)): Does the expenditure adapt the property or room to a new or different use that is inconsistent with its intended ordinary use when you placed it in service? (Example: Converting a detached garage into an Accessory Dwelling Unit [ADU] or converting a bedroom into a commercial-grade dental studio).
- R — Restoration (Treas. Reg. §1.263(a)-3(k)): Does the project replace a major component or substantial structural part of the building system (such as the entire roof, the entire HVAC system, or the entire plumbing/electrical system), restore the property after you claimed a casualty loss deduction, or rebuild the property to like-new condition after the end of its economic useful life?
Qualifying Home Improvement Expenses vs. Routine Repairs (IRS Pub. 523 Checklist)
One important trap in IRS Publication 523 (Selling Your Home) is the “General Plan of Rehabilitation” doctrine: if you perform minor repairs (like interior painting or patching drywall) as part of a larger remodeling or restoration project, the IRS allows (and for landlords, requires) you to include those otherwise nondeductible repairs inside the total cost of the capital improvement! Compare common projects side by side below:
| Home System / Area | Qualifying Capital Improvements (Adds to Basis / Capitalized) | Routine Repairs & Maintenance (Maintains Current Condition) |
|---|---|---|
| Exterior & Structure | New roof replacement, new siding, room additions, new deck/patio, new driveway, storm windows, exterior doors, new garage door, fencing, swimming pool. | Replacing a few loose roof shingles, cleaning gutters, repainting exterior trim, sealing a driveway crack, replacing a broken window pane. |
| Interior & Rooms | Complete kitchen or bathroom remodel, finishing a basement or attic, installing new hardwood/tile/carpet flooring throughout, adding built-in bookshelves, new insulation. | Interior room painting, patching drywall holes, refinishing/cleaning existing floors, regrouting bathroom tile, replacing cabinet hardware. |
| Heating, Cooling & Plumbing | New central HVAC system, heat pump, furnace, ductwork, central humidifier, new water heater, septic system, water filtration/softener system, whole-house repiping. | Seasonal furnace tune-up, replacing a thermostat or capacitor, snaking a clogged drain, fixing a leaky faucet or running toilet valve. |
| Electrical, Security & Grounds | Upgrading electrical panel (e.g., 100A to 200A), whole-house rewiring, wired security/fire alarm system, lawn sprinkler system, major permanent landscaping/retaining walls. | Replacing a faulty light switch or outlet, changing smoke detector batteries, routine lawn mowing, tree trimming, and seasonal mulch. |
5 Scenarios Where You Can Write Off Home Improvements or Repairs in 2026
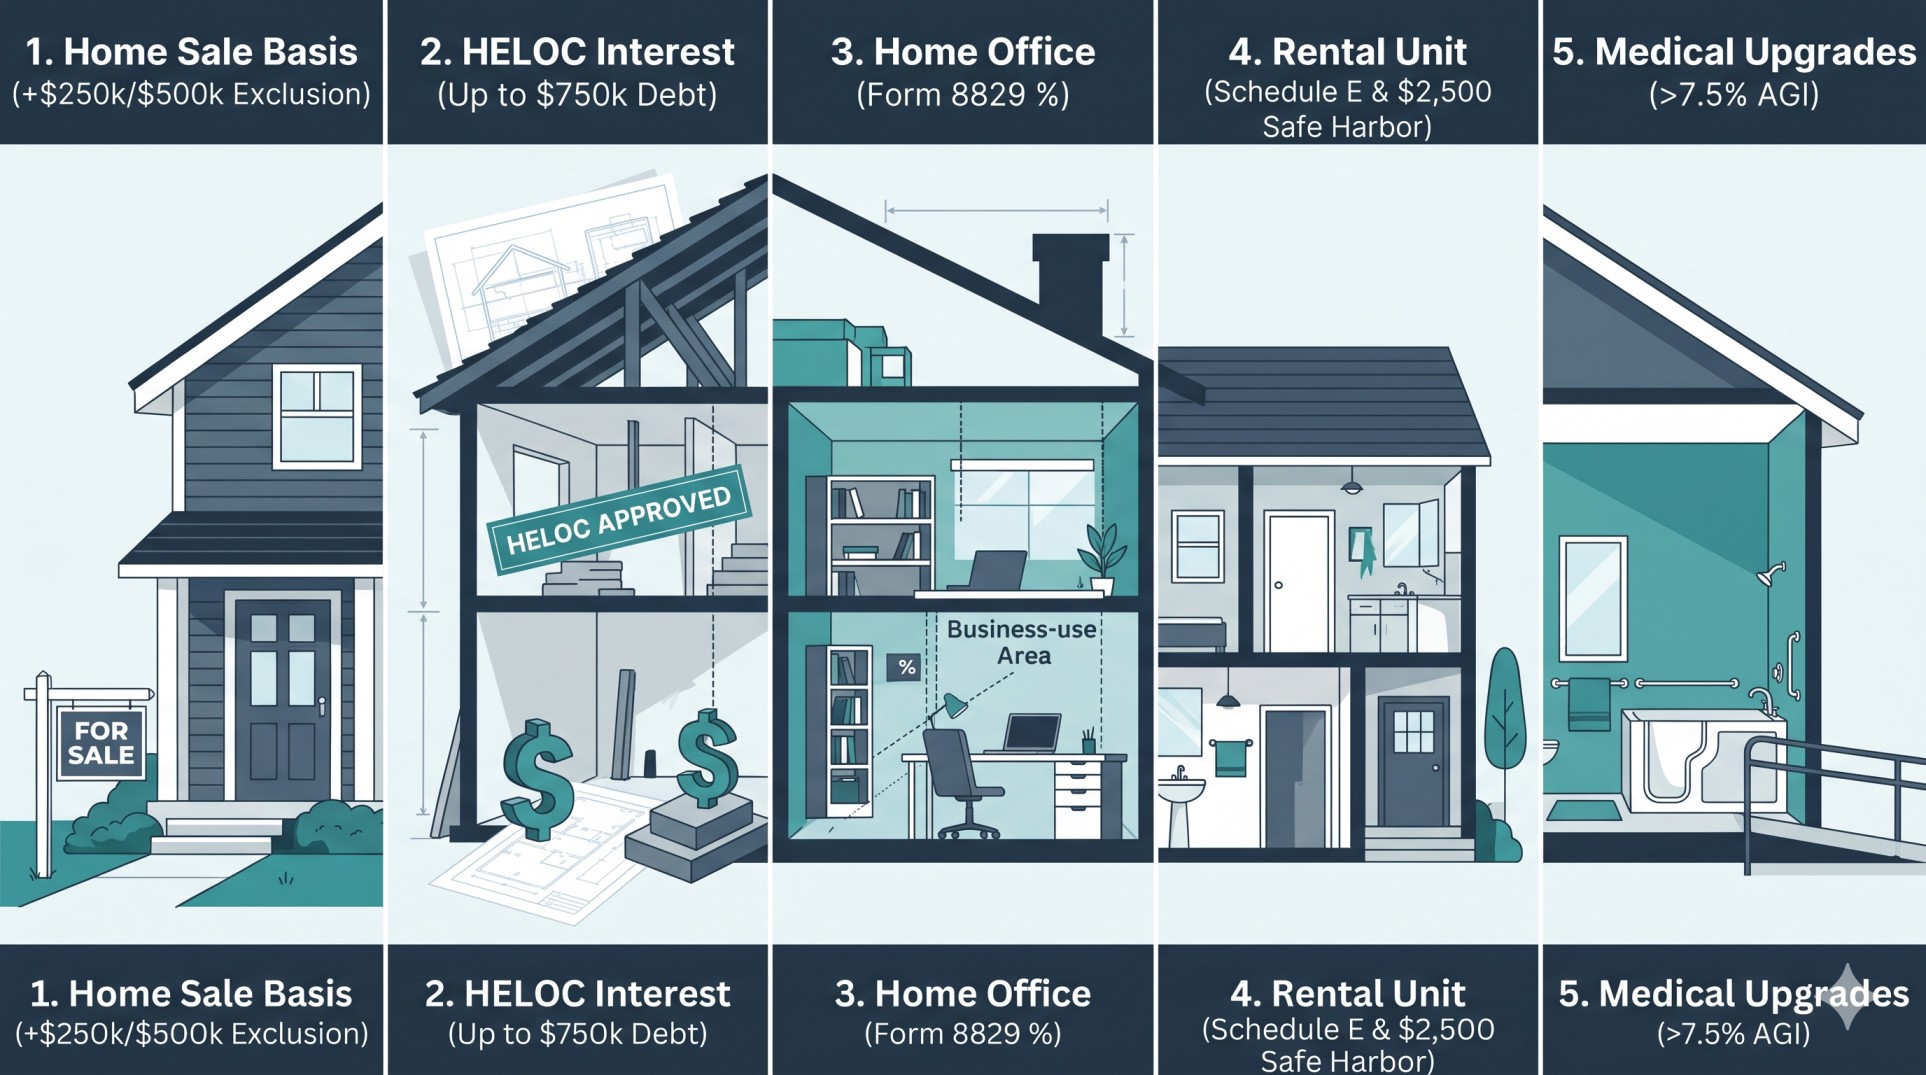
To determine whether you can write off home improvements on your 2026 return or capture a future capital gains shield, match your project against these five statutory scenarios: selling your home, financing with home equity, operating a home office, owning a rental property, or making medical modifications.
Scenario One: Selling the Home — How Do Home Improvements Impact Your Taxes When You Sell the House?
When you sell your primary residence, IRC Section 121 allows you to exclude up to $250,000 of capital gain if you are a Single filer—or up to $500,000 if you file Married Filing Jointly—provided you owned and lived in the home as your main residence for at least 24 months (2 years) out of the 5 years leading up to the sale date.
Because Congress has never indexed that $250,000 / $500,000 exclusion for inflation since enacting it in 1997, decades of home price appreciation mean millions of long-term homeowners in 2026 face a taxable gain exceeding the exclusion limit (or sell a vacation home, second home, or short-held property that gets $0 Section 121 exclusion). That is where qualifying home improvement expenses save you up to 23.8% in federal tax (the 20% top long-term capital gains rate plus the 3.8% Net Investment Income Tax) plus state tax:
- The Adjusted Cost Basis Formula (IRC Section 1016): Your taxable gain is NOT your sale price minus your original purchase price. Instead: Taxable Gain = Selling Price − Selling Expenses (realtor commissions, transfer taxes, legal fees) − Adjusted Cost Basis (Original Purchase Price + Qualifying Acquisition Closing Costs + Cumulative Capital Improvements − Any Depreciation Claimed).
- Every $10,000 of Documented Improvements Cuts Taxable Gain by $10,000: If a single homeowner bought a home for $350,000, invested $120,000 in documented capital improvements (kitchen remodel, new roof, finished basement, and new HVAC), and sells it in 2026 for $750,000 (with $40,000 in selling costs), those $120,000 in improvement receipts raise their basis to $470,000—reducing their net gain to $240,000, which fits 100% tax-free inside the $250,000 Section 121 exclusion! Without those receipts, they would have owed capital gains tax on $110,000 of excess gain.
- Watch the Replacement Rule (IRS Pub. 523): If you add an improvement to basis and later tear it out and replace it before selling (for example, putting on a roof in 2012 and replacing that roof again in 2025), you must remove the cost of the older replaced roof from your basis and include only the current replacement!
Scenario Two: Financing the Project With Home Equity (HELOC & Mortgage Interest Rules in 2026)
What if you don’t want to wait until you sell the house to get a tax break? If you finance your capital improvements using a mortgage, a Home Equity Line of Credit (HELOC), or a home equity loan, you can deduct the interest paid during 2026 on Schedule A (Form 1040), Line 8a—provided you follow the strict post-OBBBA rules under IRC Section 163(h) and IRS Publication 936:
- The Permanent “Buy, Build, or Substantially Improve” Mandate: Under the One Big Beautiful Bill Act (P.L. 119-21), Congress made the TCJA home equity restriction permanent. Interest on a home equity loan or HELOC is deductible only to the extent the borrowed funds are used to buy, build, or substantially improve (i.e., make capital improvements to) the exact qualified residence that secures the loan! If you draw $60,000 on a HELOC to pay off credit cards, buy a car, pay college tuition, or renovate a different property (like using a HELOC on your primary home to remodel a separate rental property, unless traced as a business expense on Schedule E), the interest is **0% deductible** on Schedule A.
- The Permanent $750,000 Combined Debt Ceiling ($375,000 MFS): Your HELOC balance used for improvements is added to your primary mortgage balance. You can deduct interest on up to $750,000 of combined qualified acquisition debt ($375,000 if Married Filing Separately), or up to $1,000,000 ($500,000 MFS) if your original mortgage closed on or before December 15, 2017.
- New for 2026 — Reinstated PMI Deduction & $40,400 SALT Synergy: Starting in Tax Year 2026 under the OBBBA, Private Mortgage Insurance (PMI) premiums (and FHA MIP) are permanently reinstated as deductible mortgage interest on Schedule A for borrowers with AGI up to $100,000 (phasing out completely at $109,000/$110,000 AGI). Even better, because the 2026 SALT deduction cap jumped to $40,400, millions of homeowners who couldn’t clear the standard deduction hurdle in prior years will itemize in 2026—unlocking their HELOC renovation interest deduction!
Scenario Three: The Home Office — Do I Qualify for Home Office Tax Deductions?
The home office tax deduction under IRC Section 280A transforms a portion of your personal residence into business property, allowing you to write off workspace repairs immediately and depreciate workspace improvements.
When asking do I qualify for home office tax deductions in 2026, you must first pass the employment-status gate. Because the One Big Beautiful Bill Act permanently repealed unreimbursed employee business expenses under IRC Section 67(g), W-2 employees working remotely from home cannot claim the home office deduction (unless their employer reimburses them tax-free under an IRC Section 132/62(a)(2)(A) accountable plan). To claim a home office tax deduction on your return, you must have self-employment income (Schedule C), partnership income with allowed unreimbursed expenses (Schedule E), or statutory employee status, and meet two strict physical tests:
- 1. Exclusive and Regular Use: A specific room or separately identifiable area of your home must be used solely for carrying on your trade or business on a regular basis (if your office doubles as a guest bedroom or kids’ playroom after hours, it fails the exclusive-use test—with special exceptions only for licensed day-care facilities and inventory/product sample storage).
- 2. Principal Place of Business: The home office must be your principal place of business—which includes a home office used exclusively and regularly for the administrative or management activities of your business if you have no other fixed location where you conduct substantial administrative activities.
If you choose the Actual Expense Method on Form 8829 (rather than the $5/sq. ft. Simplified Method capped at $1,500), the IRS splits your repair and improvement costs into two buckets based on your Business Use Percentage (e.g., a 250 sq. ft. office inside a 2,500 sq. ft. home = 10% business use):
- Direct Home Office Expenses (100% Allocable): Work performed exclusively inside the home office. Painting the office, repairing a broken office window, or fixing office drywall is a 100% immediate deduction on Form 8829! A capital improvement strictly inside the office (like installing custom built-in cabinetry or a dedicated mini-split AC unit for the office) is 100% business property depreciated over 39 years as nonresidential real property (or potentially eligible for Section 179 / bonus depreciation if classified as tangible personal property or Qualified Improvement Property).
- Indirect Whole-House Expenses (Pro-Rata Business % Allocable): Work that benefits the entire house. A whole-house repair (like $1,200 to fix a furnace blower or patch a roof leak over the living room) is deductible immediately at your 10% business-use share ($120). A whole-house capital improvement (like a $25,000 new roof or $15,000 whole-house HVAC replacement) is depreciated at your 10% business-use share over 39 years on Form 8829! See our self-employed Schedule C and home office deduction guide for complete Form 8829 instructions.
Scenario Four: The Rental Property (Schedule E, 100% Bonus Depreciation & The 3 Safe Harbors)
Landlords—including homeowners who rent out a basement apartment, an ADU, half of a duplex, or a spare bedroom (“house hacking”)—enjoy the most generous renovation write-offs in the tax code on Schedule E (Form 1040).
On a rental property, 100% of ordinary repairs and maintenance (fixing leaks, repainting between tenants, repairing appliances, patching drywall) are deducted in full in the year paid on Schedule E, Line 14. Even when a project crosses the BAR test into a capital improvement, 2026 landlords do NOT have to wait 27.5 years to recover their money if they use these four statutory accelerators:
- 1. The $2,500 De Minimis Safe Harbor Election (Treas. Reg. §1.263(a)-1(f) & IRS Notice 2015-82): By attaching a formal annual election statement to your timely filed 2026 return, you can immediately expense any tangible property item costing $2,500 or less per invoice or per item (as itemized on the invoice)! If you buy a $1,800 refrigerator, a $1,400 stove, three $600 ceiling fan/light packages, and a $2,200 water heater for a rental unit, every single one is 100% deductible in 2026 instead of depreciated over 5 or 27.5 years.
- 2. The Safe Harbor for Small Taxpayers (Treas. Reg. §1.263(a)-3(h)): If your average annual gross receipts are $10 million or less and your rental building’s unadjusted cost basis is $1,000,000 or less, you can elect to immediately deduct both repairs AND capital improvements to the building if your total annual spending on repairs, maintenance, and improvements for that building does not exceed the lesser of $10,000 or 2% of the building’s unadjusted basis!
- 3. The Routine Maintenance Safe Harbor (Treas. Reg. §1.263(a)-3(i)): Allows an immediate deduction (with no dollar cap and no election statement required) for recurring inspection, cleaning, testing, and part-replacement activities that you reasonably expect to perform more than once during a 10-year period.
- 4. Permanent 100% Bonus Depreciation (IRC Section 168(k)) & Section 179 ($2,560,000 Cap in 2026): Under the One Big Beautiful Bill Act, 100% bonus depreciation is permanently restored for qualifying property with a MACRS recovery period of 20 years or less acquired and placed in service after January 19, 2025! That means rental appliances, carpeting, luxury vinyl plank (LVP) floating floors, cabinetry, window treatments (5-year property), and exterior fences, driveways, sidewalks, patios, and landscaping (15-year land improvements) can be written off 100% in Year 1 on Form 4562! And if you qualify for Real Estate Professional Status (REPS) or the short-term rental loophole, those paper losses can offset your W-2 salary up to the 2026 Section 461(l) cap ($256,000 Single / $512,000 MFJ).
The Exception: Medical Necessity — Deducting Medical Home Improvements (IRC Section 213)
The single exception where a homeowner can immediately deduct a renovation to their personal living quarters is when the work is medically necessary. Under IRC Section 213 and Treasury Regulation Section 1.213-1(e)(1)(iii), deducting medical home improvements is permitted on Schedule A, Line 1 when the primary purpose of the capital expenditure is the medical care of the taxpayer, their spouse, or their dependent.
Here is the exact two-step IRS valuation rule from IRS Publication 502 and Revenue Ruling 87-106:
- General Valuation Rule (Cost Minus Home Value Increase): If a medical improvement increases the fair market value (FMV) of your home, your eligible medical expense is the total cost of the project minus the increase in your home’s appraised fair market value. For example, if a cardiologist prescribes a hydrotherapy swimming pool or a residential elevator costing $55,000 for a patient with severe heart disease or multiple sclerosis, and a certified real estate appraisal shows the pool or elevator increased the home’s market value by $20,000, the remaining $35,000 ($55,000 cost − $20,000 value increase) is an eligible medical expense in 2026! (And the $20,000 that added value isn’t lost—it gets added to your home’s cost basis when you sell!).
- The 100% Eligible Accessibility List (IRS Rev. Rul. 87-106 — $0 Value Increase Presumed): Under Revenue Ruling 87-106, the IRS officially rules that specific disability accessibility modifications ordinarily do not increase the fair market value of a house at all—meaning 100% of their cost counts as a qualifying medical expense! This list includes:
- Constructing entrance or exit wheelchair ramps to the residence.
- Widening doorways at entrances or exits, or widening interior hallways and doorways.
- Installing railings, support bars, or grab bars in bathrooms or throughout the home.
- Modifying bathroom facilities (such as installing a roll-in shower, walk-in tub, or accessible sink/toilet).
- Lowering or modifying kitchen cabinets and equipment for wheelchair access.
- Moving or modifying electrical outlets, fixtures, or warning systems/fire alarms for a disabled resident.
- Installing porch lifts and stairway lifts (note: full structural elevators do not get the automatic $0-value presumption and require a before-and-after appraisal).
- Ongoing Operation & Maintenance Write-Offs: Even if part or all of a medical capital improvement was not deductible in the year installed because it increased the home’s value, 100% of the annual cost of operating and maintaining that medical equipment (electricity, water, filter replacements, and service contracts) is an eligible medical expense every year as long as the medical necessity continues!
- Applying the 7.5% of AGI Floor & Schedule A Hurdle: Your qualifying medical home improvement cost is added to your other 2026 out-of-pocket medical, dental, vision, and insurance expenses on Schedule A, Line 1. You deduct the portion that exceeds 7.5% of your Line 11 AGI (IRC Section 213(a)), provided your total Schedule A itemized deductions exceed your 2026 standard deduction ($16,100 Single / $32,200 MFJ).
| Renovation Scenario (2026) | Routine Repairs Deductible Now? | Capital Improvements Deductible Now? | Adds to Home Sale Cost Basis? | IRS Form / Schedule Used |
|---|---|---|---|---|
| 1. Personal Residence (Living Space Only) | No ($0 tax benefit) | No (deferred until home sale) | Yes (100% of capital improvements) | Form 8949 & Schedule D (in year of sale) |
| 2. Financed via HELOC / Home Equity Loan | No (interest on repair-only loans non-deductible) | Interest Only (on up to $750k total acquisition debt) | Yes (underlying project cost adds to basis) | Schedule A, Line 8a (Form 1098) |
| 3. Self-Employed Home Office (Actual Method) | Yes (100% if direct; Business % if whole-house) | Depreciated over 39 years (or Sec. 179/Bonus if eligible) | Yes (less depreciation recaptured at sale) | Form 8829 & Schedule C, Line 30 |
| 4. Rental Property / House Hack Unit | Yes (100% immediate deduction against rent) | Yes / Depreciated (100% Bonus on 5/15-yr, $2,500 De Minimis, or 27.5-yr MACRS) | Yes (adjusted for depreciation claimed) | Schedule E (Lines 14 & 18) & Form 4562 |
| 5. Medically Necessary Modification | Yes (maintenance of medical upgrades counts) | Yes (Cost minus FMV increase, above 7.5% of AGI) | Only the portion that increased FMV | Schedule A, Lines 1–4 |
What Recently Changed: The Energy Credit Sunset & 2025 vs. 2026 Comparison
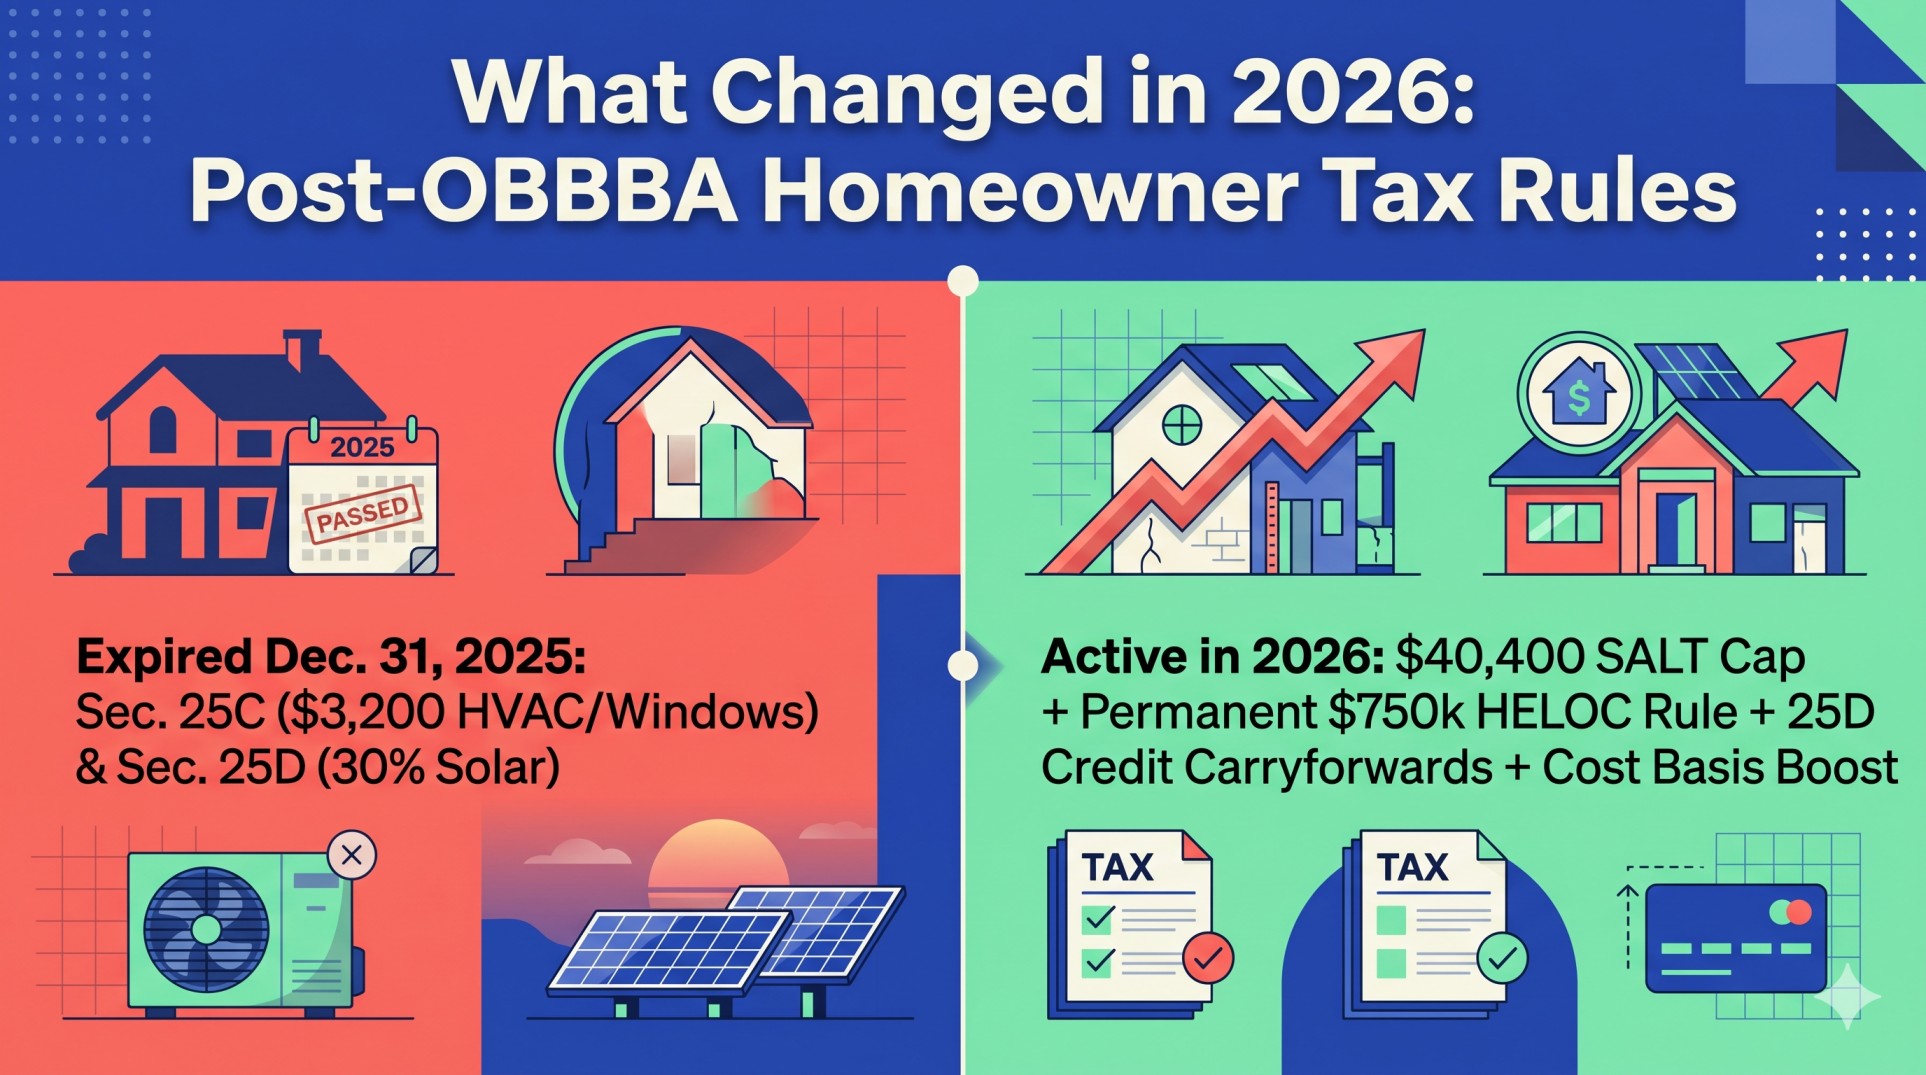
Under the One Big Beautiful Bill Act (P.L. 119-21), both the Section 25C Energy Efficient Home Improvement Credit (up to $3,200/year) and the Section 25D Residential Clean Energy Credit (30% for solar and battery storage) expired after December 31, 2025, changing how 2026 energy upgrades are treated.
If you read outdated 2023 or 2024 articles claiming you can still get a $2,000 federal tax credit for installing a heat pump or a 30% credit for putting solar panels on your roof in 2026, stop immediately. Originally scheduled under the Inflation Reduction Act to run through 2032–2034, Congress terminated both residential energy credits early in July 2025:
- IRC Section 25C (Energy Efficient Home Improvement Credit — EXPIRED for 2026 Installations): No credit is allowed for any heat pump, central AC, furnace, water heater, exterior window, skylight, exterior door, insulation, electrical panel upgrade, or home energy audit placed in service after December 31, 2025. Furthermore, Section 25C was a nonrefundable credit with zero carryforward feature—so nothing carries into 2026.
- IRC Section 25D (Residential Clean Energy Credit — EXPIRED for 2026 Expenditures, Carryforward Allowed!): No new 30% credit is allowed for solar electric panels, solar water heaters, geothermal heat pumps, small wind turbines, or battery storage technology installed after December 31, 2025. Crucial 2026 Exception: Under IRC Section 25D(c), if you installed and placed solar panels or battery storage into service on or before December 31, 2025, and your 30% credit exceeded your 2025 federal tax liability, you can carry forward the unused portion of your 2025 Section 25D credit onto your 2026 Form 5695 to reduce your 2026 taxes!
- What Energy Incentives Still Exist in 2026?
- State-Administered DOE HOMES & HEAR Point-of-Sale Rebates: Funded under the Inflation Reduction Act and administered by state energy offices in 2026, the Home Efficiency Rebates (HOMES) and Home Electrification and Appliance Rebates (HEAR) provide up to $8,000 for heat pumps and up to $14,000 in total upfront rebates for low- and moderate-income households. Under IRS Announcement 2024-19 and IRC Section 136, these rebates are excluded from your taxable gross income (though you cannot include the rebated portion in your home’s cost basis).
- 100% Cost Basis Addition: Any out-of-pocket amount you pay in 2026 for solar panels, geothermal systems, battery walls, new HVAC units, or energy-efficient windows is a 100% qualifying capital improvement that increases your home’s adjusted cost basis under IRC Section 1016!
- State & Utility Solar Tax Credits: Many states (such as New York, South Carolina, Massachusetts, Arizona, and New Mexico) still offer standalone state income tax credits, property tax exemptions, and Solar Renewable Energy Certificates (SRECs) for 2026 solar installations.
| Homeowner Tax Provision | Tax Year 2025 Rules | Tax Year 2026 Rules (Filed in 2027) | Post-OBBBA Statutory Authority |
|---|---|---|---|
| Energy Efficient Home Improvement Credit (Sec. 25C) | Up to $3,200/yr (30% on heat pumps, windows, doors, insulation, panels) | $0 / Expired (terminated for property placed in service after Dec. 31, 2025) | IRC §25C(i), as amended by OBBBA (P.L. 119-21) |
| Residential Clean Energy Credit (Sec. 25D — Solar/Battery) | 30% of cost (uncapped) for systems placed in service by Dec. 31, 2025 | $0 for new 2026 installs; prior-year unused credit carryforwards still allowed on 2026 Form 5695! | IRC §25D(c) & (h), as amended by OBBBA (P.L. 119-21) |
| HELOC & Home Equity Loan Interest Deduction | Deductible on up to $750,000 combined debt if used to substantially improve home | Permanently extended at $750,000 ($375,000 MFS) for home improvements | IRC §163(h)(3)(F), made permanent by OBBBA |
| Private Mortgage Insurance (PMI / FHA MIP) Deduction | Expired / Not deductible ($0) | Reinstated & Permanent! Deductible as mortgage interest (phases out $100k–$110k AGI) | IRC §163(h)(3)(E), reinstated starting in Tax Year 2026 |
| State and Local Tax (SALT) Deduction Cap (Schedule A) | $40,000 ($20,000 MFS), phasing down over $500,000 MAGI | $40,400 ($20,200 MFS), phasing down over $505,000 MAGI (makes itemizing much easier!) | IRC §164(b)(6); IRS Rev. Proc. 2025-32 |
| Rental Property Bonus Depreciation (5- & 15-Yr Assets) | 100% for property acquired & placed in service after Jan. 19, 2025 | Permanently 100% for appliances, flooring, fences, driveways & land improvements | IRC §168(k), made permanent by OBBBA |
| Base Standard Deduction (Schedule A Hurdle) | $15,750 Single / $23,625 HOH / $31,500 MFJ | $16,100 Single / $24,150 HOH / $32,200 MFJ (+$6,000 Senior Bonus on Sch. 1-A) | IRC §63(c)(2); IRS Rev. Proc. 2025-32, §4.14 |
4 Real-World Hypothetical Scenarios With Step-by-Step 2026 Tax Math
To see how the 2026 standard deduction ($16,100 Single / $32,200 Married Filing Jointly), the $40,400 SALT cap, the 7.5% AGI medical floor, the $2,500 De Minimis Safe Harbor, and the Section 121 home sale exclusion work in practice, walk through these four complete 2026 scenarios.
Case Study 1: Married Homeowners Using a HELOC for a $100,000 Kitchen Remodel + Selling Later
Taxpayer Profile: David and Sarah file Married Filing Jointly in 2026 with a combined W-2 Adjusted Gross Income (and MAGI) of $280,000 (putting them in the 24% federal marginal tax bracket, which spans $211,401 to $403,550 in 2026). They live in New York, have a $450,000 primary mortgage paying $22,000 in annual interest, and pay $29,000 in combined state income and property taxes. In January 2026, they take out a $100,000 HELOC at 7.5% interest (paying $7,500 of HELOC interest in 2026) and spend $80,000 of the HELOC on a complete kitchen remodel and $20,000 to pay off a personal auto loan.
- Step 1 (Tracing the Eligible HELOC Interest Under IRC §163(h)): Because their combined mortgage ($450,000) plus HELOC ($100,000) is $550,000—well under the permanent $750,000 cap—the debt limit is satisfied. However, only 80% of the HELOC proceeds ($80,000 ÷ $100,000) were used to “substantially improve” the home securing the loan; the $20,000 used to pay off the auto loan is personal debt. Thus, 80% of the $7,500 HELOC interest ($6,000) is deductible on 2026 Schedule A, Line 8a, while $1,500 is nondeductible!
- Step 2 (2026 Schedule A vs. $32,200 Standard Deduction):
- SALT Deduction: Full $29,000 (since it is under the $40,400 2026 SALT cap and their $280,000 MAGI is below $505,000).
- Primary Mortgage + Deductible HELOC Interest: $22,000 + $6,000 = $28,000.
- Total 2026 Schedule A Itemized Deductions: $29,000 + $28,000 = $57,000 (beating the $32,200 joint standard deduction by $24,800!).
- Immediate 2026 Tax Savings From the $6,000 HELOC Interest Write-Off: $6,000 × 24% marginal bracket = $1,440 saved on their 2026 tax return!
- Step 3 (Future Home Sale Cost Basis Benefit): Suppose David and Sarah originally bought the house in 2014 for $400,000 and sell it in late 2026 for $1,020,000 (with $50,000 in realtor/closing costs). Without the kitchen remodel, their net gain would be $570,000 ($1,020,000 − $50,000 − $400,000), leaving $70,000 of taxable gain above the $500,000 Section 121 exclusion. Adding the $80,000 kitchen remodel raises their adjusted cost basis to $480,000, reducing their net gain to $490,000—wiping out 100% of their capital gains tax and saving another $13,160 (15% LTCG + 3.8% NIIT on $70,000)!
Case Study 2: Self-Employed Consultant Claiming Direct & Whole-House Repairs on Form 8829
Taxpayer Profile: Marcus, a single self-employed management consultant in Illinois, earns $160,000 in gross Schedule C revenue in 2026 (in the 24% single income tax bracket plus 15.3% Self-Employment Tax). He uses a 300 sq. ft. room in his 2,000 sq. ft. home exclusively and regularly as his principal place of business (15% Business Use Percentage). During 2026, Marcus pays:
- $2,400 to repaint his home office, repair damaged drywall inside the office, and replace cracked window panes inside the office (Direct Repair Expenses).
- $3,000 to repair a leaking main water line and service the whole-house furnace (Indirect Whole-House Repair Expenses).
- $20,000 to install a brand-new roof on the entire house in June 2026 (Indirect Whole-House Capital Improvement).
- Calculating Marcus’s 2026 Form 8829 Home Office Write-Off:
- Direct Office Repairs: 100% of the $2,400 spent exclusively inside the office is deductible immediately on Form 8829!
- Indirect Whole-House Repairs: 15% of the $3,000 whole-house plumbing/furnace repairs = $450 deductible immediately on Form 8829.
- Indirect Whole-House Roof Capital Improvement: 15% of the $20,000 new roof ($3,000 depreciable basis) is depreciated over 39 years as nonresidential real property (using the June mid-month convention factor of 1.391% in Year 1 = $42 in 2026 depreciation, with the remaining 85% personal portion—$17,000—added to his home’s cost basis!).
- Total Immediate 2026 Repair & Improvement Write-Off on Schedule C, Line 30: $2,400 + $450 + $42 = $2,892 (on top of his 15% share of mortgage interest, property taxes, utilities, insurance, and whole-house depreciation!).
- 2026 Cash Tax Saved on Those Repairs Alone: Because Schedule C deductions reduce both his 24% income tax and his 15.3% self-employment tax (approximately 36.3% combined effective marginal rate after QBI/SE adjustments), that $2,892 write-off saves Marcus roughly $1,050—while he still claims his full $16,100 single standard deduction on Form 1040, Line 12!
Case Study 3: Landlord Using the $2,500 De Minimis Safe Harbor & 100% Bonus Depreciation
Taxpayer Profile: Priya owns a residential rental single-family home in Ohio (unadjusted building basis of $280,000) reported on Schedule E, and her household MAGI is $95,000 (qualifying her for the $25,000 active participation rental allowance under IRC Section 469(i) in the 22% marginal bracket). Between tenants in 2026, she spends $21,300 on four projects:
- Project A ($3,500): Patching drywall, repainting three bedrooms, and fixing a leaky shower valve -> 100% deductible immediately as a Repair ($3,500) on Schedule E, Line 14.
- Project B ($4,800): Buying a new stainless steel refrigerator ($1,900), a new range/oven ($1,300), and a new washer/dryer set ($1,600), all itemized separately on the store invoice -> Because each item is under $2,500, Priya attaches the Treasury Regulation Section 1.263(a)-1(f) De Minimis Safe Harbor election statement to her 2026 return and deducts 100% ($4,800) immediately as an operating expense in 2026!
- Project C ($13,000): Installing new luxury vinyl plank (LVP) flooring throughout the rental ($7,000 — 5-year property) and pouring a new concrete driveway apron and privacy fence ($6,000 — 15-year land improvement) -> Even though both exceed the $2,500 De Minimis threshold and fail the Small Taxpayer Safe Harbor (since total building work of $21,300 exceeds 2% of $280,000 = $5,600), both have MACRS recovery periods under 20 years. Under the OBBBA’s permanent 100% bonus depreciation (IRC Section 168(k)), Priya writes off 100% ($13,000) in Year 1 on 2026 Form 4562!
- Total 2026 Deduction: Priya writes off 100% of her $21,300 spending on her 2026 return ($3,500 repair + $4,800 De Minimis Safe Harbor + $13,000 100% Bonus Depreciation), saving $4,686 in 2026 federal income tax ($21,300 × 22%)! Explore how engineering studies unlock even larger write-offs in our cost segregation and 100% bonus depreciation guide.
Case Study 4: Retiree Deducting Medical Home Improvements Under IRC Section 213
Taxpayer Profile: Arthur (age 72) and Helen (age 70) file Married Filing Jointly in 2026 with an Adjusted Gross Income (and MAGI) of $110,000. After Arthur suffers a stroke in early 2026, his physician prescribes home accessibility modifications so he can live safely at home. In 2026, they pay:
- $18,000 to construct an exterior wheelchair ramp, widen three interior doorways, install bathroom grab bars, and convert their tub into a barrier-free roll-in shower.
- $26,000 to install a residential two-story elevator. A certified residential appraiser documents that the elevator increased the fair market value of their home by $10,000.
- $6,250 in other unreimbursed 2026 medical, dental, hearing aid, and Medicare Part B/D premium expenses.
- $16,500 in state and local property taxes and $3,500 in charitable donations.
- Step 1 (Calculating Qualifying Medical Home Improvement Expenses Under Rev. Rul. 87-106):
- Ramp, Doorways, Grab Bars & Roll-In Shower ($18,000): Under Revenue Ruling 87-106, these accessibility upgrades are presumed to add $0 to the home’s market value -> 100% ($18,000) qualifies as a medical expense!
- Residential Elevator ($26,000 Cost − $10,000 Value Increase): Subtracting the $10,000 appraised value increase leaves $16,000 as a qualifying medical expense in 2026 (and the $10,000 value increase is added to their home’s cost basis).
- Total 2026 Medical Expenses (Schedule A, Line 1): $18,000 + $16,000 + $6,250 = $40,250.
- Step 2 (Subtracting the 7.5% of AGI Medical Floor): 7.5% of their $110,000 AGI is $8,250. Subtracting $8,250 from $40,250 yields an allowable Schedule A, Line 4 Medical Deduction of $32,000!
- Step 3 (Stacking Schedule A + The $12,000 Schedule 1-A Senior Bonus!):
- On Schedule A, Arthur and Helen combine their $32,000 medical deduction, their $16,500 SALT deduction, and their $2,950 charitable deduction ($3,500 minus the 0.5% of AGI itemizer floor of $550) = $51,450 on Form 1040-SR, Line 12 (easily beating the $35,500 senior standard deduction by $15,950!).
- Even better: because the OBBBA allows itemizers to claim the $6,000 per-person Schedule 1-A senior deduction on Line 13b (and their $110,000 MAGI is below the $150,000 joint phase-out floor), they add another $12,000 on Line 13b!
- Total 2026 Deductions (Line 14): $51,450 + $12,000 = $63,450—slashing their taxable income from $110,000 down to $46,550 (in the 12% bracket!). For more retirement tax rules, read our 2026 standard deduction for seniors over 65 guide.
Step-by-Step Guide: How to Claim and Report Home Improvements on Your 2026 Return
To legally write off home improvements or repairs on your 2026 federal tax return (filed by April 15, 2027), you must report the expenditure on the exact IRS form and line corresponding to your property’s use—never lump renovation costs onto a single generic line.
Follow this form-by-form reporting roadmap for your 2026 return:
- For Medical Home Modifications (Schedule A, Lines 1–4):
- Obtain a written prescription or letter of medical necessity from your physician and (for items outside the Rev. Rul. 87-106 safe-harbor list, such as elevators or pools) a written before-and-after real estate appraisal.
- Enter your total qualifying out-of-pocket medical expenses (including the eligible portion of the home modification) on Schedule A (Form 1040), Line 1.
- Multiply your Form 1040, Line 11 AGI by 7.5% (0.075) on Line 3, and enter the deductible excess on Schedule A, Line 4.
- For HELOC / Home Equity Renovation Interest & PMI (Schedule A, Line 8a):
- Collect Form 1098 (Mortgage Interest Statement) from your primary mortgage lender and your HELOC lender.
- Verify that your combined average loan balance did not exceed $750,000 ($375,000 MFS) and multiply your HELOC interest by the exact percentage of loan proceeds spent on capital improvements to the home securing the loan.
- Enter your deductible mortgage and HELOC interest (plus qualifying 2026 PMI premiums if AGI is under $109,000/$110,000) on Schedule A, Line 8a (or Line 8b if not reported on Form 1098).
- For Self-Employed Home Office Repairs & Improvements (Form 8829 & Schedule C, Line 30):
- Measure your exclusive office square footage and divide by your total home square footage in Part I of Form 8829 (Expenses for Business Use of Your Home).
- In Part II, Line 21 of Form 8829 (“Repairs and maintenance”), enter 100% of direct office repairs in Column (a) and 100% of whole-house indirect repairs in Column (b) (which automatically multiplies by your Business Use Percentage).
- In Part III of Form 8829 (and Form 4562 if placed in service during 2026), calculate 39-year MACRS depreciation on home office capital improvements, and carry the total allowable deduction from Form 8829, Line 36 to Schedule C (Form 1040), Line 30.
- For Rental Property Repairs, Safe Harbors & 100% Bonus Depreciation (Schedule E & Form 4562):
- Report ordinary repairs and Routine Maintenance Safe Harbor expenses on Schedule E (Form 1040), Part I, Line 14 (“Repairs”).
- To use the $2,500 De Minimis Safe Harbor, expense the qualifying items on your books, report them on Schedule E (Line 14 or Line 19 “Other”), and attach a formal statement to your return titled: “Section 1.263(a)-1(f) de minimis safe harbor election” containing your name, address, SSN/EIN, and a declaration that you are making the de minimis safe harbor election under Treas. Reg. §1.263(a)-1(f).
- To claim 100% Bonus Depreciation on 5-, 7-, or 15-year rental property improvements (or 27.5-year MACRS depreciation on structural building improvements) placed in service in 2026, complete Form 4562 (Parts II and III) and carry the total depreciation to Schedule E, Line 18.
- For Selling Your Primary or Secondary Home in 2026 (Form 8949 & Schedule D):
- Use the worksheets in IRS Publication 523 to sum your original purchase price, acquisition closing costs, and all lifetime capital improvements (minus any casualty losses, energy rebates, or home office/rental depreciation claimed) to establish your Adjusted Cost Basis.
- If you received Form 1099-S (Proceeds From Real Estate Transactions) or your gain exceeds the $250,000 / $500,000 Section 121 exclusion, report the sale on Form 8949 (Part II for long-term) and Schedule D, entering your adjusted cost basis in Column (e) and using adjustment code “H” in Column (f) to exclude up to $250,000 / $500,000 of eligible primary residence gain.
- For Prior-Year Solar Credit Carryforwards (2026 Form 5695):
- While no new Section 25C or 25D credits apply to 2026 installations, if you have an unused Section 25D Residential Clean Energy Credit carryforward from your 2025 Form 5695 (Line 16), enter that carryforward on your 2026 Form 5695 and transfer the allowed credit to Schedule 3 (Form 1040), Line 5a.
Documenting Now So You’re Not Guessing Later: IRS Audit-Proof Recordkeeping
Under IRC Section 6001, the burden of proving your adjusted cost basis, HELOC tracing, or rental repair classification rests 100% on you. Because a home sale audit occurs three years after you sell the house, you must keep capital improvement receipts for the entire time you own the home plus at least three to seven years after selling.
Why is documenting now so you’re not guessing later so critical? In U.S. Tax Court cases where homeowners sold a residence after 15 or 20 years of ownership and claimed “$150,000 in renovations” based on memory or Zillow photos, IRS examiners disallowed the unsubstantiated improvements—triggering five-figure capital gains tax bills and 20% accuracy-related penalties under IRC Section 6662.
The HELOC Commingling Trap: If you take out a $75,000 home equity loan or HELOC for a renovation in 2026, never deposit those borrowed funds into your everyday personal checking account where you also buy groceries and pay credit card bills!
Under the interest-tracing rules of Treasury Regulation Section 1.163-8T, keep a dedicated bank account (or pay the contractor directly from the HELOC draw) so every dollar of borrowed principal links directly to a capital improvement invoice.
5 Documents to Save in Your Permanent Digital “Home Basis Vault”
- 1. Itemized Contractor Contracts & Invoices: Never accept a one-line invoice reading “$18,000 — Work on house.” Have your contractor itemize repairs separately from capital improvements, list individual appliance/fixture prices (so items under $2,500 clearly qualify for the De Minimis Safe Harbor on rentals), and specify the exact room worked on (for Form 8829 direct home office write-offs).
- 2. Proof of Payment: Keep PDFs of cancelled checks, bank wire confirmations, HELOC draw statements, or credit card statements matching every invoice (cash payments without bank proof or signed receipts are routinely rejected in audits).
- 3. Municipal Building Permits & Inspection Sign-Offs: City and county building permits establish an indisputable third-party record of the scope of work and the exact date the improvement was placed in service.
- 4. Closing Disclosure / HUD-1 Settlement Statement From Purchase: Your original purchase Closing Disclosure contains deductible basis additions that most homeowners forget (such as owner’s title insurance, survey fees, recording fees, and transfer taxes paid at purchase).
- 5. Physician Letters & Appraisals for Medical Upgrades: For IRC Section 213 medical modifications, retain the doctor’s dated medical necessity recommendation and the certified before-and-after real estate appraisal in your tax folder. If you ever receive an inquiry letter, follow our step-by-step guide on how to respond to an IRS audit notice.
Federal vs. State Rules: State Energy Credits, Rebates & Depreciation Conformity
While federal residential energy credits expired at the end of 2025, dozens of states still offer generous 2026 state tax credits and rebates for solar, heat pumps, historic rehabilitation, and senior accessibility upgrades—while several states decouple from federal 100% bonus depreciation on rental properties.
Always check these three state-level tax interactions when planning a 2026 project:
- 1. Standalone State Solar, Heat Pump & Accessibility Tax Credits in 2026: Even without federal Section 25C/25D credits in 2026, states such as New York (25% Solar Energy System Equipment Credit up to $5,000), South Carolina (25% solar/geothermal credit), Massachusetts (15% residential energy credit up to $1,000 + Mass Save rebates), Arizona (25% solar credit up to $1,000), and Virginia / Maryland / Missouri (state livable home / accessibility tax credits for seniors and disabled residents) provide direct state tax reductions on your 2026 state return!
- 2. State Itemizing When Taking the Federal Standard Deduction: In states like California, New York, New Jersey, Arizona, Delaware, Hawaii, Idaho, Iowa, Kentucky, Minnesota, Montana, North Carolina, and Oregon, you are allowed to itemize deductions on your state income tax return even if you take the $16,100 or $32,200 standard deduction on your federal Form 1040! That means a California homeowner whose medical home improvements and HELOC interest total $24,000 (below the $32,200 federal joint standard deduction, but more than double California’s ~$11,400 state standard deduction) can still write off those costs on their California Form 540!
- 3. State Non-Conformity to Federal 100% Bonus Depreciation on Rentals: If you claim 100% bonus depreciation under IRC Section 168(k) on 5- and 15-year rental property improvements on your 2026 federal return, remember that major states—including California, New York, New Jersey, Pennsylvania, Illinois, and Massachusetts—decouple from federal bonus depreciation and require you to depreciate those rental upgrades over their standard MACRS lives on your state tax return.
Frequently Asked Questions About Writing Off Home Improvements & Repairs
1. Can I write off a new roof or HVAC system on my personal home in 2026?
No, you cannot deduct the cost of a new roof or HVAC system on your personal residence on your 2026 tax return, and the Section 25C federal energy credit for HVAC systems expired on December 31, 2025. However, both a full roof replacement and a new HVAC system are qualifying capital improvements under IRS Publication 523: you add 100% of their cost to your home’s adjusted cost basis to reduce capital gains tax when you sell (and if you financed them with a HELOC, the interest is deductible on Schedule A).
2. Did the 30% federal solar tax credit and $3,200 energy credit expire for 2026?
Yes. Under the One Big Beautiful Bill Act (P.L. 119-21), both the Section 25C Energy Efficient Home Improvement Credit ($3,200 cap) and the Section 25D Residential Clean Energy Credit (30% solar/battery credit) were terminated for property placed in service or expenditures made after December 31, 2025. Only taxpayers who placed solar or battery systems in service by December 31, 2025, and have an unused Section 25D credit carryforward can claim that carryforward on their 2026 Form 5695.
3. Can I deduct the value of my own “sweat equity” DIY labor when remodeling my house?
No—under IRS Publication 523 and IRC Section 1016, you can never deduct or add the value of your own unpaid labor (or unpaid help from family and friends) to your home’s cost basis, nor can landlords deduct their own DIY labor on Schedule E. You can only include your actual out-of-pocket costs for materials, supplies, equipment rentals, building permits, and paid third-party contractors or laborers.
4. Is HELOC or home equity loan interest tax deductible in 2026?
Yes, but only if you itemize on Schedule A and used the borrowed funds to buy, build, or substantially improve the exact qualified residence that secures the HELOC or home equity loan. The One Big Beautiful Bill Act made this TCJA restriction permanent, along with the $750,000 ($375,000 MFS) cap on combined primary mortgage and home equity acquisition debt.
5. Can W-2 remote employees claim a home office tax deduction for remodeling their workspace in 2026?
No. The One Big Beautiful Bill Act permanently repealed all miscellaneous itemized deductions subject to the 2% AGI floor under IRC Section 67(g), which permanently bars W-2 employees from claiming a home office deduction on Schedule A. Only self-employed individuals (Schedule C), qualifying partners, and statutory employees can claim the home office deduction on Form 8829—though W-2 employees can ask their employer to reimburse workspace costs tax-free under an IRC Section 132 accountable plan.
6. What happens if I remodel my kitchen in 2015 and remodel it a second time in 2026 before selling?
Under IRS Publication 523, you cannot double-count replaced improvements in your home’s cost basis. When you tear out the 2015 kitchen remodel to install a new kitchen in 2026, you must subtract the cost of the removed 2015 kitchen improvements from your basis and add the cost of the new 2026 kitchen remodel.
7. How does the $2,500 De Minimis Safe Harbor work for rental property repairs and appliances in 2026?
Under Treasury Regulation Section 1.263(a)-1(f) and IRS Notice 2015-82, landlords who attach an annual De Minimis Safe Harbor election statement to their tax return can immediately deduct (rather than depreciate) any tangible property item or improvement costing $2,500 or less per invoice or per item as substantiated on the invoice. Make sure delivery and installation charges are allocated across the items on the invoice so each item stays at or below $2,500.
8. What if my home improvement was paid for by a homeowner’s insurance claim after a storm?
You can only deduct or add to cost basis your unreimbursed out-of-pocket costs (such as your insurance deductible and any upgrade costs you paid above the insurance payout). Any portion of a roof replacement or restoration paid for or reimbursed by your insurance company (or by a tax-free government disaster or energy rebate) cannot be deducted or added to your basis.
9. Can I deduct radon mitigation, lead paint removal, or asbestos remediation on my home?
For a rental property or qualifying home office, environmental remediation (radon, lead paint, mold, or asbestos removal) is generally deductible or capitalizable as a business/rental expense. For a personal residence, it counts as a capital improvement that adds to your cost basis if it permanently remedies a defect—and in specific cases where a physician certifies that lead paint removal or air filtration is necessary to treat a child’s lead poisoning or severe respiratory disease, the cost exceeding the home’s value increase can qualify as a medical expense under IRC Section 213.
Final 2026 Tax Planning Checklist for Homeowners and Investors
Knowing when you can and cannot write off home improvements keeps you from leaving thousands of dollars on the table—or triggering an avoidable IRS disallowance. Even when a project on your primary residence doesn’t produce an immediate write-off on your 2026 Form 1040, tracking every capital improvement invoice under the BAR test protects your home sale profit above the $250,000 / $500,000 Section 121 exclusion and unlocks the Schedule A deduction for HELOC interest.
Before you sign your next contractor agreement in 2026, put four habits into practice: ask contractors to itemize home repairs vs. capital improvements (and individual appliances under $2,500 for rental properties) on separate lines, keep HELOC renovation funds in a dedicated account for clean interest tracing, file your De Minimis Safe Harbor election and Form 4562 for 100% bonus depreciation on rental upgrades, and store digital PDFs of every invoice and proof of payment in a permanent home basis folder well before the April 15, 2027 filing deadline.
Disclaimer: This content provides general information for educational purposes only and reflects federal tax laws applicable to Tax Year 2026 (returns filed in 2027). Tax laws are complex and subject to change. This article does not constitute professional tax, legal, or accounting advice. Always consult a certified public accountant (CPA), enrolled agent (EA), or qualified tax attorney regarding your specific financial situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.
