
Filing military taxes accurately requires separating taxable base compensation from dozens of statutory exclusions enacted specifically for the U.S. Armed Forces. Claiming all available 2026 tax benefits for active duty military and **veterans** can legally trim thousands of dollars off your federal and state tax bills when you file in 2027. Service members who treat their Leave and Earnings Statement (LES) like a civilian paycheck often overpay the IRS or miss lucrative refundable credits.
Following the enactment of the One Big Beautiful Bill Act (OBBBA) and the release of IRS Revenue Procedure 2025-32, several inflation-adjusted thresholds, mileage rates, and permanent statutory rules govern Tax Year 2026. Below is the complete, line-by-line technical guide covering tax-free allowances, combat pay rules, permanent change of station (PCS) moving expenses, veteran disability exemptions, and multi-state residency laws.
⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- 2026 Combat Zone Tax Exclusion (IRC § 112): Enlisted personnel and warrant officers exclude 100% of their military pay for any month they serve at least one day in a designated combat zone. For 2026, the commissioned officer exclusion cap rises to $11,391.90 per month ($11,166.90 senior enlisted basic pay cap plus $225 Hostile Fire/Imminent Danger Pay). Individual 2026 returns are due April 15, 2027.
- Permanent PCS Moving Deduction & Split 2026 Mileage Rates: The OBBBA permanently eliminated moving deductions for civilians, leaving active duty service members under PCS orders (and certain intelligence personnel) as the sole taxpayers eligible to file Form 3903. Due to a mid-year IRS adjustment, the 2026 military moving mileage rate is 20.5 cents per mile from January 1 to June 30, 2026, and 23.5 cents per mile from July 1 to December 31, 2026.
- Post-OBBBA Standard Deduction & Child Tax Credit: For Tax Year 2026, the standard deduction is $16,100 for Single/MFS, $32,200 for Married Filing Jointly, and $24,150 for Head of Household. The Child Tax Credit is permanently expanded to $2,200 per qualifying child (with up to $1,700 refundable via the Additional Child Tax Credit).
- Veteran Disability & Retroactive Claims: VA disability compensation and Combat-Related Special Compensation (CRSC) are 100% excluded from federal and state gross income. Under the Strickland doctrine, veterans who receive a retroactive VA disability rating can file Form 1040-X to claim tax refunds on reclassified DoD retirement pay.
Table of Contents
- ⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- Understanding Military Taxes: Taxable Pay vs. Tax-Free Allowances
- Combat Pay Exclusion and 2026 Tax Benefits for Active Duty Military
- Deducting PCS Moving Expenses on Form 3903 in 2026
- SCRA State Tax Rules for Service Members and Military Spouses
- 2026 Tax Benefits for Veterans and Disabled Retirees
- Step-by-Step Guide to Filing Your 2026 Military Tax Return in 2027
- Frequently Asked Questions About Military Taxes in 2026
- Final Year-End Tax Planning Steps for Service Members
Understanding Military Taxes: Taxable Pay vs. Tax-Free Allowances
Under federal military taxes law, all basic pay, special incentive pay, and non-combat bonuses earned by service members are subject to federal income and FICA taxes, whereas living, housing, and subsistence allowances are 100% excluded from gross income under IRC Section 134.
According to IRS Publication 3 (Armed Forces’ Tax Guide), the Defense Finance and Accounting Service (DFAS) automatically separates your compensation before generating your annual Form W-2. Knowing which entitlements enter Box 1 (Taxable Wages) versus which remain permanently off your tax return allows you to project your effective tax bracket and qualify for income-tested tax credits.
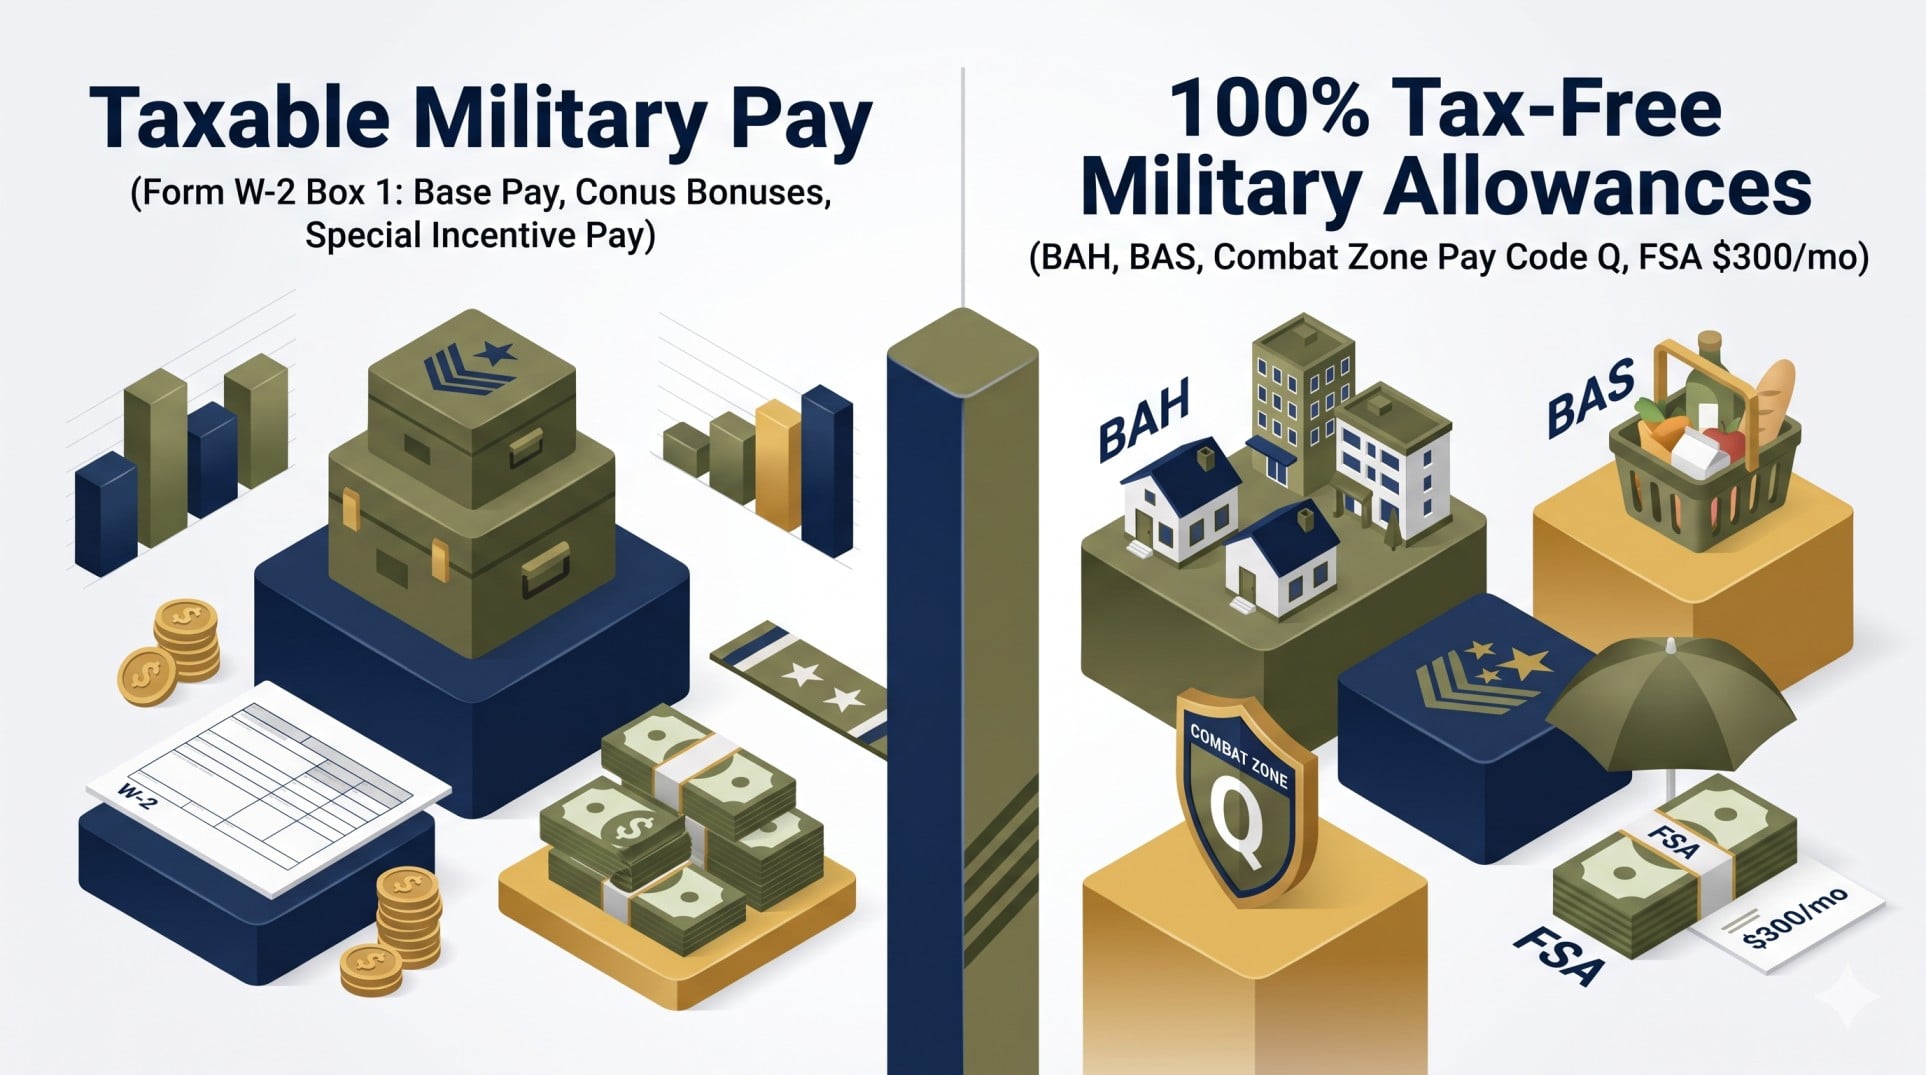
Taxable Military Compensation (Included in Form W-2, Box 1)
Unless earned during a qualifying month in a designated combat zone, the following items are fully subject to federal income tax and the 7.65% FICA payroll tax (6.2% Social Security up to the 2026 wage base of $184,500, plus 1.45% Medicare):
- Active Duty and Reserve Basic Pay: Monthly base compensation for active duty, drill weekends, and annual training.
- Special and Incentive Pays: Aviation career incentive pay (flight pay), submarine duty pay, hazardous duty incentive pay (parachute/demolition), medical/dental officer special pay, and foreign language proficiency pay.
- Enlistment and Reenlistment Bonuses: Lump-sum and installment bonuses signed outside a designated combat zone.
- Armed Forces Health Professions Scholarship Program (AFHPSP) Stipends: Living stipends paid to medical students, though tuition and fee payments remain tax-exempt under OBBBA permanent extensions.
Tax-Free Military Allowances (Excluded Under IRC Section 134)
Congress codified IRC Section 134 to prevent “qualified military benefits” from being taxed. None of the following allowances are subject to federal income tax, state income tax, or FICA payroll tax:
- Basic Allowance for Housing (BAH) and Overseas Housing Allowance (OHA): Completely tax-free whether you live off-base in a rental or own a primary residence.
- Basic Allowance for Subsistence (BAS): Tax-free monthly food allowance for officers and enlisted personnel.
- Family Separation Allowance (FSA): Paid at $300 per month in 2026 when dependents cannot accompany a service member on deployment, shipboard duty, or unaccompanied tours exceeding 30 days.
- Clothing, Dislocation, and Per Diem Allowances: Initial clothing allowances, annual uniform upkeep allowances, Dislocation Allowance (DLA), and Temporary Lodging Expense (TLE) reimbursements.
Homeowner “Double Dip” Rule (IRC Section 265(a)(6)): Just like ordained clergy, active duty service members who use tax-free BAH to pay their home mortgage and real estate property taxes can still deduct 100% of that qualified mortgage interest and property tax on Schedule A if they itemize. With the 2026 State and Local Tax (SALT) deduction cap set at $40,400 under the OBBBA, high-cost-of-living duty stations in California, Virginia, or Washington state often allow military homeowners to exceed the $32,200 joint standard deduction.
Combat Pay Exclusion and 2026 Tax Benefits for Active Duty Military
Among all 2026 tax benefits for active duty military, the Combat Zone Tax Exclusion (CZTE) under IRC Section 112 is the most financially impactful, exempting 100% of enlisted combat pay and up to $11,391.90 per month of commissioned officer pay from federal income tax.
To trigger the CZTE, a service member must perform official duties in an area designated by Presidential Executive Order as a Combat Zone (such as the Arabian Peninsula Areas, Kosovo, or the Sinai Peninsula) or a Qualified Hazardous Duty Area (QHDA) designated by Congress, or serve in direct certified support of military operations in a combat zone while receiving Hostile Fire Pay (HFP) or Imminent Danger Pay (IDP).
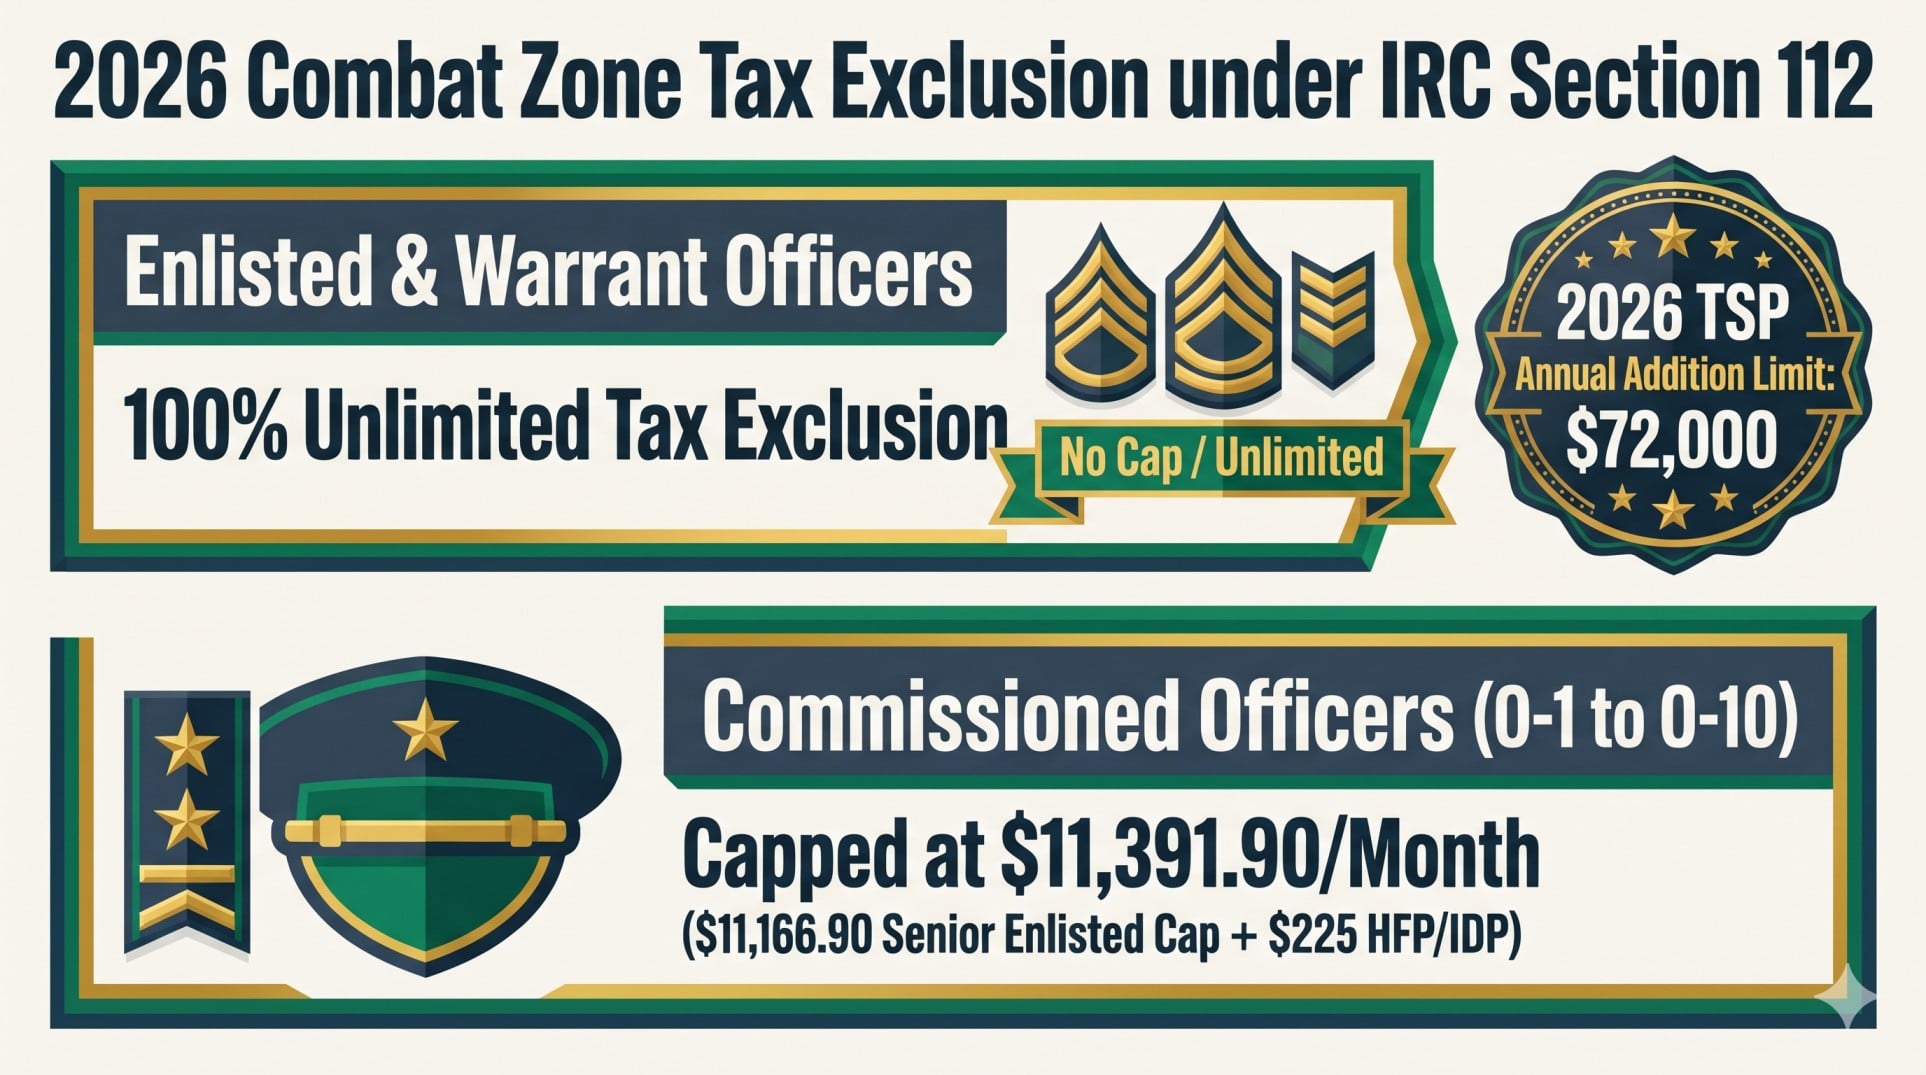
The One-Day Rule and 2026 Officer Cap
Under Treasury Regulation Section 1.112-1, the Combat Zone Tax Exclusion operates on a monthly all-or-nothing trigger known as the One-Day Rule. If you step foot in a designated combat zone on official orders for even a single hour on the 31st day of a month, your qualifying military pay for that entire calendar month is exempt from federal income tax. Note that while combat pay is exempt from federal (and almost all state) income taxes, it remains 100% subject to 6.2% Social Security and 1.45% Medicare taxes.
- Enlisted Members and Warrant Officers (E-1 to E-9 and W-1 to W-5): The exclusion is unlimited. Every dollar of basic pay, HFP/IDP, and special pay earned during a qualifying month is excluded from Box 1 of Form W-2 and reported instead in Box 12 with Code Q.
- Commissioned Officers (O-1 to O-10): Under IRC Section 112(b), a commissioned officer’s monthly income tax exclusion is capped at the highest rate of enlisted basic pay payable to the senior enlisted advisor of a military branch (Sergeant Major of the Army/Marine Corps, Master Chief Petty Officer of the Navy, or Chief Master Sergeant of the Air Force/Space Force), plus the monthly amount of HFP or IDP received by the officer. For calendar year 2026, senior enlisted E-9 basic pay is $11,166.90 per month and full HFP/IDP is $225.00 per month, creating a combined 2026 officer exclusion ceiling of $11,391.90 per month. Any officer basic pay exceeding $11,391.90 in a month remains taxable in W-2 Box 1.
- Reenlistment Bonuses and Leave Sales: If an enlisted member or officer signs a reenlistment contract or sells back accrued leave during a month in which they qualify for CZTE, the entire reenlistment bonus (including future installment payments) and leave payout is exempt from federal income tax.
The EITC Special Combat Pay Election (IRC Section 32(c)(2)(B)(vi))
Because nontaxable combat pay (W-2 Box 12, Code Q) is excluded from gross income, a lengthy deployment can reduce a family’s taxable earned income to near zero—inadvertently disqualifying them from the refundable Earned Income Tax Credit (EITC) or reducing the refundable Additional Child Tax Credit (ACTC).
To prevent this penalty, IRC Section 32(c)(2)(B)(vi) allows service members to make an annual election on Form 1040, Line 1i to include their nontaxable combat pay in earned income solely for calculating the EITC (and for determining earned income thresholds on Schedule 8812). Making this election does not make the combat pay taxable; your income tax remains $0 on that pay while unlocking a 2026 EITC refund of up to $8,231 (for families with three or more qualifying children), $7,316 (two children), or $4,427 (one child). You must include all or none of your nontaxable combat pay when making the election. Check our detailed 2026 Earned Income Tax Credit and Child Tax Credit guide to see how phase-out ranges work.
Stacking Combat Pay with the $72,000 TSP Limit and Roth IRAs
Under the HERO Act (IRC Section 219(f)(7)), nontaxable combat pay counts as eligible compensation for funding a Traditional or Roth Individual Retirement Arrangement (IRA). For 2026, a deployed service member (and a non-working spouse via a Spousal IRA) can each contribute up to $7,500 (or $8,600 if age 50 or older) to a Roth IRA, meaning the money goes in tax-free from Code Q combat pay and grows 100% tax-free for life.
Inside the federal Thrift Savings Plan (TSP), the 2026 employee elective deferral limit under IRC Section 402(g) is $24,500 (plus an $8,000 catch-up for ages 50–59 and 64+, or $11,250 for ages 60–63). However, when deployed to a combat zone, contributions made from tax-exempt combat pay into a Traditional TSP account do not count against the $24,500 elective deferral cap. Instead, they fall under the IRC Section 415(c) Annual Additions Limit, which rises to $72,000 for 2026 (up from $70,000 in 2025).
| Military Tax Provision / Threshold | Tax Year 2025 (Filed in 2026) | Tax Year 2026 (Filed in 2027) | Key IRS Rule / Post-OBBBA Impact |
|---|---|---|---|
| Standard Deduction (Single / MFJ / HOH) | $15,750 / $31,500 / $23,625 | $16,100 / $32,200 / $24,150 | Made permanent and inflation-adjusted by OBBBA / Rev. Proc. 2025-32 |
| Commissioned Officer Combat Zone Cap | $10,803.60 / month | $11,391.90 / month | Equals 2026 Senior Enlisted E-9 pay ($11,166.90) + $225 HFP/IDP |
| PCS Moving Mileage Rate (Form 3903) | 21.0 cents / mile (all year) | 20.5¢/mi (Jan–Jun) / 23.5¢/mi (Jul–Dec) | Rare mid-year IRS fuel adjustment effective July 1, 2026 |
| TSP Elective Deferral Limit (IRC § 402(g)) | $23,500 | $24,500 | Applies to combined Roth TSP + Traditional TSP from taxable pay |
| TSP Combat Zone Annual Addition Limit (§ 415(c)) | $70,000 | $72,000 | Maximum total TSP additions (employee + 5% BRS match + combat pay) |
| IRA / Roth IRA Contribution Limit | $7,000 ($8,000 age 50+) | $7,500 ($8,600 age 50+) | Tax-free Code Q combat pay qualifies as earned income for Roth IRA |
| Child Tax Credit (CTC) & Refundable ACTC | $2,200 ($1,700 refundable) | $2,200 ($1,700 refundable) | OBBBA permanently locked in the $2,200 credit per qualifying child |
| Maximum Earned Income Tax Credit (3+ Kids) | $8,046 | $8,231 | Service members can elect to include Code Q pay on Form 1040 Line 1i |
Scenario 1: Deployed E-6 Staff Sergeant Using the EITC Combat Pay Election (2026 Math)
Let’s trace the math for Staff Sergeant (E-6) Marcus and his spouse Elena, who file Married Filing Jointly for Tax Year 2026 and have two young children under age 6. Elena is a stay-at-home parent with $0 income. Marcus earns $54,000 in total military pay during 2026 (plus $24,000 in tax-free BAH and BAS). Because Marcus was deployed to a designated combat zone in the Arabian Peninsula from January through September 2026 (9 months), $40,500 of his pay is excluded as nontaxable combat pay (reported on Form W-2, Box 12, Code Q), leaving only $13,500 of taxable pay in Form W-2, Box 1.
- Step 1 (Federal Income Tax Liability): Marcus and Elena report $13,500 on Form 1040, Line 1a. After subtracting the 2026 Married Filing Jointly standard deduction of $32,200, their 2026 federal taxable income is $0, and their regular income tax is $0.
- Step 2 (Evaluating EITC Without the Election): Under IRS Revenue Procedure 2025-32, the 2026 EITC for a family with two qualifying children reaches its maximum plateau of $7,316 when earned income is at least $18,290 (and before phase-out begins at $30,470 for MFJ). With only $13,500 in W-2 Box 1 taxable earned income, Marcus and Elena fall short of the maximum credit plateau and would receive a reduced EITC of $5,400 (40% phase-in rate × $13,500).
- Step 3 (Evaluating EITC With the Line 1i Election): If Marcus elects to include all $40,500 of his Code Q combat pay on Form 1040, Line 1i, their total earned income for EITC purposes rises to $54,000 ($13,500 + $40,500). Because $54,000 is near the top of the 2026 MFJ two-child phase-out range (which phases out at 21.06% above $30,470, hitting $0 around $65,209), adding the full $40,500 would shrink their EITC down to $2,361. Therefore, Marcus leaves Line 1i blank for EITC purposes and keeps the higher $5,400 credit based on his $13,500 Box 1 wages!
- Step 4 (Calculating the Refundable Additional Child Tax Credit on Schedule 8812): For the Child Tax Credit ($2,200 × 2 children = $4,400), the refundable ACTC equals 15% of earned income above the $2,500 statutory threshold, up to $1,700 per child ($3,400 maximum refundable for two children). Notice the rule on Schedule 8812: unlike the EITC, nontaxable combat pay is automatically included in earned income when calculating the ACTC threshold! With $54,000 in total earned income ($54,000 – $2,500 = $51,500 × 15% = $7,725), Marcus easily qualifies for the full $3,400 refundable ACTC.
- Step 5 (Total 2026 Tax Refund): Marcus and Elena pay $0 in federal income tax and receive a combined tax-free refund of $8,800 ($5,400 EITC + $3,400 ACTC), plus a 100% refund of any federal income tax withheld during the three months he was stateside.
Deducting PCS Moving Expenses on Form 3903 in 2026
Under IRC Section 217(g), active duty members of the U.S. Armed Forces who relocate pursuant to a military order and incident to a permanent change of station (PCS) can claim an above-the-line deduction for unreimbursed moving expenses on IRS Form 3903.
While the Tax Cuts and Jobs Act originally suspended civilian moving deductions from 2018 through 2025, the One Big Beautiful Bill Act (OBBBA) signed in July 2025 made that repeal permanent for civilian employees and self-employed workers. Active duty service members (along with a narrow statutory carve-out for certain intelligence community employees) remain the only taxpayers in America allowed to exclude government moving reimbursements from income and deduct out-of-pocket PCS expenses on Schedule 1 (Form 1040), Line 14.
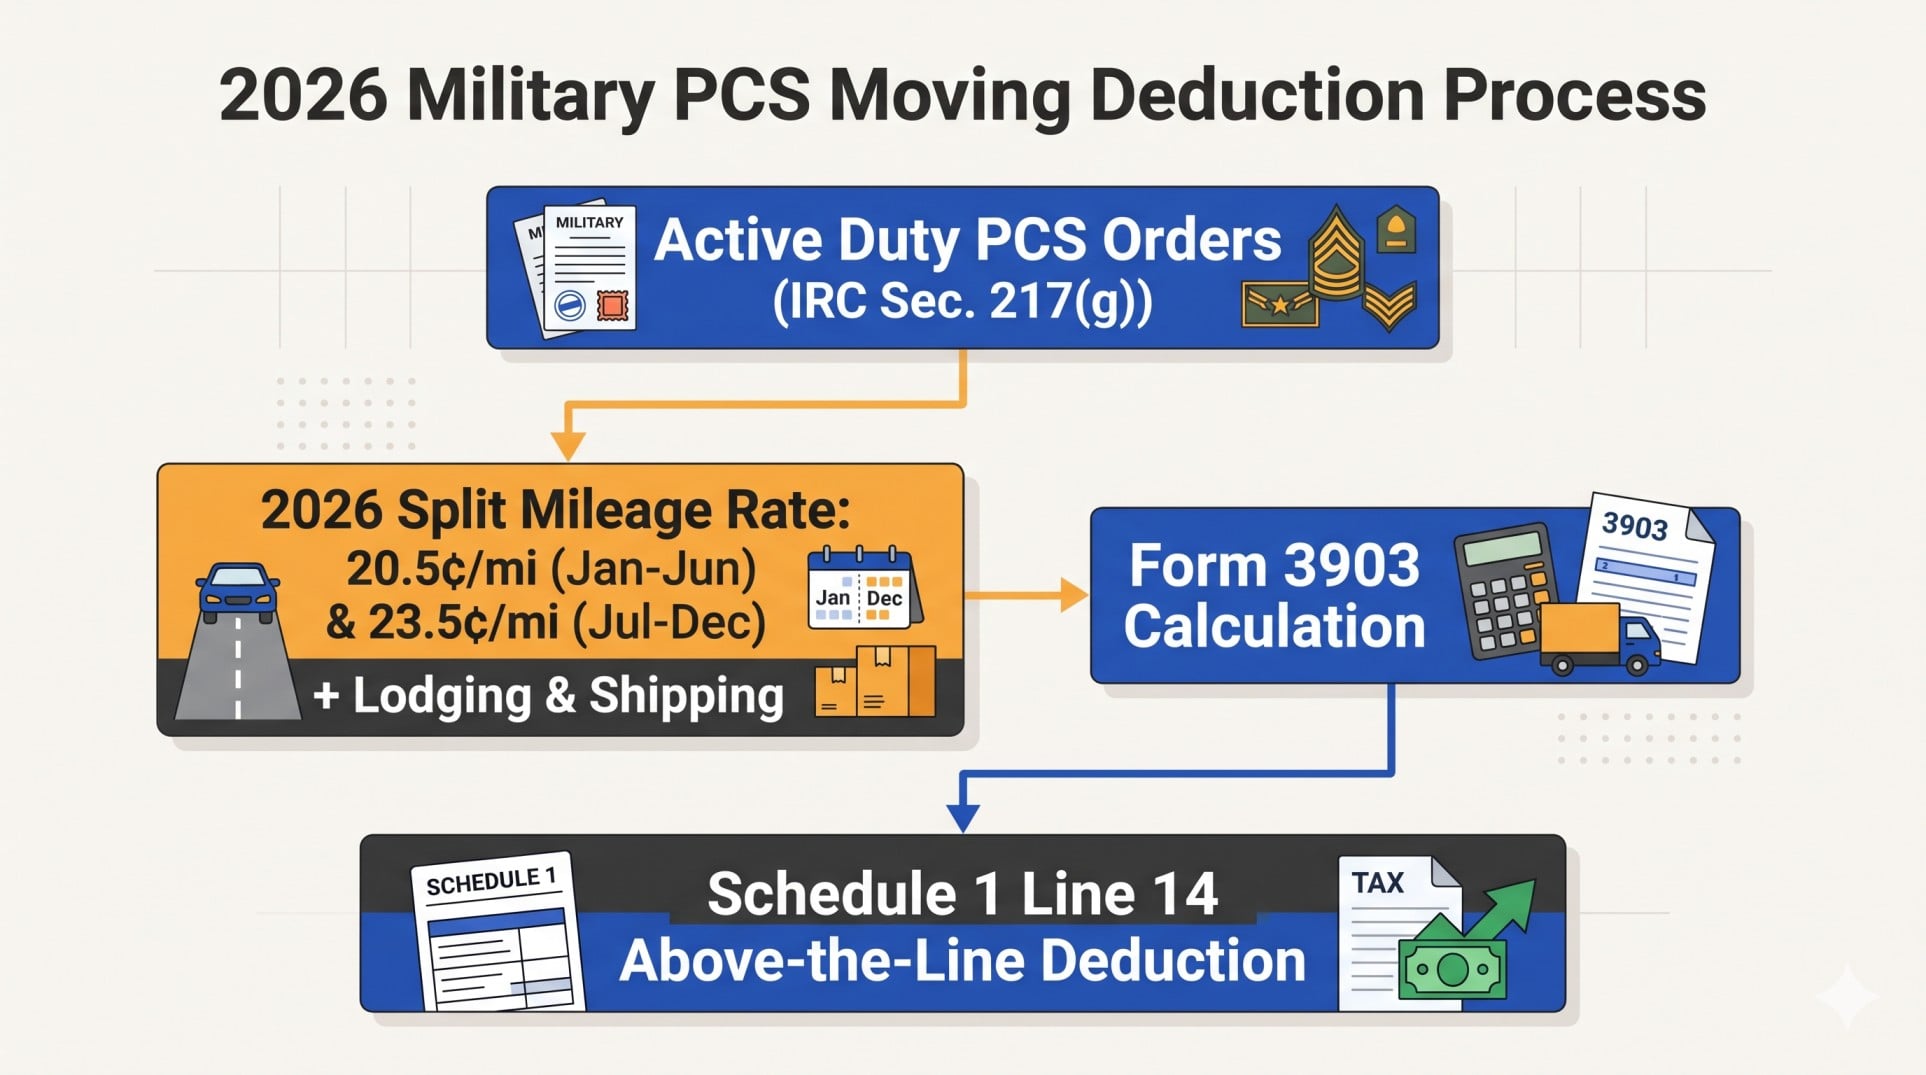
What Counts as a Qualifying PCS Move?
According to IRS Publication 3, active duty military members can claim Form 3903 without meeting any civilian distance or time-worked tests. Three types of military relocations qualify as a PCS:
- A move from your home of record or initial enlistment place to your first post of active duty.
- A move from one permanent duty station to another permanent duty station.
- A move from your last post of duty to your home of record (or to a nearer point in the United States) upon retirement, separation, or discharge, provided the move occurs within one year of ending active duty or within the period allowed under the Joint Travel Regulations (JTR).
The Split 2026 IRS Moving Mileage Rates (Crucial Mid-Year Update)
Because of fuel price volatility in 2026, the IRS took the rare step of issuing two separate standard mileage rates for calendar year 2026. When calculating vehicle expenses on Form 3903, Line 2, you must apply the exact rate in effect on the date your family drove the miles:
- January 1, 2026 through June 30, 2026: 20.5 cents per mile ($0.205) per vehicle driven, plus actual highway tolls and parking fees.
- July 1, 2026 through December 31, 2026: 23.5 cents per mile ($0.235) per vehicle driven, plus actual highway tolls and parking fees.
Alternatively, you may deduct actual out-of-pocket gas and oil expenses (supported by receipts), though you can never deduct depreciation, insurance, or general maintenance repairs on a personal vehicle used in a move. Check our 2026 IRS standard mileage rate breakdown for complete documentation rules.
Deductible vs. Non-Deductible PCS Costs and PPM (DITY) Moves
You can only deduct expenses on Form 3903 that exceed the non-taxable reimbursements and allowances (such as Monetary Allowance in Lieu of Transportation [MALT] and Per Diem) provided by the military:
- Deductible on Form 3903: Commercial moving company charges, rental trucks and trailers, packing boxes and tape, crating, in-transit insurance, shipping pets or personal automobiles, utility disconnection/connection fees related to appliances, up to 30 consecutive days of domestic in-transit storage (or unlimited foreign storage during an OCONUS tour), lodging en route for you and your household members, and vehicle mileage.
- Strictly Non-Deductible: Meals and food en route (meals are permanently disallowed on Form 3903), house-hunting trips prior to the PCS, temporary living expenses after arriving at the new station, security deposits, lease cancellation penalties, vehicle registration/licensing fees at the new state, and home purchase closing costs.
How Personally Procured Moves (PPM / DITY) Are Taxed: When you execute a Personally Procured Move (PPM), the military pays you an incentive equal to 100% of what it would have cost the government to hire a commercial mover. DFAS subtracts your documented moving operating expenses (truck rental, packing supplies, moving pads, and weight scale tickets) and reports the remaining net profit as taxable wages on a separate Travel W-2. Keep every receipt from your PPM—any valid moving expense that you forgot to submit to the military finance office can still be claimed on Form 3903 when you file your 2026 return in 2027.
National Guard and Reserve 100-Mile Travel Deduction
Members of the National Guard and Reserve components who travel more than 100 miles away from home and stay overnight to perform drill or reserve duties can claim an above-the-line deduction for unreimbursed travel, lodging, and 50% of meal expenses on Form 2106, flowing directly to Schedule 1 (Form 1040), Line 12. The deduction is capped at the federal per diem rate for that locality, and mileage is calculated using the 2026 business mileage rate of 72.5 cents per mile (Jan–Jun 2026) and 76.0 cents per mile (Jul–Dec 2026).
Scenario 2: O-3 Captain Executing a Cross-Country PCS Move in July 2026
Consider Captain Sarah, an active duty Army officer (O-3) who receives PCS orders to relocate her household from Fort Liberty, North Carolina, to Joint Base Lewis-McChord, Washington (2,800 miles) in July 2026. The government ships her primary household goods directly via a government bill of lading, but Sarah and her husband drive their two personal vehicles across the country and ship extra fragile heirlooms and their family dog out of pocket.
- Total Qualifying Out-of-Pocket Expenses:
- Driving two vehicles 2,800 miles each in July 2026 (5,600 total miles × $0.235/mile second-half 2026 rate): $1,316
- Highway tolls and hotel parking en route: $144
- 6 nights of hotel lodging en route for the family (excluding all restaurant meals): $1,680
- Out-of-pocket pet transport and overflow crating/shipping: $1,460
- Total Eligible PCS Costs: $4,600
- Subtract Government Reimbursements (Form 3903, Line 4): DFAS pays Sarah a non-taxable MALT and travel lodging reimbursement totaling $2,750 (Note: her Dislocation Allowance [DLA] is a separate tax-free allowance under IRC Section 134 and does not reduce Form 3903 moving expenses unless designated by finance directly for travel/shipping).
- Net Form 3903 Deduction: Sarah enters $1,460 on Form 3903 Line 1 (transportation/storage of goods) and $3,140 on Line 2 (travel and lodging: $1,316 mileage + $144 tolls + $1,680 hotels), totaling $4,600 on Line 3. Subtracting the $2,750 government reimbursement on Line 4 leaves an unreimbursed net moving deduction of $1,850 on Line 5.
- Tax Savings on Form 1040: Sarah transfers the $1,850 directly to Schedule 1, Line 14. Because this is an above-the-line adjustment, it reduces her Adjusted Gross Income (AGI) by $1,850 even though she and her husband claim the $32,200 standard deduction. In the 22% marginal tax bracket, filing Form 3903 saves her $407 in federal income tax.
SCRA State Tax Rules for Service Members and Military Spouses
Under the federal Servicemembers Civil Relief Act (SCRA), active duty service members and their accompanying spouses do not lose or acquire state tax domicile solely by complying with military PCS orders, allowing couples to choose the most favorable of three statutory state residency options under state tax rules.
Without federal protection, moving to a new duty station every three years would force military families to pay income taxes in high-tax states simply because the Pentagon stationed them there. Title 50 U.S.C. Section 4001 blocks host duty states from taxing active duty military pay—and blocks host states from taxing a military spouse’s civilian W-2 or self-employment income—when the couple maintains domicile elsewhere.
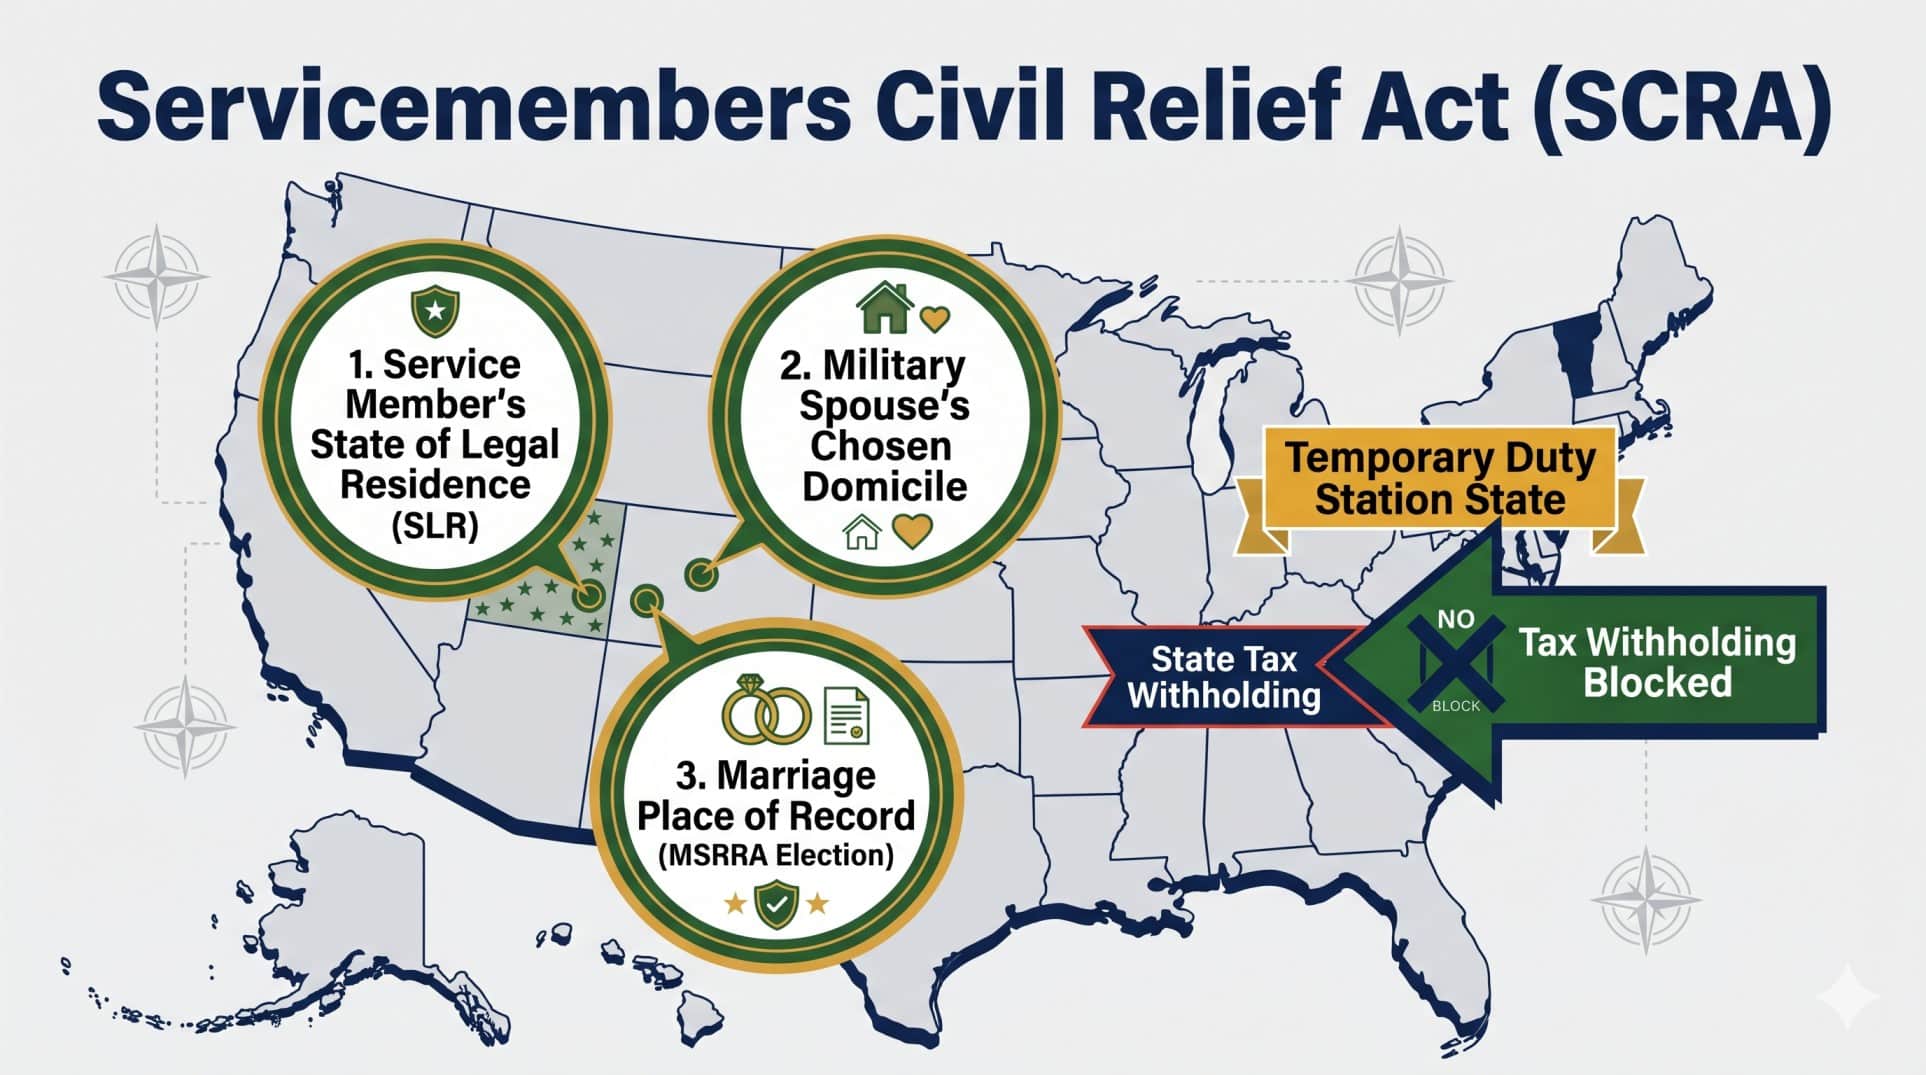
The Three SCRA / MSRRA State Residency Elections
Following the Military Spouses Residency Relief Act (MSRRA), the Veterans Benefits and Transition Act of 2018, and the Veterans Auto and Education Improvement Act (codified at 50 U.S.C. § 4001(a)(3)), an active duty service member and their spouse may elect, for any taxable year of the marriage, to use any of the following three states for state income tax filing, regardless of the date on which they were married:
- The Residence or Domicile of the Service Member: The service member’s official State of Legal Residence (SLR) on file with DFAS via DD Form 2058.
- The Residence or Domicile of the Spouse: The state where the civilian spouse established legal domicile prior to relocating on PCS orders.
- The Permanent Duty Station (PDS) of the Service Member: The state where the service member is currently stationed under PCS orders.
Here is why this matters financially: nine states impose 0% state income tax on earned wages in 2026 (Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming). If an Air Force pilot establishes legitimate legal domicile in Texas or Florida during flight training (by registering to vote, getting a driver’s license, registering vehicles, and filing DD Form 2058), and later marries a civilian nurse while stationed in Virginia or California, both the pilot’s military pay and the spouse’s civilian nursing salary in California can be legally exempt from California state income tax by electing the service member’s Texas/Florida residency!
| Income Source / Tax Scenario | Taxable in Legal Domicile State (SLR)? | Taxable in Host Duty Station State (PDS)? | Action Required by Military Family |
|---|---|---|---|
| Active Duty Military Pay (W-2) | Depends on SLR state rules (Many exempt out-of-state active pay) | No — 100% Exempt under SCRA | Maintain valid DD Form 2058 with DFAS payroll |
| Military Spouse W-2 Wages at Duty Station | Yes (0% if SLR is a no-income-tax state like TX, FL, WA) | No — 100% Exempt under SCRA / MSRRA | File state withholding exemption certificate with civilian employer (e.g., CA Form DE 4, VA Form VA-4) |
| Service Member Off-Duty Second Job (Civilian W-2 / Uber) | Yes (Subject to resident credit for taxes paid to host state) | Yes — Taxable in Host State | SCRA only protects military pay for the service member; file non-resident return in host state for side job |
| Real Estate Rental Income / Property Sale | Yes (Credit given for host state tax) | Yes — Taxed Where Property Is Physically Located | Report rental income on Schedule E and file non-resident state return where rental sits |
| Military Retirement Pay (DoD Pension) | Exempt in ~38+ States (Fully or partially taxed in only a few, e.g., CA, VT) | N/A (Retirees are taxed only by their actual state of residence) | Adjust state tax withholding inside myPay upon retirement |
| VA Disability Compensation & CRSC | No — 100% Exempt in All 50 States | No — 100% Exempt in All 50 States | No state or federal reporting required |
Important Trap: Off-Duty Civilian Jobs for the Service Member
Never confuse the rules for the service member with the rules for the spouse. While the SCRA exempts a military spouse’s civilian wages earned at the duty station state, it does not exempt civilian wages earned by the service member from an off-duty moonlighting job. If a Navy petty officer with Florida residency takes a weekend bartending or consulting job off-base while stationed in San Diego, California, those civilian bartending wages are 100% subject to California non-resident state income tax.
Furthermore, several states that have a personal income tax—such as New York, Pennsylvania, Ohio, and Missouri—grant a special exemption to their own domiciliaries: if you are a legal resident of one of those states, maintain no permanent home inside that state, maintain a home outside that state, and spend 30 days or fewer in your home state during 2026, your active duty military pay is exempt from your home state’s income tax as well. See our state residency and non-resident tax filing guide for state-by-state domicile rules.
2026 Tax Benefits for Veterans and Disabled Retirees
Under IRC Section 104(a)(4) and Title 38 U.S.C. Section 5301, all benefits administered by the Department of Veterans Affairs (VA) are 100% excluded from federal and state gross income, providing permanent tax relief for disabled **veterans** and their families.
Unlike regular military retirement longevity pensions (which are reported on Form 1099-R and taxed as ordinary federal income, though exempt from FICA payroll tax), disability-based payments from the VA never enter your Adjusted Gross Income. Understanding the distinction between DoD retirement pay, VA disability, and concurrent receipt programs is essential for retirees in 2026.
Tax-Free Veteran Benefits vs. Taxable DoD Retirement
- 100% Tax-Free VA Benefits: Monthly VA disability compensation, Dependency and Indemnity Compensation (DIC) paid to surviving spouses, VA Pension payments, GI Bill tuition payments and Monthly Housing Allowances (MHA), Veteran Readiness and Employment (VR&E) subsistence stipends, grants for specially adapted housing or adaptive vehicles, and Veterans’ Group Life Insurance (VGLI) dividends and proceeds.
- Combat-Related Special Compensation (CRSC) vs. Concurrent Retirement and Disability Pay (CRDP): Military retirees with a 50% or higher VA disability rating generally qualify for CRDP, which restores the DoD retired pay offset without a separate application; however, CRDP is 100% taxable as regular retired pay. Conversely, CRSC (awarded for disabilities directly attributable to combat, hazardous duty, or instrumentality of war) is 100% tax-exempt under IRC Section 104(a)(4).
- DoD Medical Disability Retirement: Under IRC Section 104(b), DoD disability retired pay is only tax-free if the disability was a direct result of a combat-related injury (or if the member was in the military on September 24, 1975). Otherwise, DoD medical retirement is taxable to the extent it exceeds the VA disability offset.
The Strickland Retroactive VA Rating Refund (Form 1040-X)
When a military retiree applies for VA disability compensation, the VA often takes months or years to adjudicate the claim. Once approved, the VA assigns a retroactive effective date (typically the date the claim or Intent to File was submitted). Under Revenue Ruling 78-161 (commonly called the Strickland decision), a retiree who does not qualify for full CRDP must waive a dollar of taxable DoD retired pay for every dollar of tax-free VA disability compensation received.
Because DFAS already issued a Form 1099-R for the prior tax year showing the full DoD pension as taxable, the veteran can file Form 1040-X (Amended U.S. Individual Income Tax Return) for each open tax year covered by the retroactive VA award letter to reclassify that portion of DoD retired pay as tax-exempt! You do not need a corrected Form 1099-R from DFAS to claim this refund; instead, attach a copy of your official VA Rating Decision letter and the DFAS retroactive computation audit sheet to Form 1040-X.
Be mindful of the statute of limitations under IRC Section 6511: you must file Form 1040-X within three years from the date you filed the original tax return (or within two years from the date you paid the tax, whichever is later). Furthermore, under the Combat-Injured Veterans Tax Fairness Act of 2016, veterans who had federal income taxes improperly withheld from DoD disability severance pay have an extended window—one year from the date of their DoD notification letter—to claim a refund.
State Property Tax Exemptions for Disabled Veterans
Beyond income taxes, virtually all 50 states offer substantial real estate property tax exemptions for veterans with service-connected disabilities. More than 20 states—including Texas, Florida, Virginia, Maryland, Michigan, Illinois, and Oklahoma—grant a 100% complete property tax exemption on a primary residence for veterans rated 100% Permanent and Total (P&T) (or Individual Unemployability [TDIU]) by the VA. Because property tax exemptions are administered by county tax assessors rather than the IRS, veterans must submit their VA Benefit Summary Letter to their local county appraisal office before the annual state deadline.
Scenario 3: Retired E-8 Master Sergeant Filing a Strickland Retroactive Refund Plus 2026 Taxes
Let’s look at Master Sergeant (Ret.) Thomas, age 46, a single filer living in Georgia. Thomas retired from the Army in January 2025 with 20 years of service and a 40% VA disability rating (below the 50% threshold required for CRDP, meaning his DoD pension is subject to a dollar-for-dollar VA waiver). In 2025, DFAS paid him $36,000 in taxable DoD retirement pay, and he also earned $50,000 at a civilian defense contractor job (placing him firmly in the 22% federal marginal tax bracket).
In August 2025, Thomas filed a claim for a worsened service-connected condition. On March 15, 2026, the VA issued an official decision increasing his rating from 40% to 40% + additional combined ratings that raised his monthly tax-free VA award by $600 per month, retroactive to September 1, 2025.
- Amending Tax Year 2025 via Form 1040-X: Because the retroactive effective date covered four months of 2025 (September through December 2025), $2,400 ($600 × 4 months) of the taxable DoD pension reported on his 2025 Form 1099-R is retroactively reclassified as tax-exempt VA disability under Revenue Ruling 78-161. Thomas files Form 1040-X for 2025, reducing his 2025 Adjusted Gross Income by $2,400 and receiving a federal tax refund of $528 ($2,400 × 22% marginal bracket), plus a state tax refund from Georgia.
- Filing Tax Year 2026 Return (in 2027): Because the VA did not issue the rating letter until March 2026, DFAS continued paying his unadjusted taxable pension during January and February 2026 before updating his Form 1099-R for the rest of the year. When Thomas files his 2026 Form 1040 in April 2027, he reduces the taxable pension amount on Form 1040, Line 5b by $1,200 ($600 × 2 months for Jan–Feb 2026), attaching his VA rating decision statement to substantiate the Strickland exclusion, saving another $264 in 2026 federal tax.
Step-by-Step Guide to Filing Your 2026 Military Tax Return in 2027
To file your 2026 military tax return accurately by April 15, 2027, gather your DFAS Form W-2 (or Form 1099-R), verify Box 12 Code Q combat exclusions, attach Form 3903 for unreimbursed PCS moves, and apply automatic combat zone deadline extensions under IRC Section 7508 if deployed.
Active duty personnel and eligible family members have free access to commercial tax preparation software and military tax consultants through Defense Department **MilTax** (via Military OneSource) and on-base **Volunteer Income Tax Assistance (VITA)** offices trained specifically on IRS Publication 3 mechanics. Follow this five-step checklist when preparing your return.
Step 1: Download Your DFAS Tax Statements via myPay
In mid-to-late January 2027, log into your DFAS myPay portal to retrieve all 2026 tax documents:
- Active Duty & Reserve Form W-2: Check Box 1 for taxable military wages, Box 12 Code Q for nontaxable combat pay, and Box 15 for your listed State of Legal Residence (SLR).
- Travel / PCS Form W-2: If you completed a Personally Procured Move (PPM/DITY) or received taxable travel reimbursements in 2026, DFAS issues a separate W-2. Do not file your return until you have downloaded both W-2s!
- Retiree Form 1099-R: Military retirees receive Form 1099-R showing gross taxable retired pay in Box 1 and Box 2a.
Step 2: Complete Form 3903 and Form 2106 on Schedule 1
If you executed a PCS move in 2026 and your out-of-pocket shipping, lodging, and mileage costs (at 20.5¢/mile for Jan–Jun or 23.5¢/mile for Jul–Dec) exceeded your military travel reimbursement, complete Form 3903 and carry the deduction to Schedule 1 (Form 1040), Line 14. If you had two separate PCS moves in 2026, prepare a separate Form 3903 for each move and combine them on Schedule 1. National Guard and Reserve members traveling over 100 miles for drill complete Form 2106 and carry the deduction to Schedule 1, Line 12.
Step 3: Test the Combat Pay Election on Form 1040, Line 1i
If Box 12 of your W-2 contains a Code Q amount and your family qualifies for the Earned Income Tax Credit (EITC), run your tax software calculation twice: once with the Code Q amount entered on Form 1040, Line 1i, and once with Line 1i left at $0. Select whichever option produces the larger refund on Form 1040, Line 27. Ensure your Code Q combat pay is included on Schedule 8812 when calculating the refundable Additional Child Tax Credit.
Step 4: Claim Automatic Extensions if Overseas or Deployed
If you cannot file by the standard April 15, 2027 deadline due to military duty, two automatic extensions protect you from late-filing penalties:
- Stationed Outside the U.S. and Puerto Rico (Non-Combat): Service members on tour outside the United States and Puerto Rico on April 15, 2027, receive an automatic two-month extension to June 15, 2027 to file their return (though interest on any unpaid tax still accrues from April 15). You can request an additional four-month extension to October 15, 2027 by filing Form 4868 before June 15.
- Combat Zone / Contingency Operation Extension (IRC Section 7508): If you serve in a designated combat zone or qualifying contingency operation, your deadline to file your 2026 return, pay taxes owed, and make a 2026 IRA contribution is automatically extended for 180 days after your last day in the combat zone (or last day of continuous hospitalization from a combat injury), plus the number of days that remained before the April 15 filing deadline when you entered the zone. During this extension period, the IRS charges 0% interest and $0 penalties. To alert the IRS before deploying, you or your spouse can email your deployment orders to `combatzone@irs.gov`.
Step 5: File State Non-Resident Refund Returns for Spouse Withholding
If a civilian employer at your temporary duty station mistakenly withheld host-state income tax from a military spouse’s W-2 wages in 2026, file a non-resident state tax return in that host state claiming $0 in state-source taxable income under the SCRA/MSRRA to recover 100% of the withheld state taxes, and attach a copy of the service member’s PCS orders, military ID, and DD Form 2058.
Frequently Asked Questions About Military Taxes in 2026
1. Are BAH and BAS taxable on a 2026 military tax return?
No, Basic Allowance for Housing (BAH) and Basic Allowance for Subsistence (BAS) are 100% excluded from federal and state gross income under IRC Section 134. DFAS automatically omits these allowances from Box 1 of your Form W-2, and you do not report them as income on Form 1040.
2. What is the commissioned officer combat zone tax exclusion cap for 2026?
For Tax Year 2026, the maximum monthly Combat Zone Tax Exclusion for a commissioned officer (grades O-1 through O-10) is $11,391.90 per month. Per IRC Section 112(b), this figure equals the 2026 senior enlisted E-9 basic pay cap ($11,166.90) plus $225.00 in monthly Hostile Fire or Imminent Danger Pay.
3. Can active duty military still deduct moving expenses in 2026 after the OBBBA?
Yes, active duty service members relocating under military PCS orders remain eligible to deduct unreimbursed moving expenses on IRS Form 3903 in 2026. While the One Big Beautiful Bill Act permanently eliminated moving deductions for civilians, Congress preserved the active duty military exception under IRC Section 217(g).
4. What is the 2026 IRS mileage rate for a military PCS move?
The IRS instituted two separate moving mileage rates for 2026 due to a mid-year fuel adjustment. For PCS travel driven between January 1 and June 30, 2026, the deductible rate is 20.5 cents per mile; for PCS travel driven between July 1 and December 31, 2026, the rate is 23.5 cents per mile.
5. Is VA disability compensation taxable at the federal or state level?
No, disability compensation paid by the Department of Veterans Affairs (VA) is 100% tax-free at both the federal and state levels under IRC Section 104(a)(4) and 38 U.S.C. Section 5301. You never receive a Form 1099-R for VA disability benefits, and you should never include them on Form 1040.
6. Can a military spouse claim the service member’s state of legal residence for taxes?
Yes, under federal Servicemembers Civil Relief Act (SCRA) amendments (50 U.S.C. § 4001), a military spouse accompanying an active duty member on PCS orders can elect to use the service member’s State of Legal Residence (SLR), the spouse’s own domicile, or the current permanent duty station state for state tax purposes.
7. Does tax-free combat pay count as earned income for a Roth IRA in 2026?
Yes, under the HERO Act (IRC Section 219(f)(7)), nontaxable combat pay reported in Box 12 (Code Q) of Form W-2 counts as eligible earned compensation for IRA contributions. In 2026, a deployed service member can contribute up to $7,500 ($8,600 if age 50+) of tax-free combat pay into a Roth IRA.
8. How are military Death Gratuity and SGLI payments taxed?
The $100,000 military Death Gratuity and up to $500,000 in Servicemembers’ Group Life Insurance (SGLI) proceeds paid to survivors of a deceased service member are 100% exempt from federal and state income tax. Furthermore, under the HEART Act (IRC Section 408A(e)(2)), survivors can roll these payments directly into a Roth IRA within one year of receipt, ignoring normal annual contribution caps.
9. Can I deduct meals while driving to my new duty station on a PCS move?
No, out-of-pocket meal and food expenses incurred while traveling to a new permanent duty station are never deductible on IRS Form 3903. Only unreimbursed lodging, vehicle mileage (or actual gas/oil), tolls, parking, and household goods shipping costs qualify for the PCS moving expense deduction.
10. What happens if I sell my primary home early because of PCS orders?
Under IRC Section 121(d)(9), active duty military members on qualified official extended duty (stationed 50+ miles away or in government quarters for 90+ days) can suspend the normal 5-year ownership-and-use lookback period for up to 10 years. This allows you to live in the home for just 2 out of 15 years and still exclude up to $250,000 ($500,000 Married Filing Jointly) of capital gains when selling the property.
Final Year-End Tax Planning Steps for Service Members
Securing all available 2026 tax benefits for active duty military and veterans starts with auditing your Leave and Earnings Statement (LES) before December 31, 2026. Verify that your State of Legal Residence (SLR) is accurately recorded on DD Form 2058, confirm that any combat zone months properly stopped federal tax withholding, and organize your weight tickets and lodging receipts if you executed a PCS move during the year.
When tax filing season opens in January 2027, take time to test the EITC combat pay election on Form 1040, Line 1i and reconcile both your regular W-2 and any separate Travel W-2 inside DFAS myPay. By combining statutory military exclusions under IRC Sections 112, 134, and 217(g) with the expanded post-OBBBA standard deduction and child tax credits, service members and veterans can keep every dollar Congress intended in their family’s pocket.
Disclaimer: This content provides general information for educational purposes only and reflects federal tax laws applicable to Tax Year 2026 (returns filed in 2027). Tax laws are complex and subject to change. This article does not constitute professional tax, legal, or accounting advice. Always consult a certified public accountant (CPA), enrolled agent (EA), or qualified tax attorney regarding your specific financial situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.
