
If you drove for business, medical care, a qualifying military move, or charity work in 2026, one figure decides your write-off — and this year it’s not a single number. The IRS mileage rate 2026 started at 72.5 cents per business mile in January, then jumped to 76 cents per mile on July 1 after a rare mid-year adjustment. This guide breaks down every rate by date and purpose, walks through the math with real numbers, and flags what changed under new tax law.
If you’re self-employed or run a small business, the worked examples and Schedule C guidance below apply directly to you. If you’re a W-2 employee, skip ahead to the Federal vs. State section — current federal law blocks this deduction for most employees, though a few states still allow it.
⚡ Executive Summary: IRS Mileage Rate 2026
- For the 2026 tax year, the business mileage rate is 72.5 cents per mile from January 1 through June 30, then 76 cents per mile from July 1 through December 31.
- The medical and qualifying moving mileage rate is 20.5 cents per mile for the first half of 2026 and 23.5 cents per mile for the second half.
- The charitable mileage rate is fixed by statute at 14 cents per mile for the entire 2026 tax year — the IRS cannot adjust it.
- The maximum standard automobile cost for employer FAVR reimbursement plans is $61,700 for 2026.
Table of Contents
- IRS Mileage Rate 2026: The Numbers at a Glance
- Why the Rate Changed Mid-Year
- How to Calculate Your Mileage Deduction
- Four Worked Examples Using the 2026 Rates
- Ways to Get the Most From the Standard Mileage Method
- Common Mistakes and IRS Red Flags
- Federal vs. State Treatment
- Recent Law Changes
- When to Get Professional Help
- Frequently Asked Questions
- Sources Consulted
IRS Mileage Rate 2026: The Numbers at a Glance
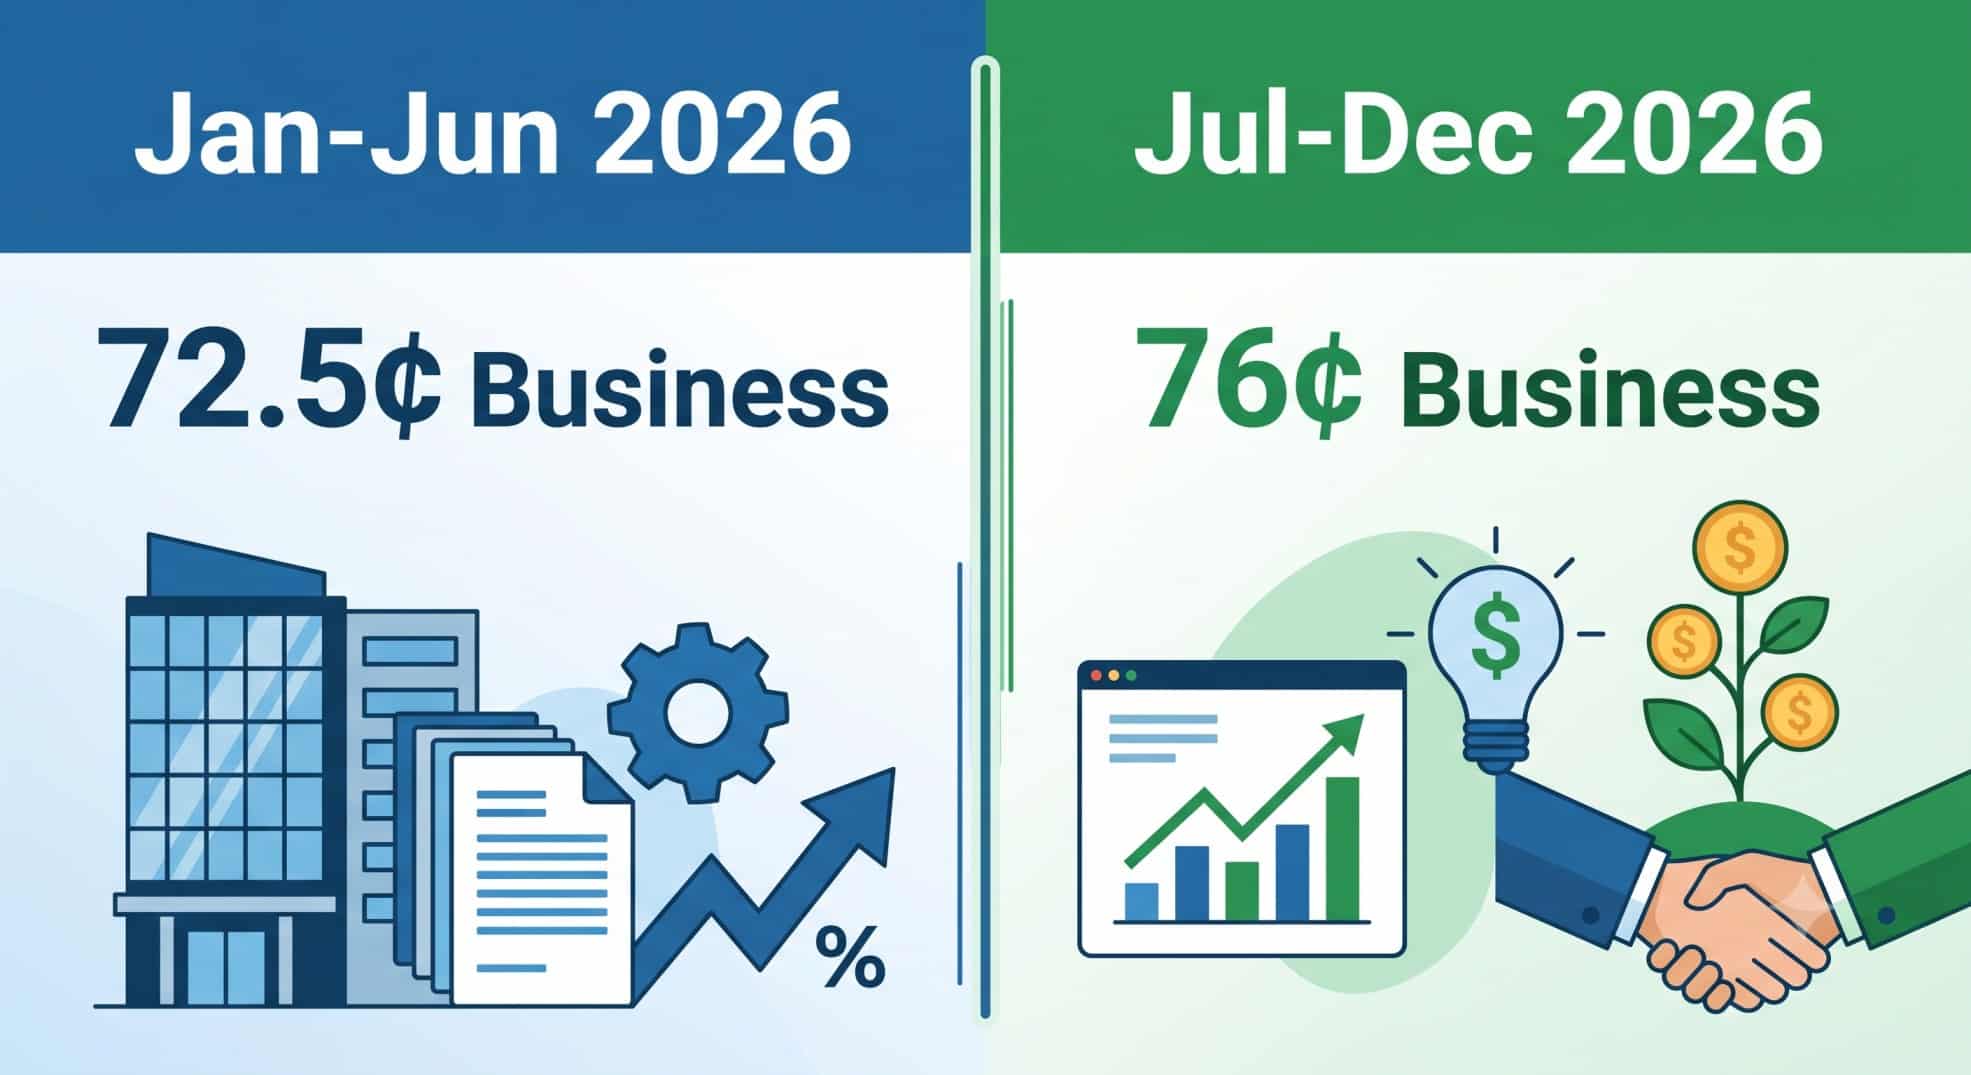
The IRS mileage rate 2026 applies differently depending on the date you drove and the purpose of the trip. Because of a mid-year adjustment, you’ll need two rates instead of one for business, medical, and moving miles. Only the charitable rate stayed the same all year.
| Purpose | Jan 1 – Jun 30, 2026 | Jul 1 – Dec 31, 2026 |
|---|---|---|
| Business | 72.5 cents/mile | 76 cents/mile |
| Medical care | 20.5 cents/mile | 23.5 cents/mile |
| Qualifying military/intelligence-community moving | 20.5 cents/mile | 23.5 cents/mile |
| Charitable service | 14 cents/mile | 14 cents/mile |
Beginning January 1, 2026, the rates were 72.5 cents per mile for business, 20.5 cents per mile for medical purposes, 20.5 cents per mile for qualifying moving purposes, and 14 cents per mile for charitable service, under Notice 2026-10, establishing the optional standard mileage rates for computing the deductible costs of operating an automobile for business, charitable, medical, or moving expense purposes effective January 1, 2026. Then, mid-year, the revised standard mileage rates, effective July 1, are: 76 cents per mile for business, an increase from 72.5 cents, and 23.5 cents per mile for medical and moving purposes, up from 20.5 cents per mile for each. The charitable rate never moved, because the mileage rate that applies to the deduction for charitable contributions is fixed under Sec. 170(i) of the Internal Revenue Code at 14 cents per mile.
Two more figures matter if you’re a business owner or an employer running a reimbursement plan. The portion of the business standard mileage rate treated as depreciation for purposes of calculating reductions to basis is 35 cents per mile for 2026, up 2 cents from 2025. And for purposes of computing the allowance under a fixed and variable rate (FAVR) plan, the standard automobile cost may not exceed $61,700 for automobiles, including trucks and vans, for 2026.
Does this rate apply to electric or hybrid vehicles?
Yes. The rates apply to fully-electric and hybrid automobiles, as well as gasoline and diesel-powered vehicles. The IRS does not publish a separate mileage rate for EVs.
Is using the standard mileage rate mandatory?
Use of the standard mileage rates is optional. Taxpayers may instead choose to calculate the actual costs of using their vehicle, tracking gas, insurance, repairs, and depreciation directly. The standard rate is simpler; the actual-expense method sometimes produces a bigger deduction for high-cost or heavily used vehicles.
Why the Rate Changed Mid-Year
A mid-year mileage rate change is unusual — the IRS normally sets one rate per calendar year in December. The IRS normally updates the mileage rate once a year, with mid-year changes occurring only in rare circumstances, and the last midyear adjustment of the standard mileage rate was in 2022, before this one.
The trigger was fuel cost movement. Citing the increase in the cost of fuel, the IRS set a higher optional standard mileage rate for the remainder of 2026, through Announcement 2026-11, which modified Notice 2026-10. Gas prices back this up: the American Automobile Association reported that the average price for regular gasoline was $2.819 a gallon on Jan. 8, and $3.890 on July 15, an increase of 38%.
What if I only drove in one half of the year?
Then only one rate applies to you — 72.5 cents for business miles driven January through June, or 76 cents for miles driven July through December. The split only matters if your driving spans both periods, which is common for anyone driving regularly all year.
Does the mid-year change affect the depreciation and FAVR figures?
Announcement 2026-11 addressed only the per-mile rates themselves. All other provisions of Notice 2026-10 remain in effect, which means the 35-cents-per-mile depreciation component and the $61,700 FAVR ceiling described above continue to apply for the full 2026 tax year.
For a full walkthrough of the alternative approach, see our guide on choosing between the standard mileage rate and the actual expense method.
How to Calculate Your Mileage Deduction
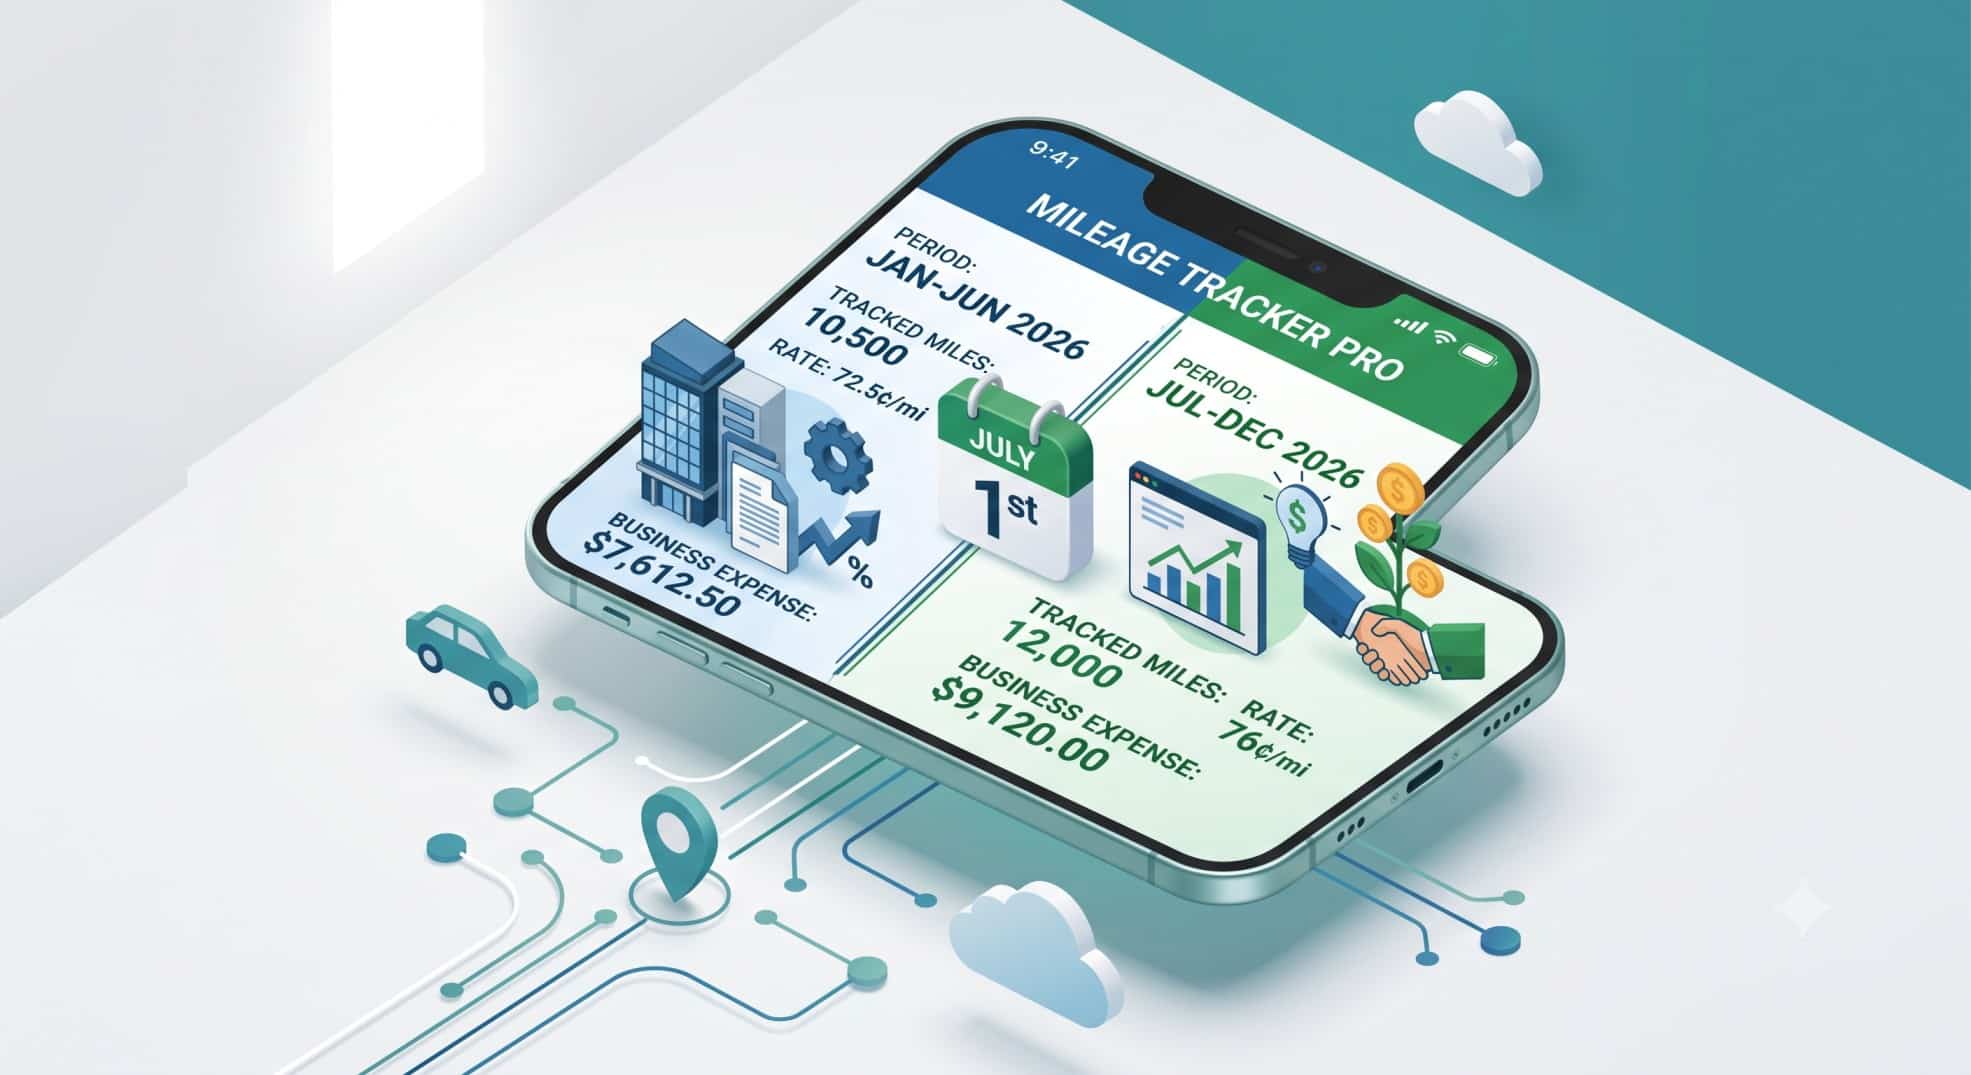
Calculating your 2026 deduction takes four steps once you know your total mileage log is split by date. Follow this order every time you have driving that spans the July 1 rate change.
- Separate your mileage log by period. Total your business (or medical, moving, charitable) miles driven from January 1 through June 30, then total the miles driven from July 1 through December 31.
- Apply the correct rate to each period. Multiply your January–June business miles by 72.5 cents, and your July–December business miles by 76 cents.
- Add the two results together. This combined figure is your total standard mileage deduction for the year.
- Report it on the correct form and line. Self-employed filers enter vehicle expenses on Schedule C, Part II, Line 9. Landlords use Schedule E, Part I, Line 6. Farmers use Schedule F.
What if I use my car for more than one purpose?
If you use your car for more than one purpose, you’ll want to keep appropriate records and deduct the cost of personal travel separately, and you may also use more than one rate on your return — for example, business miles at the business rate and a separate trip to a medical appointment at the medical rate. Commuting between home and your regular workplace never counts, regardless of purpose.
Do I have to choose the standard rate in the first year I use a vehicle?
Yes. Taxpayers using the standard mileage rate for a vehicle they own and use for business must choose to use the rate in the first year the automobile is available for business use. In later years, they can elect to use the standard mileage rate or actual expenses. For a leased vehicle, the rule is stricter: taxpayers using the standard mileage rate must employ that method for the entire lease period, including renewals.
Four Worked Examples Using the 2026 Rates
These four scenarios show how the split rate plays out for different taxpayers. Each assumes no other adjustments unless stated, and each rounds only at the final total.
| Period | Miles | Rate | Subtotal |
|---|---|---|---|
| Jan 1 – Jun 30 | 6,000 | 72.5 cents | $4,350.00 |
| Jul 1 – Dec 31 | 6,000 | 76 cents | $4,560.00 |
| Total Schedule C deduction | 12,000 | — | $8,910.00 |
This consultant reports the full $8,910 on Schedule C, Part II, Line 9, as a vehicle expense, alongside her other business deductions.
| Period | Miles | Rate | Subtotal |
|---|---|---|---|
| Jan 1 – Jun 30 | 800 | 72.5 cents | $580.00 |
| Jul 1 – Dec 31 | 800 | 76 cents | $608.00 |
| Total Schedule E deduction | 1,600 | — | $1,188.00 |
The landlord reports $1,188 on Schedule E, Part I, Line 6, for trips to inspect, maintain, or show the rental units. Commuting-style drives to a personal residence don’t count.
| Period | Miles | Rate | Subtotal |
|---|---|---|---|
| Jan 1 – Jun 30 | 1,200 | 20.5 cents | $246.00 |
| Jul 1 – Dec 31 | 1,200 | 23.5 cents | $282.00 |
| Total medical mileage | 2,400 | — | $528.00 |
This $528 gets added to the retiree’s other unreimbursed medical expenses on Schedule A. It only produces a benefit once total medical expenses exceed the 7.5% adjusted-gross-income floor and the taxpayer itemizes rather than takes the standard deduction.
Worked example 4: W-2 employee, not reimbursed, 5,000 work miles in 2026. Under current federal law, this employee’s mileage produces a $0 federal deduction, no matter which rate applies, unless they fall into a narrow exception discussed in the next section. This is the scenario that trips up the most taxpayers, because the old pre-2018 rules still circulate online.
Ways to Get the Most From the Standard Mileage Method
A few habits make a real difference in what you can legitimately claim under the 2026 rates.
- Log every trip contemporaneously. Note the date, destination, purpose, and odometer reading close to the time of the trip rather than reconstructing it in April.
- Split your log at June 30. Since the rate changed mid-year, a log that already separates miles by period saves time and reduces math errors at filing.
- Track multi-purpose trips separately. If one drive covers both a client meeting and a personal errand, only the business portion counts.
- Compare against actual expenses in high-cost years. If you bought new tires, had major repairs, or your insurance jumped, run the numbers both ways before committing to the standard rate for that vehicle.
- Don’t forget parking and tolls. These are deductible in addition to the standard mileage rate, not folded into it.
For more on reporting vehicle costs correctly, see our article on completing Schedule C Part II vehicle expenses.
Common Mistakes and IRS Red Flags
Preparers see the same handful of mileage errors every filing season, and the 2026 mid-year change adds a new one to the list.
- Using one rate for the whole year. Applying 72.5 cents to July–December miles, or 76 cents to January–June miles, understates or overstates the deduction and is the single most common IRS mileage rate 2026 error this year.
- Claiming commuting miles. Regular drives from home to a fixed workplace are never deductible, no matter the rate.
- No contemporaneous log. Estimated mileage reconstructed after the fact is a frequent audit trigger.
- Switching methods incorrectly. Using actual expenses (including accelerated depreciation) in the first year, then trying to switch to the standard rate later, isn’t permitted for an owned vehicle.
- Claiming employee mileage on Schedule A. Most W-2 employees can no longer deduct unreimbursed mileage federally at all — see the next section.
Federal vs. State Treatment
Federal and state rules on mileage deductions diverge sharply for W-2 employees, so don’t assume your state follows the same rule as your federal return.
Federal treatment: Taxpayers cannot claim a miscellaneous itemized deduction for unreimbursed employee travel expenses, except for certain educator expenses. However, deductions for expenses that are deductible in determining adjusted gross income remain allowable, such as for certain members of a reserve component of the Armed Forces, certain state and local government officials, certain performing artists, and eligible educators. Outside those narrow categories, an ordinary W-2 employee gets no federal mileage deduction at all in 2026, even using the correct IRS mileage rate 2026 figures.
State treatment: States generally fall into three groups: those with no state income tax (the issue doesn’t arise), those that follow the federal disallowance, and a smaller group of states reported to have decoupled from it. A handful of states — including California, New York, Pennsylvania, and Minnesota — are reported to still permit employees to deduct unreimbursed vehicle expenses on the state return even though the federal deduction is gone. Confirm the current rule for your state directly with your state Department of Revenue before relying on it, since state conformity rules change independently of federal law and vary by year.
What about self-employed taxpayers — does state treatment differ for them?
Self-employed vehicle deductions generally flow through to state returns the same way federal Schedule C income does, since most states start their calculation from federal adjusted gross income or federal taxable income. Confirm this with your state’s specific business income tax instructions, since a few states require separate adjustments.
Recent Law Changes
The One, Big, Beautiful Bill Act reshaped two pieces of the mileage picture that were previously temporary. First, it made the employee mileage deduction disallowance permanent rather than a sunset provision — the TCJA suspended this deduction and the One Big Beautiful Bill Act permanently eliminated the deduction by amending IRC § 67(g) to remove its scheduled expiration date. Second, it widened who can use the moving-mileage rate: the optional standard mileage rate may be used to calculate the deductible costs of operating vehicles for moving purposes for certain active-duty members of the Armed Forces, and now, under the One, Big, Beautiful Bill, certain members of the intelligence community. Beyond these two items, no other 2026 legislation has altered how the standard mileage rates themselves are calculated or reported.
When to Get Professional Help
Most taxpayers can apply the 2026 rates and file without assistance. But a few situations raise the stakes enough to justify a licensed CPA or Enrolled Agent: you drive across multiple states for work and need to sort out conflicting state conformity rules, you’re designing a FAVR reimbursement plan as an employer, you fall into one of the narrow federal exceptions (reservist, fee-basis official, performing artist, or educator) and need to document eligibility correctly, or you received an IRS notice questioning your mileage substantiation. In any of these cases, a professional can confirm the current rules apply to your specific facts before you file or amend. For background on record requirements, see our guide on what counts as an IRS-compliant mileage log.
Frequently Asked Questions
What is the IRS mileage rate for 2026?
The IRS mileage rate 2026 is 72.5 cents per business mile from January 1 through June 30, then 76 cents per mile from July 1 through December 31. Medical and qualifying moving mileage is 20.5 cents, rising to 23.5 cents on July 1. Charitable mileage stays at 14 cents all year.
Did the mileage rate change in the middle of 2026?
Yes. The IRS issued a mid-year adjustment effective July 1, 2026, raising the business rate from 72.5 to 76 cents and the medical/moving rate from 20.5 to 23.5 cents, citing rising fuel and vehicle operating costs.
Can W-2 employees still deduct mileage in 2026?
Generally, no. Federal law permanently disallows the unreimbursed employee mileage deduction, with narrow exceptions for reservists, certain fee-basis government officials, performing artists, and eligible educators. Some states still allow it on the state return — confirm with your state Department of Revenue.
What’s the medical mileage rate for 2026?
It’s 20.5 cents per mile from January through June and 23.5 cents per mile from July through December, added to your other unreimbursed medical expenses on Schedule A, subject to the 7.5% AGI floor.
Is the charitable mileage rate ever adjusted for inflation?
No. The charitable mileage rate is set by Congress in the tax code, not by the IRS through an annual cost study, so it doesn’t move with fuel prices the way the business rate does.
Do electric and hybrid vehicles qualify for the standard mileage rate?
Yes. The standard mileage rates apply equally to gasoline, diesel, hybrid, and fully electric vehicles. There’s no separate IRS mileage rate for EVs.
What if I used my car for both business and personal driving?
Only the business-purpose miles count toward your deduction. Keep a log that separates business trips from personal ones, and apply the mileage rate only to the business portion.
How do I substantiate my mileage if I’m audited?
Keep a contemporaneous log showing the date, starting and ending odometer readings or total miles, destination, and business purpose of each trip. Records created after the fact are far more likely to be questioned.
Sources Consulted
- IRS Newsroom, “IRS sets 2026 business standard mileage rate at 72.5 cents per mile, up 2.5 cents” (IR-2025-128, Dec. 29, 2025)
- IRS Notice 2026-10, Standard Mileage Rates for 2026
- IRS Announcement 2026-11 / Internal Revenue Bulletin 2026-29 (mid-year rate adjustment, effective July 1, 2026)
- IRS, “The standard mileage rates and maximum automobile fair market values have been updated for 2026”
- IRS, Standard Mileage Rates page (Tax Professionals)
- Journal of Accountancy, “Business standard mileage rate increases for 2026” and “IRS raises standard mileage rates for remainder of 2026”
- American Automobile Association, national average gasoline price data (as cited by Journal of Accountancy)
Disclaimer: This content provides general information for educational purposes only. Tax laws are complex and change often. It is not professional tax, legal, or financial advice. Always consult a qualified tax professional for personalized guidance regarding your specific situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.
