
Transferring wealth to the next generation requires precision. If you simply write a massive check to your children or grandchildren without understanding the tax code, you risk triggering unnecessary IRS scrutiny and eating into your lifetime wealth transfer limits. The 2026 Annual Gift Tax Exclusion is the primary tool you will use to move money out of your taxable estate efficiently.
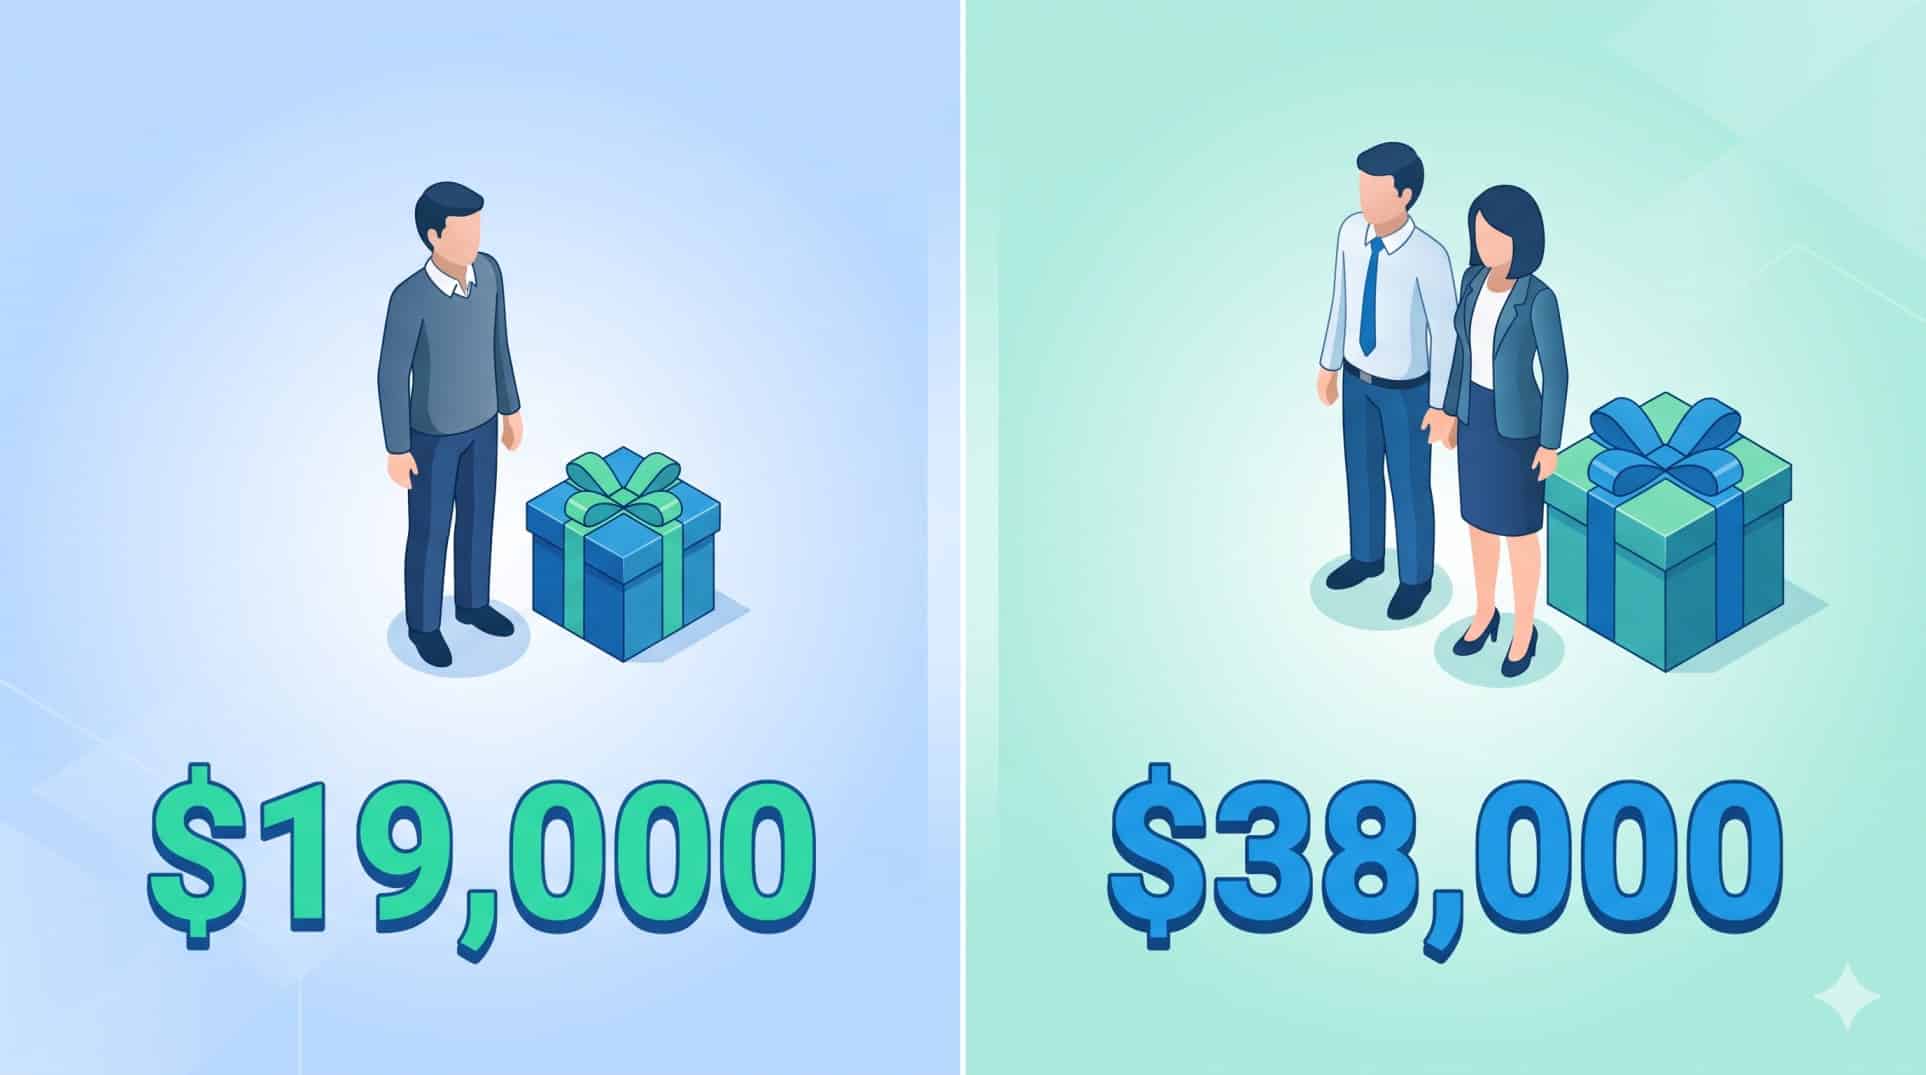
For the 2026 tax year, the IRS has set the annual exclusion limit at $19,000 per recipient. This is the baseline number that dictates whether you need to file extra paperwork or tap into your lifetime exemption. But the rules surrounding Gift Taxes are highly nuanced. Between gift splitting for married couples, unlimited exceptions for specific expenses, and the recent legislative changes that permanently altered the lifetime exemption, you need a concrete strategy.
This guide is A great companion to your estate planning posts. We will break down exactly How Much Can You Give Tax-Free, how to navigate IRS Form 709, and the specific strategies high-net-worth families use to fund education and medical care without ever paying a dime to the federal government. If you regularly read estate planning posts, you know that proactive gifting is the foundation of generational wealth preservation.
⚡ Executive Summary: 2026 Gifting Rules
- Annual Limit: The 2026 Annual Gift Tax Exclusion is $19,000 per recipient. You can give this amount to as many different people as you want.
- Married Couples: Through “gift splitting,” a married couple can give up to $38,000 per recipient in 2026 without triggering tax consequences.
- Lifetime Exemption: The One Big Beautiful Bill Act (OBBBA) prevented the 2026 sunset, permanently setting the lifetime estate and gift tax exemption at $15 million per individual ($30 million for couples).
- Unlimited Exceptions: Payments made directly to medical providers or educational institutions do not count toward your $19,000 annual limit.
Table of Contents
- The Core Rule: 2026 Annual Gift Tax Exclusion Explained
- Married Couples and Gift Splitting: Doubling Your Impact
- The $15 Million Lifetime Exemption: The OBBBA Impact
- Beyond the Limit: Unlimited Tax-Free Gifts for Medical and Tuition
- 529 Superfunding: The 5-Year Forward Election
- The Basis Trap: Gifting Cash vs. Appreciated Assets
- Step-by-Step Guide: Filing Form 709 and Reporting Gifts
- Frequently Asked Questions About Gift Taxes
The Core Rule: 2026 Annual Gift Tax Exclusion Explained
The federal government taxes the transfer of wealth. However, to prevent the IRS from having to track every birthday check or graduation present, the tax code includes a generous annual buffer. The 2026 Annual Gift Tax Exclusion allows you to give up to $19,000 to any individual over the course of the calendar year without reporting it to the IRS.
This limit applies on a per-recipient basis. You are not capped at giving $19,000 total for the year. You could give $19,000 to your son, $19,000 to your daughter, $19,000 to your neighbor, and $19,000 to a complete stranger. As long as no single individual receives more than $19,000 from you between January 1 and December 31, you do not have to file a gift tax return.
When people ask How Much Can You Give Tax-Free, they often confuse the annual exclusion with the lifetime exemption. The annual exclusion is simply your yearly reporting threshold. If you stay under it, the IRS does not need to know about the gift. If you go over it, you trigger a reporting requirement, but you still likely will not owe any actual taxes.
Married Couples and Gift Splitting: Doubling Your Impact
If you are married, your ability to transfer wealth doubles. The IRS allows married couples to combine their individual exclusions through a process called “gift splitting.”
Because each spouse has a $19,000 limit, a married couple can give up to $38,000 to a single recipient in 2026. You can achieve this by writing two separate $19,000 checks from individual accounts, or by writing one $38,000 check from a joint checking account. If you write a single check from a joint account, the IRS automatically assumes the gift is split evenly between both spouses.
However, if one spouse writes a $38,000 check from an account held solely in their name, you must file IRS Form 709 to officially elect gift splitting. Your spouse must sign the form consenting to apply their $19,000 exclusion to your gift. This administrative step is critical to avoid accidentally eating into your individual lifetime exemption.
Robert and Linda are married and want to help their three grandchildren buy their first homes. In 2026, they decide to maximize their gifting. Robert has a $19,000 limit per grandchild, and Linda has a $19,000 limit per grandchild. By utilizing gift splitting, they give each grandchild $38,000. Across three grandchildren, they successfully transfer $114,000 out of their taxable estate in a single year. Because they stayed exactly at the $38,000 combined limit per recipient, they owe zero Gift Taxes and do not reduce their lifetime exemption.
The $15 Million Lifetime Exemption: The OBBBA Impact
What happens if you give someone $50,000 in a single year? You have exceeded the 2026 Annual Gift Tax Exclusion by $31,000. Do you owe a massive tax bill? No. This is where the lifetime exemption comes into play.
For years, the estate planning community warned of a looming “sunset” in 2026 that would cut the lifetime exemption in half. The One Big Beautiful Bill Act (OBBBA), signed into law in July 2025, completely eliminated that threat. The OBBBA permanently set the federal estate and gift tax exemption at $15,000,000 per person ($30,000,000 for a married couple) starting in 2026, with inflation adjustments moving forward.
When you exceed the $19,000 annual limit, the excess amount simply subtracts from your $15 million lifetime bucket. You must file Form 709 to report the excess gift, but you will not pay a single penny in out-of-pocket Gift Taxes until you have given away more than $15 million over the course of your entire life.
This permanent $15 million threshold makes this guide A great companion to your estate planning posts. You no longer have to panic-gift assets to beat a legislative sunset. You can plan your wealth transfer strategically.
Beyond the Limit: Unlimited Tax-Free Gifts for Medical and Tuition
If you want to know How Much Can You Give Tax-Free, the answer is technically unlimited—if you pay for the right things. The IRS provides two massive loopholes that bypass both the annual exclusion and the lifetime exemption entirely.
1. The Educational Exclusion: You can pay unlimited amounts for someone’s tuition without it counting as a taxable gift. This applies to college, private high school, or even specialized training programs. However, it only covers tuition. It does not cover room and board, books, or supplies.
2. The Medical Exclusion: You can pay unlimited amounts for someone’s qualifying medical expenses, including hospital bills, surgeries, and health insurance premiums.
The golden rule for both of these exceptions is the direct payment mandate. You must write the check directly to the university or the hospital. If you give the cash to your grandson so he can pay his tuition bill, it is considered a standard gift and is subject to the $19,000 2026 Annual Gift Tax Exclusion. Never put the money in the recipient’s hands.
Sarah’s daughter requires an emergency surgery that costs $45,000 out-of-pocket. Sarah wants to cover the cost. If Sarah transfers $45,000 to her daughter’s checking account, she exceeds her $19,000 annual exclusion by $26,000, forcing her to file Form 709 and reduce her lifetime exemption. Instead, Sarah calls the hospital billing department and pays the $45,000 invoice directly. Because she paid the provider directly, the entire $45,000 is tax-free, does not require a tax return, and leaves her $19,000 annual exclusion completely untouched. She can still give her daughter a $19,000 cash gift later that year.
529 Superfunding: The 5-Year Forward Election
One of the most powerful strategies discussed in advanced estate planning posts is 529 plan superfunding. A 529 plan is a tax-advantaged investment account designed for education savings. Normally, contributions to a 529 plan are subject to the standard annual gift limits.
However, the IRS allows a special 5-year forward election. You can front-load five years’ worth of annual exclusions into a 529 plan in a single lump sum. For 2026, the math is simple: $19,000 multiplied by 5 equals $95,000. A married couple can double this, dropping $190,000 into a grandchild’s 529 plan on day one.
By superfunding the account, you allow the capital to compound tax-free for years before the child actually needs it for college. You must file Form 709 to elect this 5-year spread, and you cannot make any additional tax-free gifts to that specific beneficiary for the next five years. If you die before the five years are up, a prorated portion of the gift is pulled back into your taxable estate.
The Basis Trap: Gifting Cash vs. Appreciated Assets
When deciding How Much Can You Give Tax-Free, you must also consider *what* you are giving. Gifting cash is straightforward. Gifting appreciated assets—like real estate or stocks—introduces the basis trap.
When you give an asset while you are alive, the recipient assumes your original cost basis. If you bought stock for $10,000 decades ago and it is now worth $19,000, you can gift it under the 2026 Annual Gift Tax Exclusion. But when your child sells that stock, they will owe capital gains taxes on the $9,000 of growth.
Conversely, if you hold that stock until you die and pass it through your estate, the asset receives a “step-up in basis.” The cost basis resets to the fair market value on the day of your death. If your child inherits the stock at $19,000 and sells it the next day, they owe zero capital gains taxes. As a general rule, it is better to gift cash or slow-growing assets during your lifetime, and hold highly appreciated assets to pass through your estate.
David wants to give his son $19,000 in 2026. He decides to transfer shares of Apple stock that he originally purchased for $2,000. The gift falls perfectly under the 2026 Annual Gift Tax Exclusion, so no Gift Taxes are owed. However, the son inherits David’s $2,000 cost basis. When the son sells the stock for $19,000 to buy a car, he gets hit with a capital gains tax bill on the $17,000 profit. Had David simply given his son $19,000 in cash, the son would have owed nothing.
Step-by-Step Guide: Filing Form 709 and Reporting Gifts
If you exceed the $19,000 limit, or if you need to elect gift splitting or 529 superfunding, you must file IRS Form 709 (United States Gift and Generation-Skipping Transfer Tax Return). This form is due on April 15th of the year following the gift, the exact same deadline as your standard income tax return.
Step 1: Track All Gifts
Maintain a ledger of every transfer you make during the year. Include cash, property, forgiven loans, and below-market sales (e.g., selling a $300,000 house to your child for $100,000 is a $200,000 gift).
Step 2: Isolate the Exceptions
Remove any direct payments made for tuition or medical expenses from your ledger. These do not go on Form 709.
Step 3: Calculate the Excess
For every recipient, subtract the $19,000 2026 Annual Gift Tax Exclusion from the total amount given. The remaining balance is your taxable gift amount.
Step 4: Apply to Lifetime Exemption
On Form 709, you will report the excess amount. The form will walk you through the math of subtracting that excess from your $15 million lifetime exemption. You will not write a check to the IRS unless your lifetime bucket is completely empty.
Frequently Asked Questions About Gift Taxes
What is the 2026 Annual Gift Tax Exclusion limit?
The limit for 2026 is $19,000 per recipient. You can give this amount to an unlimited number of individuals without filing a tax return or paying any taxes.
How Much Can You Give Tax-Free over a lifetime?
Thanks to the OBBBA legislation, the lifetime estate and gift tax exemption is permanently set at $15 million per individual, or $30 million for a married couple, starting in 2026.
Do I have to pay taxes if I give someone $50,000?
No, assuming you have not exhausted your $15 million lifetime exemption. You will have to file Form 709 to report the $31,000 excess over the annual limit, but you will not pay out-of-pocket Gift Taxes.
What is gift splitting?
Gift splitting allows a married couple to combine their individual annual exclusions. In 2026, this means a couple can give up to $38,000 to a single recipient tax-free.
Are gifts to my spouse taxable?
No. The IRS provides an unlimited marital deduction. You can transfer an unlimited amount of assets to your U.S. citizen spouse during your lifetime or at death without triggering any taxes.
Does paying for my grandchild’s college count toward the limit?
Not if you pay the school directly. Direct tuition payments are completely exempt from gift tax limits. However, if you give the money to your grandchild to pay the bill, it counts toward your $19,000 limit.
What is 529 superfunding?
Superfunding allows you to front-load five years of annual exclusions into a 529 college savings plan at once. In 2026, an individual can contribute $95,000, and a married couple can contribute $190,000 to a single beneficiary’s account.
Do I need to file IRS Form 709?
You only need to file Form 709 if you give more than $19,000 to a single person in a year, if you are electing to split gifts with your spouse from a separate account, or if you are superfunding a 529 plan.
Are charitable donations considered gifts?
No. Donations to qualified 501(c)(3) charities are not subject to gift tax rules. They are charitable contributions, which may actually provide you with an income tax deduction.
What happens if I exceed my $15 million lifetime exemption?
If you manage to give away more than $15 million during your lifetime, any subsequent gifts will be subject to the federal gift tax. The top federal tax rate for these excess gifts is 40%.
Understanding the 2026 Annual Gift Tax Exclusion is the first step in mastering generational wealth transfer. By leveraging gift splitting, direct payment exceptions, and the permanent $15 million lifetime exemption, you can ensure your assets go to your family rather than the federal government. Keep this guide bookmarked as A great companion to your estate planning posts as you navigate the 2026 tax year.
Disclaimer: This content provides general information for educational purposes only. Tax laws are complex and change often. It is not professional tax, legal, or financial advice. Always consult a qualified tax professional for personalized guidance regarding your specific situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.
