
Renouncing US citizenship in 2026—or surrendering a long-held green card—is the only legal way to permanently end your obligation to file annual US federal tax returns on worldwide income. While the US Department of State slashed the administrative consular processing fee for a Certificate of Loss of Nationality (CLN) from $2,350 down to $450 effective April 13, 2026, the tax hurdles governed by Internal Revenue Code (IRC) Section 877A remain unforgiving. Before the IRS lets you walk away from the US tax system, it audits your net worth, your prior five years of tax liability, and your filing compliance history on Form 8854 to determine whether you owe a final departure levy known as the IRS exit tax.
Contrary to popular belief, most Americans living abroad who give up their passport pay zero exit tax. However, if you cross a single statutory threshold and become a covered expatriate, the IRS treats you as having sold every asset you own across the globe on the day before your expatriation date. Worse, a single paperwork mistake or an unfiled foreign information return from three years ago can trigger automatic covered status—turning a routine consular appointment into a six-figure tax bill when you file your final returns in 2027.
⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- 2026 Covered Expatriate Thresholds: Per IRS Revenue Procedure 2025-32, you are a covered expatriate if your net worth is $2,000,000 or more on your expatriation date, your 5-year average annual net US income tax liability for 2021–2025 exceeds $211,000, or you fail to certify 5 years of full federal tax compliance on Form 8854.
- $910,000 Mark-to-Market Exclusion: For expatriations occurring in calendar year 2026, the IRC Section 877A(a)(3) deemed-sale gain exclusion is $910,000 (up from $890,000 in 2025). This exclusion applies only to mark-to-market capital assets—never to IRAs, 401(k)s, foreign pensions, or trusts.
- Post-OBBBA Gifting & Section 2801 Rules: The One Big Beautiful Bill Act (OBBBA) permanently raised the unified federal estate and gift tax exemption to $15,000,000 for 2026, giving ultra-high-net-worth citizens unprecedented room to gift assets before expatriating. Conversely, future gifts or bequests made by a covered expatriate to US persons face a flat 40% tax under final IRC Section 2801 regulations (reported on Form 708).
- 2027 Dual-Status Filing Deadlines: If you expatriate in 2026, your final dual-status return (Form 1040 attached to Form 1040-NR) and initial Form 8854 are due by June 15, 2027, for taxpayers residing abroad, though any 2026 exit tax balance owed must be paid by April 15, 2027, to avoid interest.
Table of Contents
- ⚡ Executive Summary: Key 2026 Tax Rules at a Glance
- What Is the IRS Exit Tax (IRC Section 877A) in 2026?
- Who Pays the IRS Exit Tax? The 3 Covered Expatriate Tests for 2026
- Statutory Exceptions and IRS Relief Procedures for Former Citizens
- 2025 vs. 2026 Expatriation Thresholds and Asset Treatment Matrix
- How the Expatriation Tax 2026 Is Calculated (Mark-to-Market & $910,000 Exclusion)
- 4 Real-World 2026 Expatriation Scenarios (With Step-by-Step Math)
- Business Owners, Green Card Holders, and the Section 2801 Inheritance Trap
- Pre-Expatriation Tax Planning: Legal Ways to Avoid Covered Status in 2026
- Step-by-Step Guide: How to File Your Dual-Status Return and Form 8854 in 2027
- Frequently Asked Questions About Renouncing US Citizenship in 2026
- Final Checklist Before Scheduling Your 2026 Consular Appointment
What Is the IRS Exit Tax (IRC Section 877A) in 2026?
The IRS exit tax—formally titled the Expatriation Tax under IRC Section 877A—is a final federal income tax assessment imposed on certain wealthy or tax-noncompliant US citizens and long-term green card holders who formally terminate their US tax status. Enacted under the Heroes Earnings Assistance and Relief Tax (HEART) Act of 2008, the statute prevents individuals from accumulating tax-deferred wealth or unrealized capital gains inside the US tax net and then relocating to a low-tax foreign jurisdiction to cash out tax-free.
Section 877A only applies to two distinct groups of individuals who expatriate during calendar year 2026:
- US Citizens: Any individual who relinquishes US nationality by taking a formal oath of renunciation before a US diplomatic or consular officer abroad (8 U.S.C. Section 1481(a)(5)) or commits another statutory expatriating act with the intent to relinquish citizenship.
- Long-Term Lawful Permanent Residents (Green Card Holders): Any non-citizen who held a US green card in at least 8 of the last 15 taxable years ending with the year in which residency is terminated—either by filing USCIS Form I-407 (Record of Abandonment of Lawful Permanent Resident Status) or by electing to be treated as a tax resident of a foreign treaty country via IRS Form 8833.
Your exact “expatriation date” controls which calendar year’s inflation thresholds apply and sets the valuation date for your worldwide balance sheet. For US citizens renouncing at an embassy in 2026, your expatriation date is the exact day you sign the oath of renunciation in front of the consular officer—not the later date when the State Department approves and mails your Certificate of Loss of Nationality (Form DS-4083). Although the State Department published a final rule on March 13, 2026, lowering the administrative CLN fee from $2,350 to $450 (effective April 13, 2026), that consular fee reduction has zero effect on your tax obligations with the Internal Revenue Service.
Who Pays the IRS Exit Tax? The 3 Covered Expatriate Tests for 2026
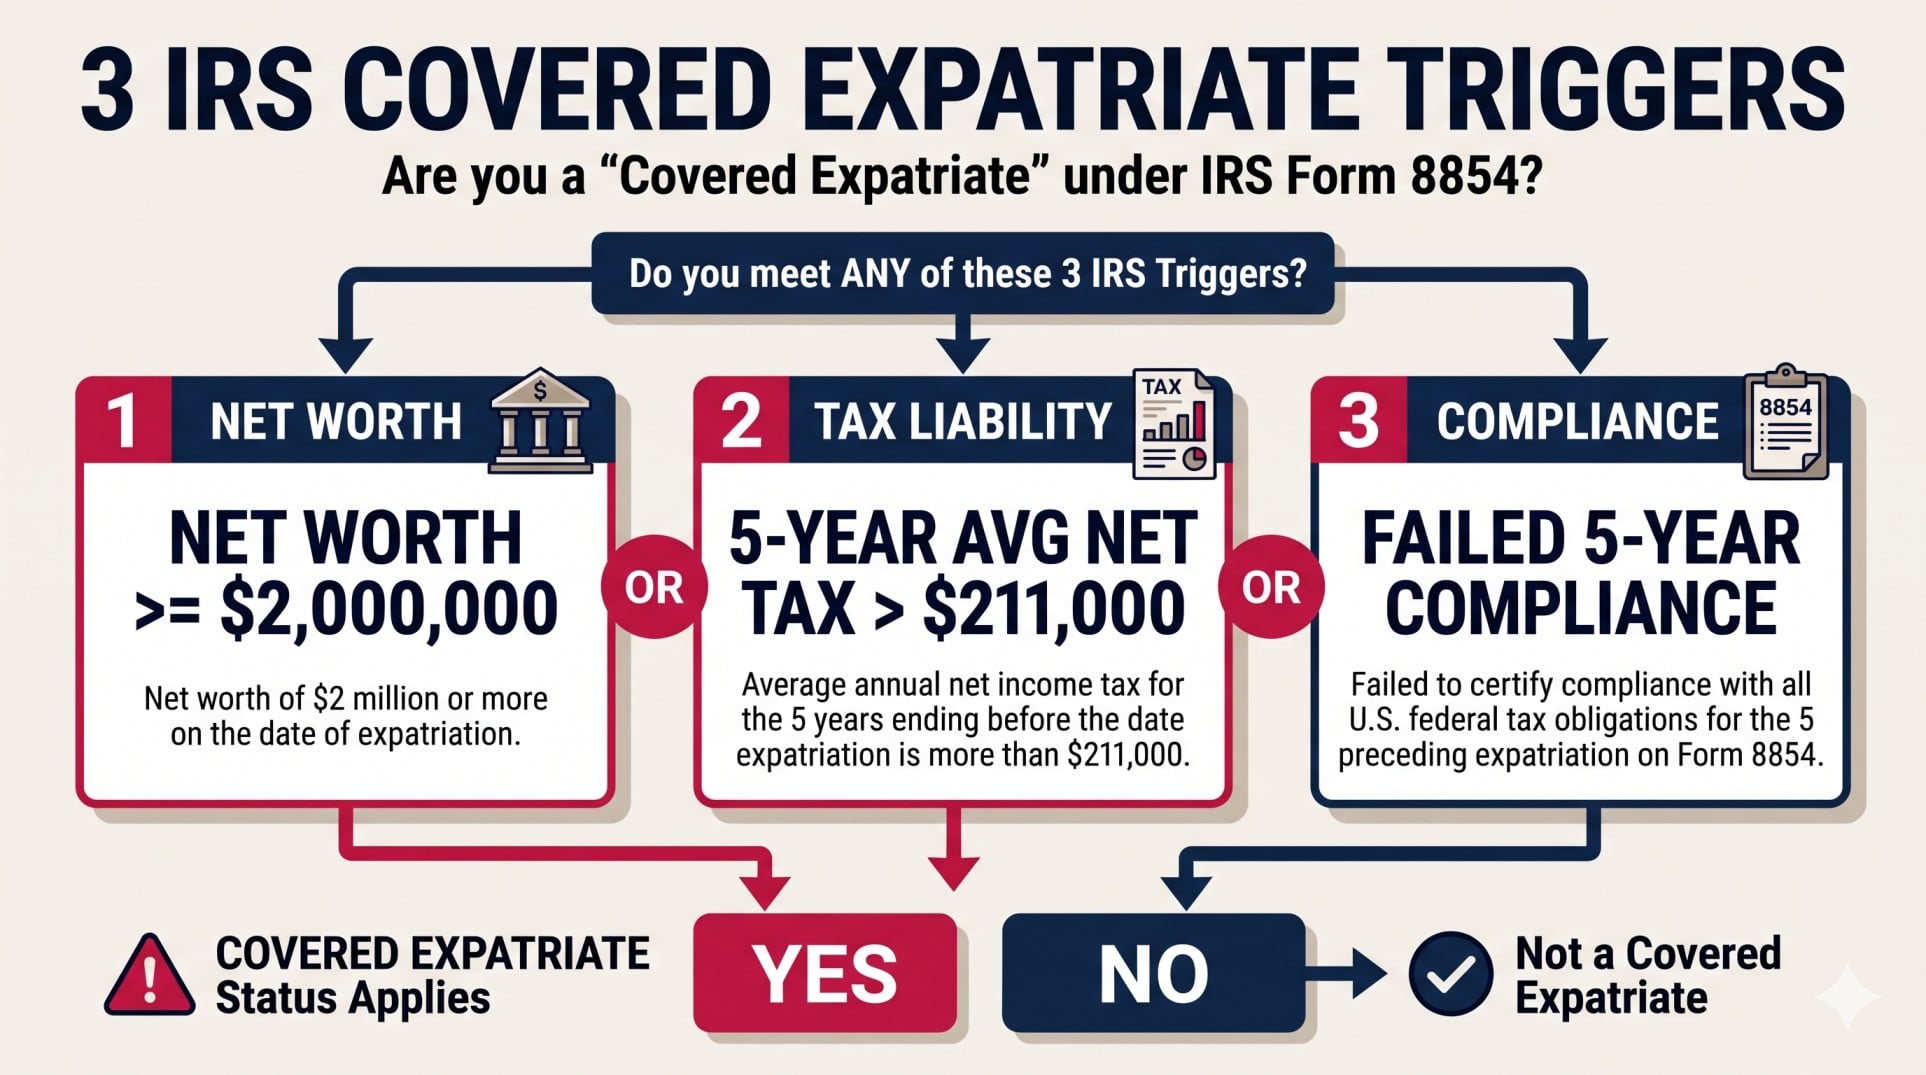
You only owe the IRS exit tax when renouncing US citizenship in 2026 if you are classified as a covered expatriate under IRC Section 877A(g)(1)(A), which cross-references the three statutory triggers in IRC Section 877(a)(2). Meeting even one of the following three tests on your expatriation date makes you a covered expatriate; if you stay beneath all three thresholds, you exit the US tax system owing $0 in exit tax.
1. The $2,000,000 Net Worth Test (Unindexed Since 2004)
You are a covered expatriate if your personal net worth is $2,000,000 or more on the exact date of your expatriation. Unlike almost every other threshold in the tax code, Congress never indexed the $2,000,000 net worth figure for inflation—meaning it has remained frozen at $2 million since 2004.
Under IRS Notice 2009-85 and Notice 97-19, your net worth includes the fair market value (minus bona fide liabilities like mortgages and margin loans) of every worldwide interest in property that would be taxable as a gift under IRC Section 2501 if you transferred it on your expatriation date. You must include:
- Foreign and domestic real estate (including your primary residence, vacation homes, and rental properties).
- Cash, brokerage accounts, cryptocurrency, collectibles, automobiles, and personal property.
- The present actuarial value of US retirement accounts (401(k)s, Traditional/Roth IRAs), foreign employer pensions, and unvested deferred compensation.
- Closely held business shares, partnership interests, and beneficial interests in grantor and non-grantor trusts (valued using the two-step allocation and IRC Section 7520 actuarial tables specified in Notice 97-19).
Married couples do not combine their net worth. Each spouse’s net worth is calculated strictly on an individual basis ($2,000,000 per person), dividing jointly held marital or community property according to local property law and legal title.
2. The $211,000 Average Annual Net Income Tax Liability Test
Per IRS Revenue Procedure 2025-32 (Section 4.37), you are a covered expatriate in 2026 if your average annual net income tax liability for the five taxable years ending before your expatriation date (Tax Years 2021, 2022, 2023, 2024, and 2025) is more than $211,000 (up from $206,000 for 2025 expatriations).
Pay close attention to the wording: this test measures your 5-year average net federal income tax paid after subtracting Foreign Tax Credits, not your gross income. If you lived in a high-tax country like the UK or Germany from 2021 through 2025 and used Foreign Tax Credit vs. FEIE strategies for expats to reduce your net US tax bill on Form 1040 Line 24 to $0 each year, your 5-year average net tax liability is $0—even if you earned $1,000,000 per year. However, one critical trap catches married expats: if you filed Married Filing Jointly (Form 1040) during any of the prior five years, you must include 100% of the joint tax liability from that return in your personal 5-year average calculation, even if your spouse earned all the income.
3. The 5-Year Tax Compliance Certification Test (The Paperwork Trap)
Even if your net worth is $50,000 and your 5-year average tax liability is $0, you automatically become a covered expatriate under IRC Section 877(a)(2)(C) if you fail to certify under penalty of perjury on Part IV, Line 6 of Form 8854 that you have complied with all federal tax obligations for the five taxable years preceding your expatriation year (2021–2025).
Under IRS Notice 2009-85, “all federal tax obligations” means far more than just filing Form 1040. You must have filed complete, accurate returns and paid all taxes, penalties, and interest across income taxes, self-employment taxes, gift taxes, and every mandatory international information return—including Form 5471 (foreign corporations), Form 3520/3520-A (foreign trusts and large foreign gifts), Form 8621 (PFIC foreign mutual funds), and Form 8938 (FATCA). If you have unfiled returns or missing schedules between 2021 and 2025, you must clean them up before signing Form 8854 in 2027.
Statutory Exceptions and IRS Relief Procedures for Former Citizens
The Internal Revenue Code provides two statutory exceptions under IRC Section 877A(g)(1)(B) that exempt qualifying individuals from the $2,000,000 Net Worth Test and the $211,000 Tax Liability Test, alongside a specialized IRS administrative amnesty program for “Accidental Americans.”
Exception 1: Dual Citizens at Birth
Even if your net worth is $10 million or your 5-year average US tax exceeds $211,000, you will not be treated as a covered expatriate if you satisfy all four of these conditions:
- You became at birth a citizen of the United States and also a citizen of another country.
- On your expatriation date, you continue to be a citizen of, and are taxed as a resident of, that other country.
- You have been a tax resident of the United States (under the substantial presence test of IRC Section 7701(b)(1)(A)(ii)) for no more than 10 taxable years during the 15-taxable-year period ending with the taxable year during which the expatriation occurs.
- You still certify 5 years of full federal tax compliance on Form 8854. (The dual-citizen exception waives the wealth and tax liability tests, never the 5-year compliance certification test).
Exception 2: Minors Relinquishing Citizenship Before Age 18½
An individual is exempt from the Net Worth Test and Tax Liability Test if they relinquish US citizenship before reaching age 18½, provided they were a US tax resident for no more than 10 taxable years before the date of relinquishment—and still file Form 8854 certifying 5 years of tax compliance.
IRS Relief Procedures for Certain Former Citizens (Accidental Americans)
What if you were born in a US hospital to foreign parents, moved abroad as an infant, never obtained a Social Security Number, and never filed a US tax return? Under the IRS Relief Procedures for Certain Former Citizens (which remain active in 2026), qualifying individuals who relinquished citizenship after March 18, 2010, can achieve full compliance and avoid covered expatriate status without paying back taxes, penalties, or interest—and without needing an SSN.
To qualify for these relief procedures in 2026/2027, you must meet every single criterion:
- Your past failure to file US tax returns and pay taxes was due to non-willful conduct.
- You have zero prior filing history as a US citizen or resident (filing a Form 1040-NR under the mistaken good-faith belief you were a nonresident alien does not disqualify you).
- Your net worth was under $2,000,000 both on your date of expatriation and on the date of your relief submission.
- Your aggregate total US tax liability across the 6-year submission window (the year of expatriation plus the 5 prior tax years) is $25,000 or less after applying foreign tax credits and the FEIE (if claimed on timely returns, note that late returns under this relief calculate tax before penalties). If your 6-year aggregate tax is $25,000 or under, the IRS waives the entire tax payment completely.
- You mail a paper package containing 6 years of tax returns (5 prior years of Form 1040 plus the dual-status expatriation return, Form 8854, and all required information returns) with “Relief for Certain Former Citizens” written in red ink across the top of each first page.
2025 vs. 2026 Expatriation Thresholds and Asset Treatment Matrix
Planning for the expatriation tax 2026 requires using the updated inflation figures from IRS Revenue Procedure 2025-32 alongside the permanent estate and gift tax provisions enacted by the One Big Beautiful Bill Act (Public Law 119-21).
| Expatriation Tax Metric / Threshold | Tax Year 2025 (Expatriated in 2025) | Tax Year 2026 (Expatriated in 2026) | Statutory Authority / Form |
|---|---|---|---|
| 5-Year Average Annual Net Income Tax Trigger | More than $206,000 | More than $211,000 | IRC Sec. 877(a)(2)(A); Rev. Proc. 2025-32 Sec. 4.37 |
| Net Worth Covered Expatriate Trigger | $2,000,000 or more | $2,000,000 or more (Unindexed) | IRC Sec. 877(a)(2)(B); Form 8854 Part II |
| Mark-to-Market Deemed Sale Gain Exclusion | $890,000 | $910,000 | IRC Sec. 877A(a)(3); Rev. Proc. 2025-32 Sec. 4.38 |
| State Dept. CLN Renunciation Fee | $2,350 | $450 (Effective April 13, 2026) | 22 CFR 22.1; Form DS-4083 |
| Lifetime Federal Estate & Gift Tax Exemption | $13,990,000 | $15,000,000 ($30M married) | OBBBA; IRC Sec. 2010(c)(3) |
| Annual Gift Tax Exclusion (Per Donee) | $19,000 | $19,000 | IRC Sec. 2503(b); Rev. Proc. 2025-32 Sec. 4.42(1) |
| Annual Gift Exclusion to Non-Citizen Spouse | $190,000 | $194,000 | IRC Sec. 2523(i)(2); Rev. Proc. 2025-32 Sec. 4.42(2) |
| Section 2801 Covered Gift / Bequest Tax Rate | 40% (Above $19,000 exclusion) | 40% (Above $19,000 exclusion) | IRC Sec. 2801; T.D. 10027; Form 708 |
Once an individual is classified as a covered expatriate in 2026, IRC Section 877A does not treat all assets equally. Instead, the IRS divides your worldwide balance sheet into four distinct statutory categories—only one of which receives the $910,000 exclusion.
| Asset Category Under IRC Sec. 877A | Examples of Included Assets | 2026 Exit Tax Rule & Rate | Eligible for $910,000 Exclusion? |
|---|---|---|---|
| 1. General Mark-to-Market Property (IRC Sec. 877A(a)) |
Stocks, ETFs, crypto, primary residence, rental real estate, private business shares, Roth IRAs | Deemed sold at FMV the day before expatriation; net gain above exclusion taxed at 15%/20% LTCG + 3.8% NIIT (or ordinary rates) | Yes (Allocated pro rata across all built-in gain assets) |
| 2. Specified Tax-Deferred Accounts (IRC Sec. 877A(e)) |
Traditional IRAs, SEP IRAs, SIMPLE IRAs, 529 plans, HSAs, Coverdell ESAs | Deemed 100% distributed the day before expatriation; taxed at ordinary rates up to 37% (10% early penalty waived) | No (Taxed from the very first dollar) |
| 3. Eligible Deferred Compensation (IRC Sec. 877A(d)(1)/(3)) |
US 401(k), 403(b), US stock options (with US payor & Form W-8CE filed within 30 days) | No immediate lump-sum tax; payor withholds flat 30% tax when actual future distributions are paid | No (Treaty benefits permanently waived) |
| 4. Ineligible Deferred Compensation (IRC Sec. 877A(d)(2)) |
Foreign employer pensions (e.g., UK SIPP, Australian Super, Canadian RPP), US plans without timely W-8CE | Present value of accrued benefit taxed immediately as ordinary income up to 37% on the day before expatriation | No (Frequently triggers double taxation without foreign credit relief) |
| 5. Non-Grantor Trust Interests (IRC Sec. 877A(f)) |
Beneficial interests in domestic or foreign non-grantor trusts held day before expatriation | Trusteewithholds flat 30% tax on the taxable portion of any future direct or indirect distribution | No (Unless electing deemed settlement via IRS Private Letter Ruling) |
How the Expatriation Tax 2026 Is Calculated (Mark-to-Market & $910,000 Exclusion)
Calculating the expatriation tax 2026 requires valuing every asset you own at fair market value on the day before your expatriation date, sorting those assets into their IRC Section 877A buckets, and computing the resulting capital gains and ordinary income tax on your final Form 1040.
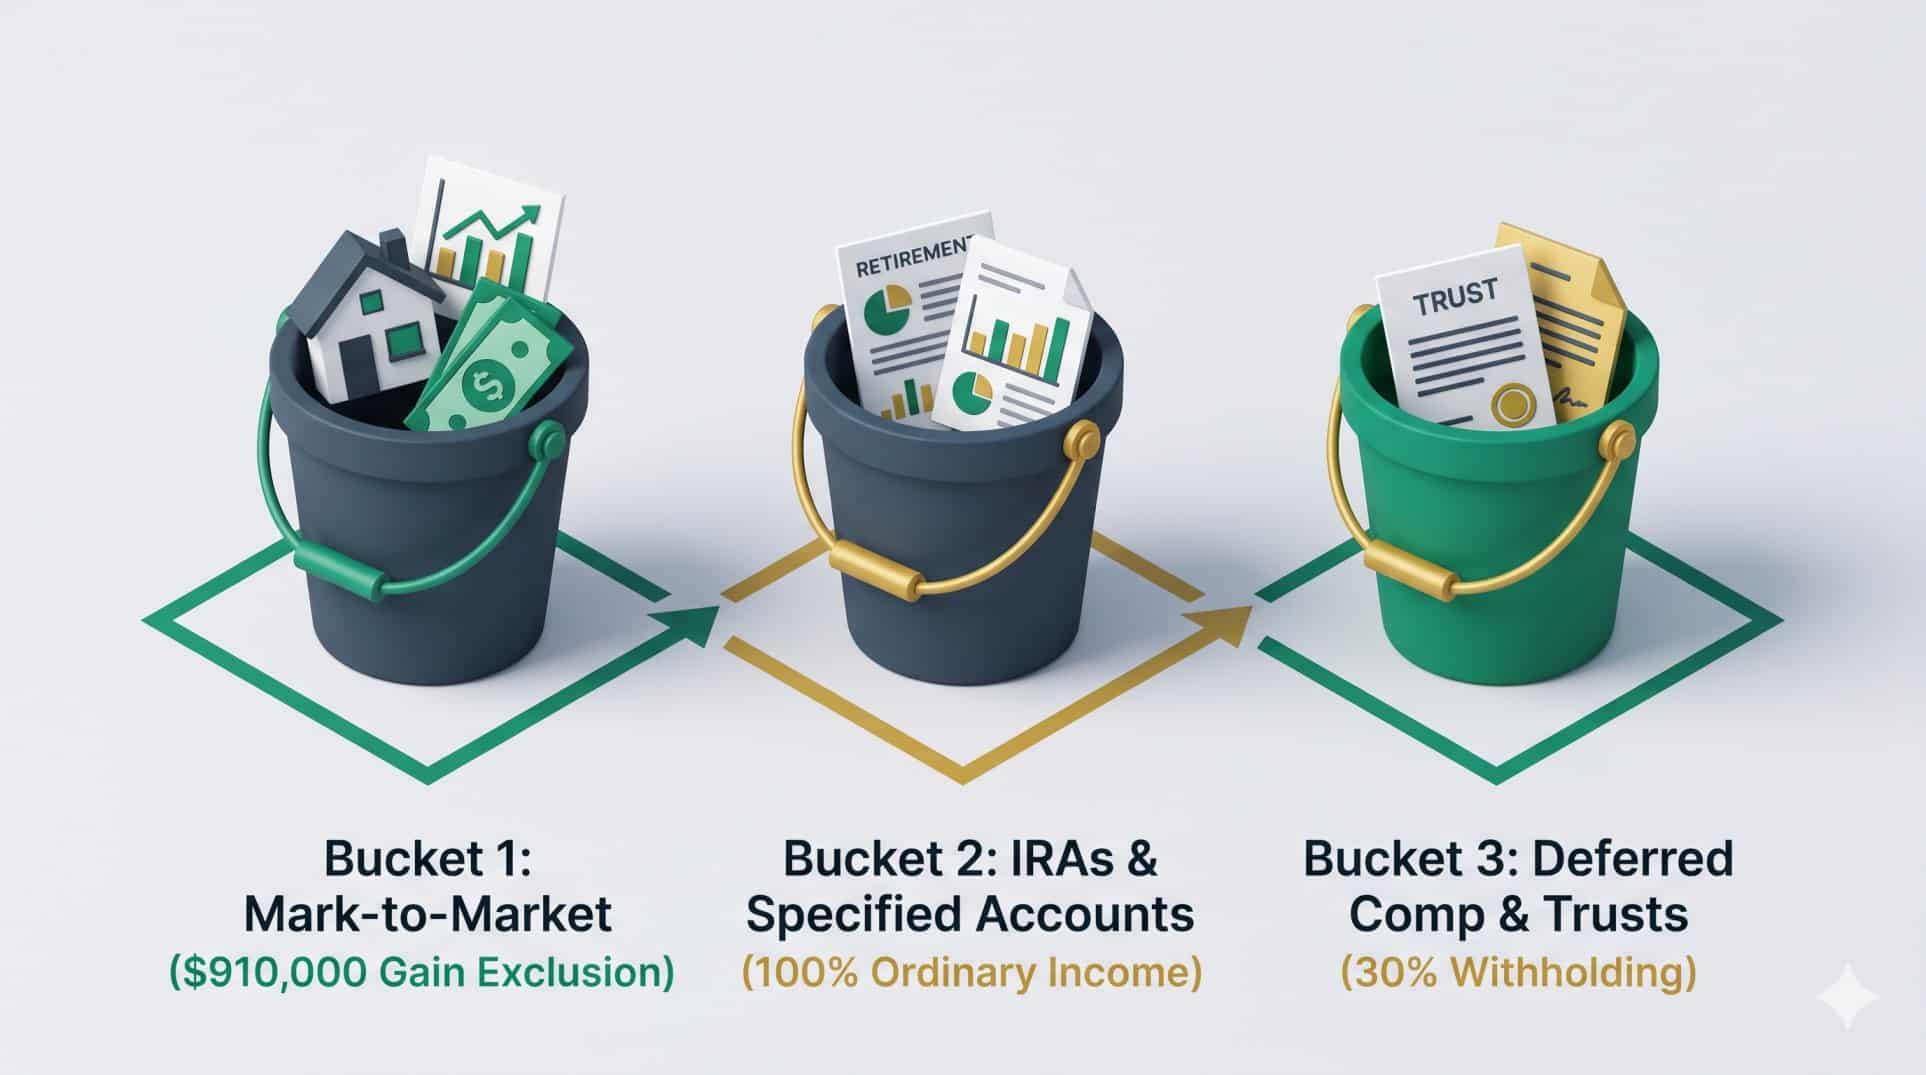
Bucket 1: Mark-to-Market Deemed Sale and Pro-Rata Exclusion Allocation
Under IRC Section 877A(a)(1), all worldwide property not falling into a retirement or trust exception is treated as sold for its fair market value on the day before your expatriation date. Any built-in gains must be recognized immediately (and built-in losses are allowed to the extent permitted by the Code, except wash-sale rules under Section 1091 do not apply). Importantly, when calculating the deemed gain on your primary residence, you cannot claim the IRC Section 121 principal residence exclusion ($250,000 Single / $500,000 Married) against the mark-to-market deemed sale—if you want the Section 121 home sale exclusion, you must physically sell the home before expatriating.
Next, you apply the 2026 statutory exclusion of $910,000 under IRC Section 877A(a)(3) and Rev. Proc. 2025-32. Under Section 3.C of IRS Notice 2009-85, you do not simply subtract $910,000 from your bottom-line net capital gain. Instead, you must allocate the $910,000 exclusion pro rata among all built-in gain properties (ignoring loss properties) using this exact formula:
Exclusion Allocated to Asset = $910,000 × (Built-In Gain of Specific Asset ÷ Total Built-In Gain of All Gain Assets)
This pro-rata rule matters enormously if your portfolio mixes assets taxed at different rates—such as collectibles taxed at 28%, short-term capital gains taxed up to 37%, depreciable real estate subject to 25% Section 1250 unrecaptured depreciation, and long-term stocks taxed at 15% or 20% (plus the 3.8% Net Investment Income Tax on Form 8960 for MAGI above $200,000 Single / $250,000 MFJ).
Green Card Basis Step-Up Relief (IRC Section 877A(h)(2)): For long-term green card holders (not US citizens from birth), any property you owned before you first became a US tax resident receives an automatic basis floor equal to its fair market value on the first day of your US residency (excluding US real property interests and property used in a US trade or business), unless you affirmatively elect out on Form 8854.
Buckets 2 & 3: The Retirement Account Tax Accelerations
The harshest financial shock of the IRS exit tax hits retirement savings, where the $910,000 exclusion is completely unavailable:
- Specified Tax-Deferred Accounts (Traditional IRAs, SEP/SIMPLE IRAs, HSAs, 529 Plans): Under IRC Section 877A(e), you are treated as receiving a lump-sum distribution of your entire account balance on the day before your expatriation date. If you hold an $800,000 Traditional IRA, all $800,000 is added directly to your ordinary income on your final 2026 Form 1040, pushing you straight into the 35% and 37% marginal tax brackets (which begins at $640,600 for Single filers in 2026). While the 10% early withdrawal penalty under IRC Section 72(t) is waived, your host country will not recognize this fictitious US “deemed distribution,” meaning you will likely pay tax a second time to your foreign government when you actually withdraw the cash in retirement.
- Eligible Deferred Compensation (US 401(k)s and Employer Plans): If you have a US 401(k) with a US plan administrator, you can avoid immediate lump-sum taxation ONLY if you submit IRS Form W-8CE (Notice of Expatriation and Waiver of Treaty Benefits) to the plan payor within 30 days of your expatriation date (or before the first post-expatriation distribution, if earlier). Doing so classifies the 401(k) as “eligible deferred compensation,” meaning you pay $0 tax in 2026, and the US custodian withholds a flat 30% tax as distributions occur in the future.
- Ineligible Deferred Compensation (Foreign Pensions): Because a foreign pension administrator (such as a UK workplace pension, Canadian RPP, or Australian Superannuation fund) is not a US payor committed to withholding 30% for the IRS, foreign pensions are classified as ineligible deferred compensation. You must calculate the present value of your accrued foreign pension on the day before expatriation and pay immediate US ordinary income tax up to 37% on that phantom balance—without a dime of cash leaving the locked pension fund.
4 Real-World 2026 Expatriation Scenarios (With Step-by-Step Math)
To see how these rules interact in real life, review these four mathematical examples for taxpayers renouncing US citizenship in 2026 or abandoning long-term green cards.
Scenario 1: The Compliant Expat Under All Thresholds ($0 Exit Tax)
- Taxpayer Profile: Liam, Single US citizen living in Dublin, Ireland, renounces at the US Embassy on August 14, 2026.
- 2026 Metrics: Net worth is $1,450,000 ($600,000 home equity, $500,000 brokerage account, $350,000 Irish pension). His 5-year average US net income tax (2021–2025) is $0 (fully offset by Irish Foreign Tax Credits). All 2021–2025 tax returns and FBARs were timely filed.
- Exit Tax Calculation: Liam’s net worth is below $2,000,000, his 5-year average net tax is below $211,000, and he certifies 5 years of compliance on Form 8854. He is not a covered expatriate.
- 2026 Result: Liam pays the $450 State Department CLN fee and owes $0 in IRS exit tax. His Irish pension and brokerage gains escape Section 877A completely.
Scenario 2: Covered Expatriate Shielded by the $910,000 Gain Exclusion ($0 Exit Tax)
- Taxpayer Profile: Sophia, Single US citizen in Zurich, Switzerland, renounces on September 10, 2026.
- 2026 Metrics: Worldwide net worth is $2,600,000, consisting of $800,000 in cash and a taxable brokerage portfolio worth $1,800,000 with a cost basis of $1,050,000 (she holds no retirement accounts or trusts).
- Exit Tax Calculation: Because her $2,600,000 net worth exceeds the $2,000,000 threshold, Sophia is a covered expatriate. Under the Section 877A(a) mark-to-market rule, her brokerage portfolio is deemed sold on September 9, 2026, for $1,800,000, generating a built-in long-term capital gain of $750,000 ($1,800,000 FMV minus $1,050,000 basis). She applies the 2026 gain exclusion of $910,000. Because her $750,000 total gain is less than the $910,000 exclusion, her taxable mark-to-market gain is reduced to $0.
- 2026 Result: Despite being a covered expatriate, Sophia owes $0 in Section 877A exit tax (though she remains subject to IRC Section 2801 rules if she later gifts money to US citizens).
Scenario 3: High-Net-Worth Tech Founder With an IRA and Foreign Pension (Heavy Tax Hit)
- Taxpayer Profile: Vikram, a 12-year green card holder (Long-Term Resident), files Form I-407 on November 3, 2026, after moving back to Singapore. Single filer with $100,000 in pre-expatriation salary (which absorbs his standard deduction and lower brackets).
- 2026 Worldwide Assets on Nov 2, 2026:
- Tech stock portfolio: FMV $3,000,000; Cost basis $500,000 (Built-in LTCG = $2,500,000).
- US Rental Condo: FMV $1,200,000; Cost basis $700,000 (Built-in LTCG = $500,000; zero prior depreciation for simplicity).
- Traditional IRA (Bucket 2 Specified Account): Balance = $600,000.
- Total Net Worth = $4,800,000 (Covered Expatriate).
- Step 1 (Mark-to-Market Pro-Rata Exclusion): Total built-in capital gain across Bucket 1 assets is $3,000,000 ($2,500,000 stock + $500,000 condo). The $910,000 2026 exclusion is allocated pro rata:
- Stock Exclusion: $910,000 × ($2.5M ÷ $3.0M) = $758,333 -> Taxable Stock Gain = $1,741,667.
- Condo Exclusion: $910,000 × ($0.5M ÷ $3.0M) = $151,667 -> Taxable Condo Gain = $348,333.
- Total Net Taxable Long-Term Capital Gain = $2,090,000 ($3,000,000 minus $910,000).
- Step 2 (Traditional IRA Deemed Distribution): The entire $600,000 Traditional IRA is deemed distributed on November 2, 2026, with zero exclusion allowed.
- Step 3 (2026 Tax Computation):
- The $600,000 IRA distribution is taxed at 2026 ordinary brackets (32%, 35%, and 37%), generating approximately $206,400 in ordinary income tax.
- The $2,090,000 net mark-to-market capital gain sits above the 2026 20% LTCG threshold ($545,500 for Single filers) and is also subject to the 3.8% Net Investment Income Tax (NIIT), resulting in an effective 23.8% rate on the gain = $497,420.
- 2026 Result: Vikram owes a combined $703,820 in IRS exit tax on April 15, 2027, despite not selling a single share of stock or withdrawing a dollar from his IRA.
Scenario 4: Dual Citizen at Birth With $4.5M Net Worth (Statutory Exemption)
- Taxpayer Profile: Camille was born in Montreal to a Canadian mother and an American father, acquiring both US and Canadian citizenship at birth. She has lived and paid taxes in Canada her entire life (0 years of US residency) and renounces her US citizenship in Toronto on October 15, 2026.
- 2026 Metrics: Net worth is $4,500,000 CAD/USD equivalent. She timely filed all 2021–2025 US tax returns, FBARs, and Form 8938 disclosures.
- 2026 Result: Under IRC Section 877A(g)(1)(B)(i), Camille qualifies for the Dual Citizen at Birth Exception and certifies 5 years of compliance on Form 8854. She is exempt from the $2,000,000 net worth test, is not a covered expatriate, and owes $0 in exit tax on her $4,500,000 estate.
Business Owners, Green Card Holders, and the Section 2801 Inheritance Trap
Beyond individual stock portfolios and retirement accounts, the expatriation tax 2026 creates complex structural traps for green card holders, business owners with domestic or foreign corporations, and parents leaving inheritances to US-citizen children.
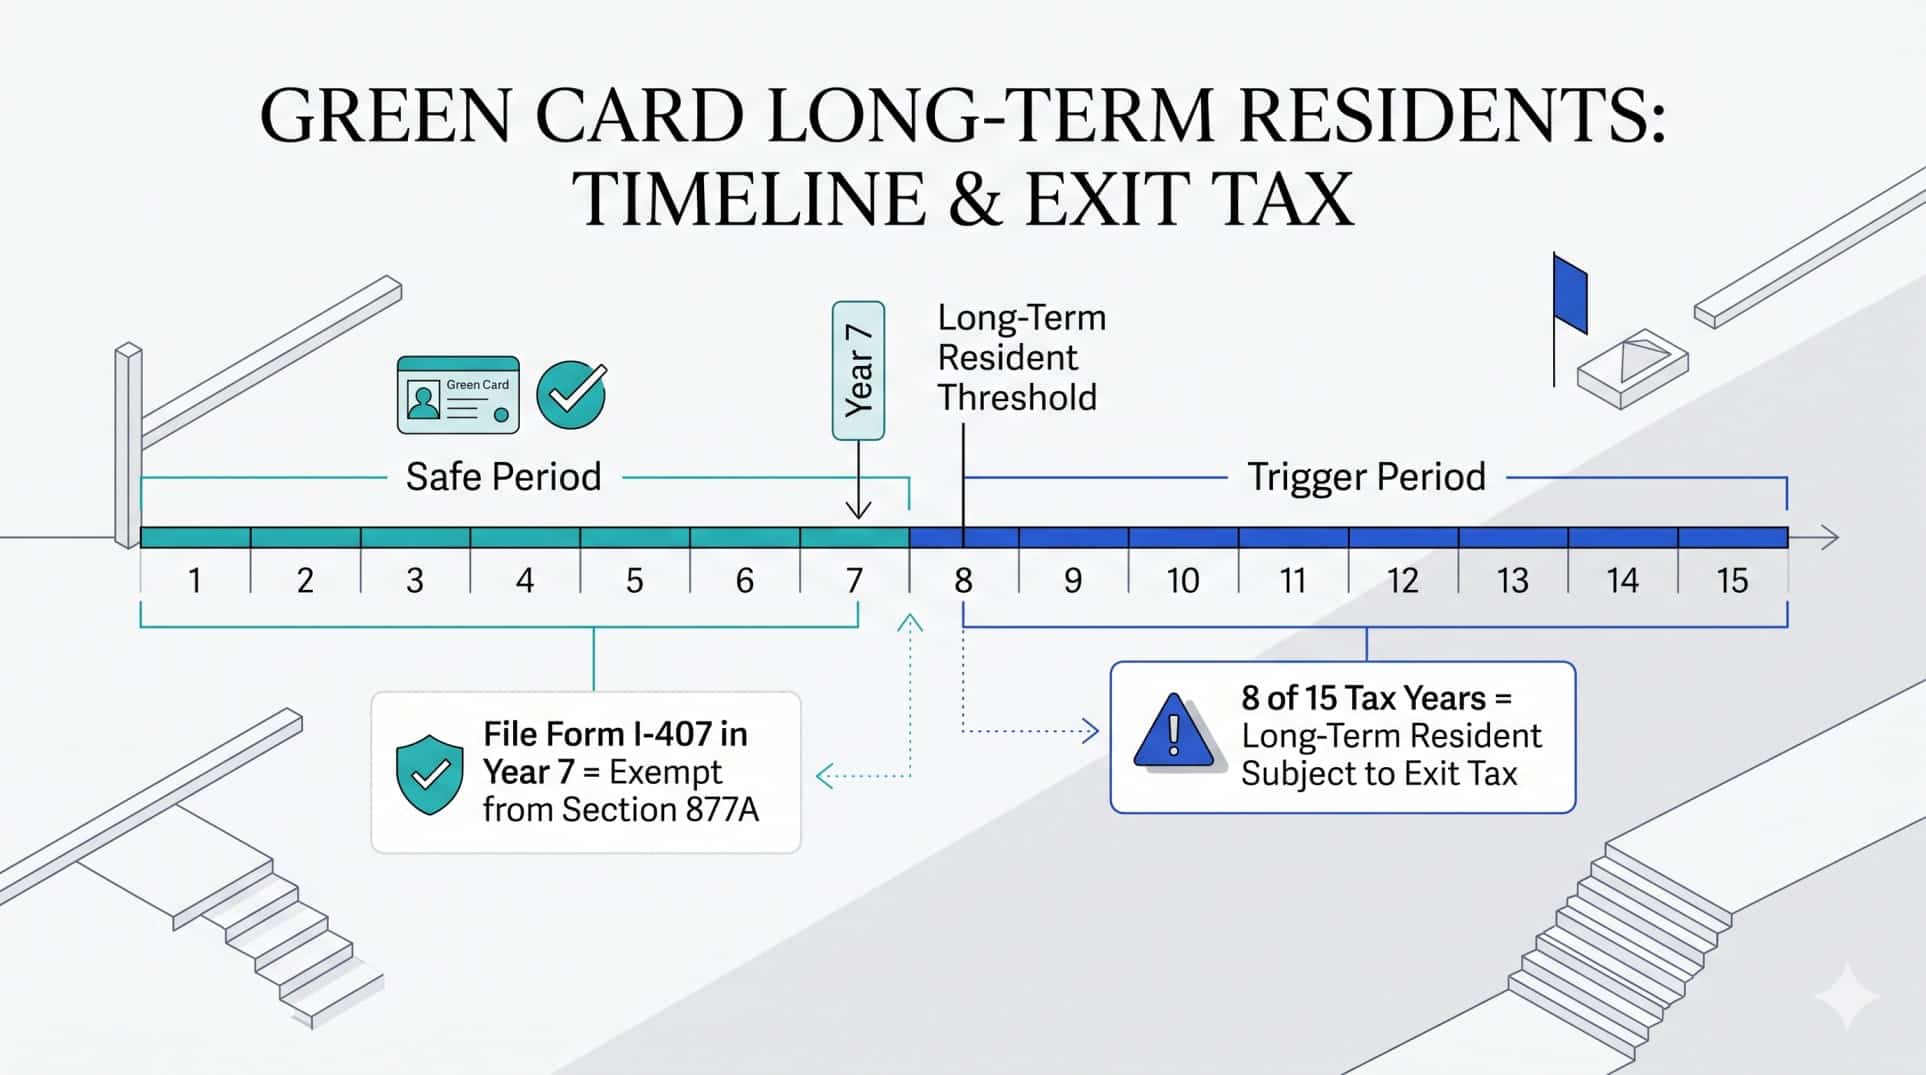
Green Card Holders: Counting the “8 of 15 Years” Clock
Under IRC Section 877(e)(2), a green card holder is only subject to the expatriation rules if they are a “Long-Term Resident” (LTR)—defined as holding lawful permanent resident status in at least 8 of the last 15 taxable years ending with the year residency ends. Three mechanical rules catch green card holders by surprise:
- Any Single Day Counts as a Full Year: If USCIS approved your green card on December 28, 2019, and you file Form I-407 on January 3, 2026, you held the card in 2019, 2020, 2021, 2022, 2023, 2024, 2025, and 2026—hitting 8 taxable years and triggering the exit tax. Had you filed Form I-407 on December 30, 2025 (Year 7), you would have avoided Long-Term Resident status and owed $0 regardless of whether you were worth $50 million.
- Expired Plastic Cards Still Count: Letting your physical green card expire or moving abroad does not stop the 8-year tax clock under IRC Section 7701(b)(6). Your tax status continues running until you formally file Form I-407 or have status administratively/judicially revoked.
- The Tax Treaty Tie-Breaker Trap: If you are already in Year 8+ and file Form 8833 to claim non-resident tie-breaker benefits under a US tax treaty, that treaty election itself is treated as an expatriating act that triggers Form 8854 and the Section 877A exit tax. (Conversely, if you claimed treaty tie-breaker status in an earlier year before hitting 8 years and waived green card benefits, that treaty year does not count toward the 8-year clock).
Business Entities: S-Corps, Partnerships, and Foreign Corporations
If you own a closely held business, expatriating triggers immediate entity-level and valuation consequences:
- S-Corporations (Form 1120-S): Under IRC Section 1361(b)(1)(C), a nonresident alien is prohibited from being an S-Corporation shareholder. The exact moment you renounce your US citizenship or abandon your green card in 2026, your S-Corporation election automatically terminates, converting the company into a taxable C-Corporation unless you restructure or sell/transfer the shares prior to expatriation.
- Private C-Corps, LLCs, and Foreign Corporations (Form 5471): For a covered expatriate, private business interests must be appraised at fair market value on the day before expatriation using IRS-accepted valuation methodologies (Revenue Ruling 59-60), applying documented discounts for lack of marketability (DLOM) and minority ownership where applicable. If you own a Controlled Foreign Corporation (CFC), your final Form 1040 must also account for any final Subpart F or Section 951A GILTI inclusions up to your expatriation date.
The IRC Section 2801 “Shadow Estate Tax” (40% on US Heirs & Form 708)
Becoming a covered expatriate carries a permanent consequence that outlives your expatriation: the IRC Section 2801 tax on covered gifts and bequests. On January 14, 2025, the Treasury and IRS published Final Regulations (T.D. 10027) enforcing Section 2801 for all gifts and inheritances received on or after January 1, 2025.
How Section 2801 Works in 2026: If you are a covered expatriate and you later make a gift or leave an inheritance (at any point in the future—there is no 10-year expiration) to a US citizen or US resident, the US recipient must file IRS Form 708 and pay a flat 40% tax on the value of the gift or bequest above the 2026 annual exclusion of $19,000. Unlike normal citizens who enjoy the $15,000,000 lifetime exemption, covered expatriates lose their lifetime estate and gift exemption entirely once they expatriate.
Deferring the Exit Tax (IRC Section 877A(b)) & Sticky State Rules
Can you defer paying the mark-to-market exit tax on illiquid real estate or private company stock? Technically, IRC Section 877A(b) allows covered expatriates to elect to defer the tax on specific mark-to-market assets until the asset is actually sold or at death. However, to qualify for deferral, you must execute a formal tax deferral agreement with the IRS, furnish “adequate security” (such as a surety bond or bank letter of credit acceptable to the Treasury), appoint a US agent, permanently waive all tax treaty rights, and pay continuous IRS underpayment interest every year. Because few banks issue multi-year tax bonds for former citizens, deferral is rarely practical.
Finally, watch out for state tax exposure. While states like California do not impose a standalone state “mark-to-market” deemed-sale exit tax under Section 877A, if you have not properly severed your state domicile with a “sticky state” (California, New York, Virginia, New Mexico, or South Carolina) before taking actual pre-expatriation IRA distributions or realizing capital gains, that state will demand state income tax (up to 13.3% in California) on your pre-exit liquidations.
Pre-Expatriation Tax Planning: Legal Ways to Avoid Covered Status in 2026
Because the three covered expatriate tests are evaluated strictly on the date of expatriation, proactive planning before you attend your consular appointment can legally keep you out of covered expatriate status—or slash your deemed-sale tax bill.
1. Pre-Expatriation Gifting Using the $15,000,000 OBBBA Exemption
If your net worth sits at $3,500,000, you will fail the $2,000,000 Net Worth Test if you renounce tomorrow. However, under the One Big Beautiful Bill Act (OBBBA), every US citizen and domiciliary enjoys a permanent $15,000,000 unified federal gift and estate tax exemption in 2026—plus a $19,000 annual gift exclusion per donee and a $194,000 annual exclusion for gifts to a non-citizen spouse (under IRC Section 2523(i)(2) and Rev. Proc. 2025-32).
By gifting $1,600,000 of assets irrevocably to your spouse, adult children, or an irrevocable trust in the calendar year before your expatriation year (and timely filing IRS Form 709 to report the gift against your $15,000,000 lifetime exemption), you reduce your personal net worth to $1,900,000—dropping cleanly beneath the $2,000,000 threshold, avoiding covered expatriate status, and shielding future inheritances from the 40% Section 2801 tax. Check our 2026 federal estate and gift tax exemption guide under the OBBBA for complete Form 709 mechanics.
2. Fixing Unfiled Back Taxes Before You Renounce
Never attend a renunciation interview if you have unfiled returns or missing FBARs/Forms 8938 from the prior five years. If you do not qualify for the narrow Relief Procedures for Certain Former Citizens (for instance, because your net worth exceeds $2 million or you previously filed US tax returns), use the IRS Streamlined Foreign Offshore Procedures (filing 3 years of back tax returns, 6 years of FBARs, and Form 14653 with a 0% penalty) or file delinquent returns so that you can truthfully check “Yes” on the 5-year compliance certification on Form 8854. Review our FBAR and Form 8938 foreign asset reporting guide to verify you haven’t missed a mandatory disclosure.
3. Selling Your Primary Residence and Harvesting Capital Losses First
If you will be a covered expatriate and own a primary residence with $500,000 of built-in appreciation, selling the home before your expatriation date lets you claim the IRC Section 121 exclusion ($250,000 Single / $500,000 MFJ) tax-free, preserving your full $910,000 Section 877A exclusion for your stock portfolio. Similarly, if you hold an underwater asset with a built-in capital loss that might be restricted under personal-use rules, restructuring or liquidating strategic positions before your exit date maximizes tax efficiency.
Step-by-Step Guide: How to File Your Dual-Status Return and Form 8854 in 2027
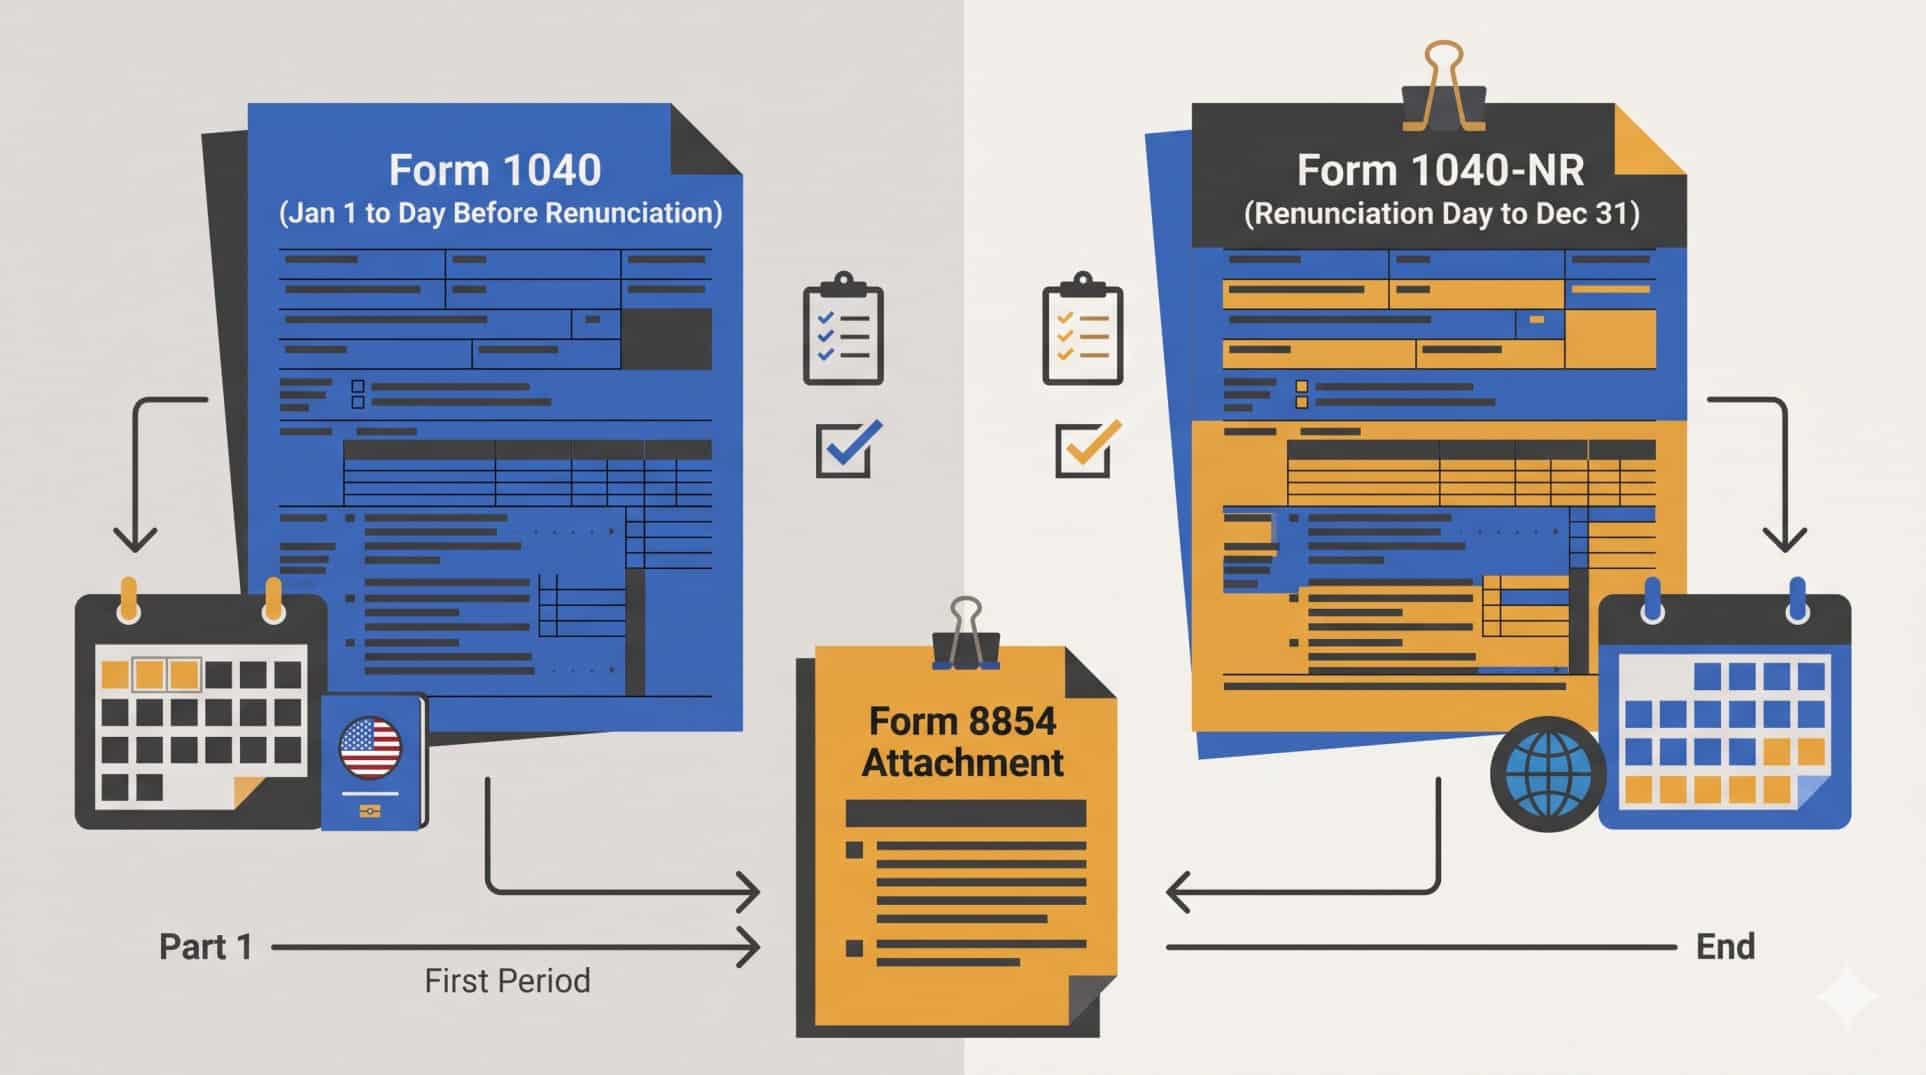
Relinquishing your citizenship or green card in 2026 does not end your paperwork at the embassy door. In calendar year 2027, you must file a final “Dual-Status” tax return and Form 8854 to officially close your account with the IRS.
Step 1: Secure Your Expatriation Date and Form DS-4083 / I-407
Record the exact calendar date in 2026 when you took the oath of renunciation at the US embassy/consulate (or the date USCIS received your Form I-407). Keep a copy of your signed Form DS-4083 (Certificate of Loss of Nationality) or stamped I-407 receipt.
Step 2: Prepare Your 2026 Dual-Status Tax Return (Form 1040-NR + Form 1040 Statement)
Because you were a US citizen or resident for the first part of 2026 and a nonresident alien (NRA) for the remainder of 2026, you are a Dual-Status Taxpayer for Tax Year 2026 (note: dual-status taxpayers cannot file Married Filing Jointly and cannot claim the standard deduction on the NRA portion):
- The Controlling Return (Form 1040-NR): Because you are a nonresident alien on December 31, 2026, Form 1040-NR serves as your primary return cover page, reporting only US-source income earned from your expatriation date through December 31, 2026. Write “Dual-Status Return” across the top of Page 1 of Form 1040-NR.
- The Informational Attachment (Form 1040): Prepare a partial-year Form 1040 (and all required schedules, including Schedule D, Form 8949, Form 2555, or Form 1116) covering worldwide income from January 1, 2026, through the day before your expatriation date. If you are a covered expatriate, all Section 877A deemed-sale capital gains (Schedule D / Form 8949) and deemed IRA distributions (Form 1040 Line 4b) are reported on this partial-year Form 1040 statement. Write “Dual-Status Statement” across the top of Form 1040 and attach it behind Form 1040-NR.
Step 3: Complete Initial Form 8854 (Initial and Annual Expatriation Statement)
Every individual who relinquishes US citizenship or terminates long-term green card residency in 2026 must file Form 8854—even if you are not a covered expatriate:
- Part I: Enter your mailing address, foreign country of tax residence, exact 2026 expatriation date, and how you expatriated.
- Part II: Complete your 5-year net income tax liabilities for 2021, 2022, 2023, 2024, and 2025 on Line 1, enter your net worth on the date of expatriation on Line 2, and answer the 5-year tax compliance certification question under penalty of perjury on Line 6.
- Part IV (Covered Expatriates Only): Complete the Section A Mark-to-Market calculation (listing every asset, FMV, cost basis, built-in gain/loss, and pro-rata allocation of the $910,000 exclusion), Section B for Deferred Compensation and Specified Tax-Deferred Accounts, and Section C for Deferral Elections.
- Part V (All Expatriates): Complete the detailed Worldwide Balance Sheet (Assets and Liabilities at Fair Market Value and Cost Basis) and Income Statement as of your expatriation date. Sign the bottom of Form 8854 under penalty of perjury.
Step 4: Attach Form 8854 and Mail by the 2027 Deadline
Attach your completed Form 8854 directly to your 2026 Dual-Status Return (Form 1040-NR with Form 1040 attached) and file it by the due date of your return in 2027 (April 15, 2027, or June 15, 2027, if living outside the US—extendable to October 15, 2027, via Form 4868). Also double-check the current Form 8854 instructions to confirm whether an additional standalone copy of Form 8854 must be mailed to the IRS Austin, TX service center address. Failing to file a complete and accurate Form 8854 triggers an automatic $10,000 penalty under IRC Section 6039G(c).
Frequently Asked Questions About Renouncing US Citizenship in 2026
1. How much does it cost to renounce US citizenship in 2026?
Effective April 13, 2026, the US Department of State reduced the administrative processing fee for a Certificate of Loss of Nationality (CLN) from $2,350 to $450. Aside from that $450 consular fee, you only owe an IRS exit tax if you meet one of the three covered expatriate triggers (net worth of $2,000,000+, 5-year average net income tax over $211,000, or failure to certify 5 years of tax compliance on Form 8854) and have unrealized gains above $910,000 or taxable retirement/trust accounts.
2. What is the 2026 IRS exit tax exclusion amount?
Under IRS Revenue Procedure 2025-32 (Section 4.38), the IRC Section 877A(a)(3) mark-to-market gain exclusion for Tax Year 2026 is $910,000 per covered expatriate, up from $890,000 in 2025. This means the first $910,000 of net unrealized capital gains across your worldwide mark-to-market assets (such as stocks, real estate, and crypto) is exempt from the exit tax.
3. Does the $910,000 exit tax exclusion apply to my Traditional IRA or 401(k)?
No. Under IRC Section 877A(d) and (e), the $910,000 exclusion only offsets deemed-sale gains on general mark-to-market property. Specified tax-deferred accounts (like Traditional IRAs) are treated as 100% distributed on the day before expatriation and taxed at ordinary rates up to 37% from the very first dollar, while eligible 401(k)s face a flat 30% withholding tax on future distributions if you timely submit Form W-8CE.
4. What happens if I renounce my US citizenship without filing Form 8854?
If you renounce at a US embassy in 2026 and fail to file Form 8854 with your final 2026 return in 2027, you face a statutory $10,000 penalty under IRC Section 6039G and automatically fail the 5-year tax compliance certification test under IRC Section 877(a)(2)(C). Becoming a covered expatriate due to non-filing exposes your worldwide assets to the Section 877A exit tax and subjects future gifts or inheritances to US heirs to the 40% Section 2801 tax.
5. Does the $2,000,000 net worth test apply per person or per married couple?
The $2,000,000 net worth threshold applies strictly per individual, not per married couple. If a husband and wife jointly own $3,600,000 in assets tilted 50/50 ($1,800,000 each) and both renounce in 2026, neither spouse crosses the $2,000,000 net worth threshold—and if they become covered expatriates for another reason, each spouse receives their own separate $910,000 gain exclusion ($1,820,000 combined).
6. How are foreign pensions taxed under the expatriation tax 2026?
For a covered expatriate, foreign employer and personal pensions (such as a UK SIPP/workplace pension, Canadian RPP, or Australian Superannuation) are classified as ineligible deferred compensation under IRC Section 877A(d)(2) because the foreign custodian is not a US withholding agent. The IRS taxes the entire present actuarial value of your accrued foreign pension on the day before expatriation as ordinary income up to 37%, with no $910,000 exclusion allowed.
7. Do green card holders have to pay the IRS exit tax when leaving the US?
Green card holders are only subject to the Section 877A exit tax and Form 8854 rules if they are Long-Term Residents—meaning they held a green card during any part of at least 8 of the last 15 taxable years ending with the year residency terminates. If you formally abandon your green card via Form I-407 in Year 7 or earlier (and never claimed treaty tie-breaker status in Year 8+), you are 100% exempt from the exit tax regardless of your wealth.
8. Will renouncing US citizenship stop me from receiving US Social Security benefits?
No. Renouncing US citizenship does not forfeit your earned US Social Security retirement benefits, provided you reside in a country where the Social Security Administration is permitted to send payments and often covered by a Totalization Agreement. However, once you become a nonresident alien, your Social Security benefits may be subject to non-resident flat withholding (typically 30% on 85% of the benefit, meaning an effective 25.5% withholding rate) unless reduced or eliminated by an applicable bilateral income tax treaty.
9. Can I still visit the United States after renouncing my citizenship?
Yes, using your foreign passport—either via the Visa Waiver Program (ESTA) if you hold citizenship in an eligible country or by applying for a B-1/B-2 tourist visa. While the Illegal Immigration Reform and Immigrant Responsibility Act of 1996 (Reed Amendment, 8 U.S.C. Section 1182(a)(10)(E)) theoretically bars former citizens who officially state they renounced for tax avoidance purposes, it is rarely enforced in practice provided you never make self-incriminating tax-avoidance statements during your consular interview and complete your final IRS filings properly.
10. What is the IRC Section 2801 tax on gifts and inheritances from covered expatriates?
Under IRC Section 2801 and Final Regulations T.D. 10027 (effective for transfers on or after January 1, 2025), any US citizen or resident who receives a lifetime gift or estate bequest from a covered expatriate must pay a flat 40% tax on the transfer above the $19,000 annual exclusion, reported by the US recipient on IRS Form 708. Non-covered expatriates are completely exempt from Section 2801.
Final Checklist Before Scheduling Your 2026 Consular Appointment
Renouncing US citizenship in 2026 is an irreversible legal act, and the IRS evaluates your covered expatriate status based on the exact snapshot of your finances on the day you sign the oath. Once you take that oath at the embassy or submit Form I-407 in your eighth green card year, it is too late to gift down your net worth below $2,000,000, liquidate a primary residence under Section 121, or restructure an S-Corporation or Traditional IRA.
Before booking your consular appointment, verify that your 2021–2025 federal tax returns, FBARs, and international information forms are 100% complete, calculate your net worth and built-in capital gains against the $910,000 exclusion for the expatriation tax 2026, and model how your retirement accounts will be taxed. Taking the time to clean up your tax history and optimize your balance sheet ensures you file a clean Form 8854 in 2027 and exit the US tax system with zero surprises.
Disclaimer: This content provides general information for educational purposes only and reflects federal tax laws applicable to Tax Year 2026 (returns filed in 2027). Tax laws are complex and subject to change. This article does not constitute professional tax, legal, or accounting advice. Always consult a certified public accountant (CPA), enrolled agent (EA), or qualified tax attorney regarding your specific financial situation. Ourtaxpartner.com is not responsible for any actions taken based on the information provided herein.
